Blog

  • Cambridge BEUDO Net-Zero Guide: 2025–2026 Caps, 2035 Cutoff & May 1 Filing

    Cambridge BEUDO Net-Zero Guide: 2025–2026 Caps, 2035 Cutoff & May 1 Filing

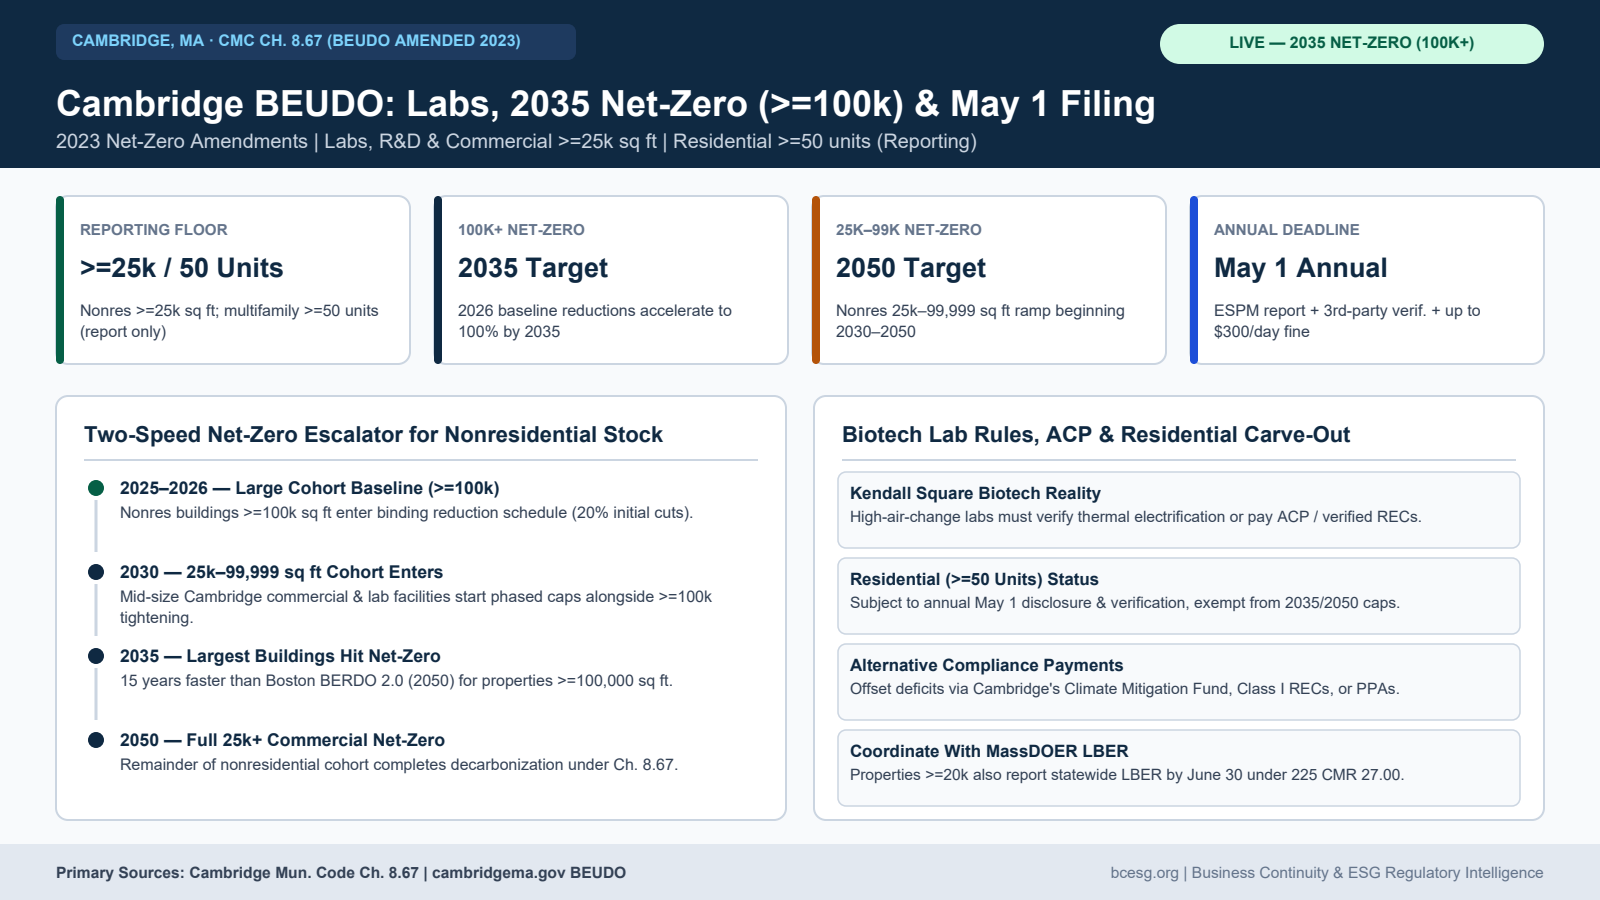
    Short answer: Following its 2023 overhaul under Cambridge Municipal Code Chapter 8.67, Cambridge’s Building Energy Use Disclosure Ordinance (BEUDO) imposes the fastest major commercial net-zero timeline in the United States. Every non-residential parcel >=100,000 sq ft entered phased GHG emissions reductions across 2025–2026 and must hit net-zero emissions by 2035 — fully fifteen years ahead of Boston’s 2050 horizon.

    For Kendall Square life-science laboratories, university buildings, and large corporate campuses, a 2035 zero-carbon finish line puts immediate pressure on electrification capital cycles, green-power contracting, and Massachusetts LBER (225 CMR 27.00) data integration. Compare neighboring municipal mechanics in our Boston BERDO 2.0 Guide and Newton & Lexington MA Guide.

    Statutory Status at a Glance
    • Large Non-Residential (>=100,000 sq ft): Annual May 1 Portfolio Manager reporting; 20% baseline reduction already started in 2025, escalating toward 60% in 2030 and 100% net-zero in 2035.
    • Mid-Size Non-Residential (25,000–99,999 sq ft): Annual May 1 energy/GHG disclosure active now; emissions caps take effect in 2030 (40% reduction) reaching net-zero by 2050.
    • Multifamily Residential (>=50 units): Annual May 1 energy and water benchmarking mandatory; no BEUDO emissions caps currently apply to purely residential buildings >=50 units.
    • Enforcement & Compliance Tools: Includes Cambridge-approved Class I RECs / verified PPAs, Alternative Compliance Payments ($234/MTCO2e), Hardship Compliance Plans, and statutory $300/day noncompliance penalties.
    Print-First Compliance Brief

    Download the Cambridge BEUDO 2035 Net-Zero Playbook

    2-page Print-First PDF mapping Cambridge Ch. 8.67’s accelerated 2035 net-zero deadline for >=100k sq ft nonresidential assets vs. 2050 timelines.

    Why 2035 Changes Lease, Lab HVAC & Financing Math in Cambridge

    Conventional commercial lease terms run seven to ten years — meaning any lease signed today for a 100,000+ sq ft Cambridge property extends squarely across the 2035 net-zero mandate. High-air-change biomedical laboratories and steam-heated offices cannot treat decarbonization as a post-2040 renovation problem; owners must evaluate central plant heat-recovery chillers, district energy contracts, or multi-year green-power PPAs inside current capital plans.

    Cambridge provides temporary flexibility through qualified third-party RECs and Alternative Compliance Payments ($234/MTCO2e), as well as Portfolio Compliance pooling and Review Board extensions, yet each option requires structured documentation ahead of annual May 1 filings.

    • Baseline Verification Matters: Because percentage reductions scale against historic asset/baseline emissions under Ch. 8.67, verifying utility meter boundaries early prevents overstated reduction burdens.
    • Residential Exemption Scope: Mixed-use towers containing >=25,000 sq ft of non-residential retail or commercial floorspace remain subject to non-residential BEUDO targets on those portions.
    Property CategoryBenchmarking (Annual May 1)Emissions Caps & Net-Zero CutoffFlexibility & Violations
    Non-Residential >=100,000 sfRequired (ENERGY STAR PM)Active 2025–2026 -> Net-Zero 2035Qualified RECs/PPAs, $234/t ACP, $300/day fine
    Non-Residential 25k–99,999 sfRequired (ENERGY STAR PM)Caps start 2030 -> Net-Zero 2050Phased targets + hardship/board plans
    Residential >=50 unitsRequired (ENERGY STAR PM)Disclosure only (no BEUDO emissions cap)$300/day non-reporting penalties
    Compliance chart comparing Cambridge BEUDO >=100,000 sq ft (2035 net-zero) vs 25,000–99,999 sq ft (2050 net-zero) tracks, May 1 reporting, and $300/day penalties.
    Cambridge BEUDO (Municipal Code Ch. 8.67, amended 2023): active 2025–2026 caps on >=100k sq ft buildings racing toward a 2035 net-zero deadline.

    Compliance Execution Checklist

    StepOwner / TeamAuditable Deliverable
    1. Baseline AuditEngineering / OperationsConfirm non-residential gross sq ft (>=100k vs 25k–99,999) and baseline emissions.
    2. May 1 Filing LockSustainability TeamUpload verified whole-building Eversource energy/water logs prior to May 1.
    3. 2030–2035 CapEx ModelCapital Projects / FinanceModel heat-pump / chiller conversion vs REC + $234/t ACP over 2026–2035 lease cycles.
    Field & Print Package

    Keep This Cambridge, MA Compliance Checklist Handy

    Download the formatted 2-page PDF reference brief or pull the structured Markdown edition for internal compliance documentation.

    Frequently Asked Questions

    Which Cambridge buildings must hit net-zero emissions by 2035 under BEUDO?

    Under Cambridge Municipal Code Ch. 8.67, non-residential buildings >=100,000 sq ft entered emissions limits in 2025–2026 and must achieve net-zero emissions by 2035; buildings 25,000–99,999 sq ft follow a 2030–2050 schedule.

    Are residential apartment buildings subject to Cambridge BEUDO's emissions caps?

    No. Residential buildings with 50 or more units must complete annual May 1 energy and water benchmarking disclosures, but Cambridge's 2023 amendment left purely residential multifamily assets out of the numeric net-zero emissions caps.

    Primary Authorities & Official Resources

    Informational notice: This guide summarizes enacted statutes, regulations, or pending legislative records from the primary authorities linked above as of November 14, 2026. It is not legal, accounting, or licensed engineering advice.
  • Boston BERDO 2.0 Compliance Guide: 2025–2050 Emissions Limits, ACPs & May 15 Filing

    Boston BERDO 2.0 Compliance Guide: 2025–2050 Emissions Limits, ACPs & May 15 Filing

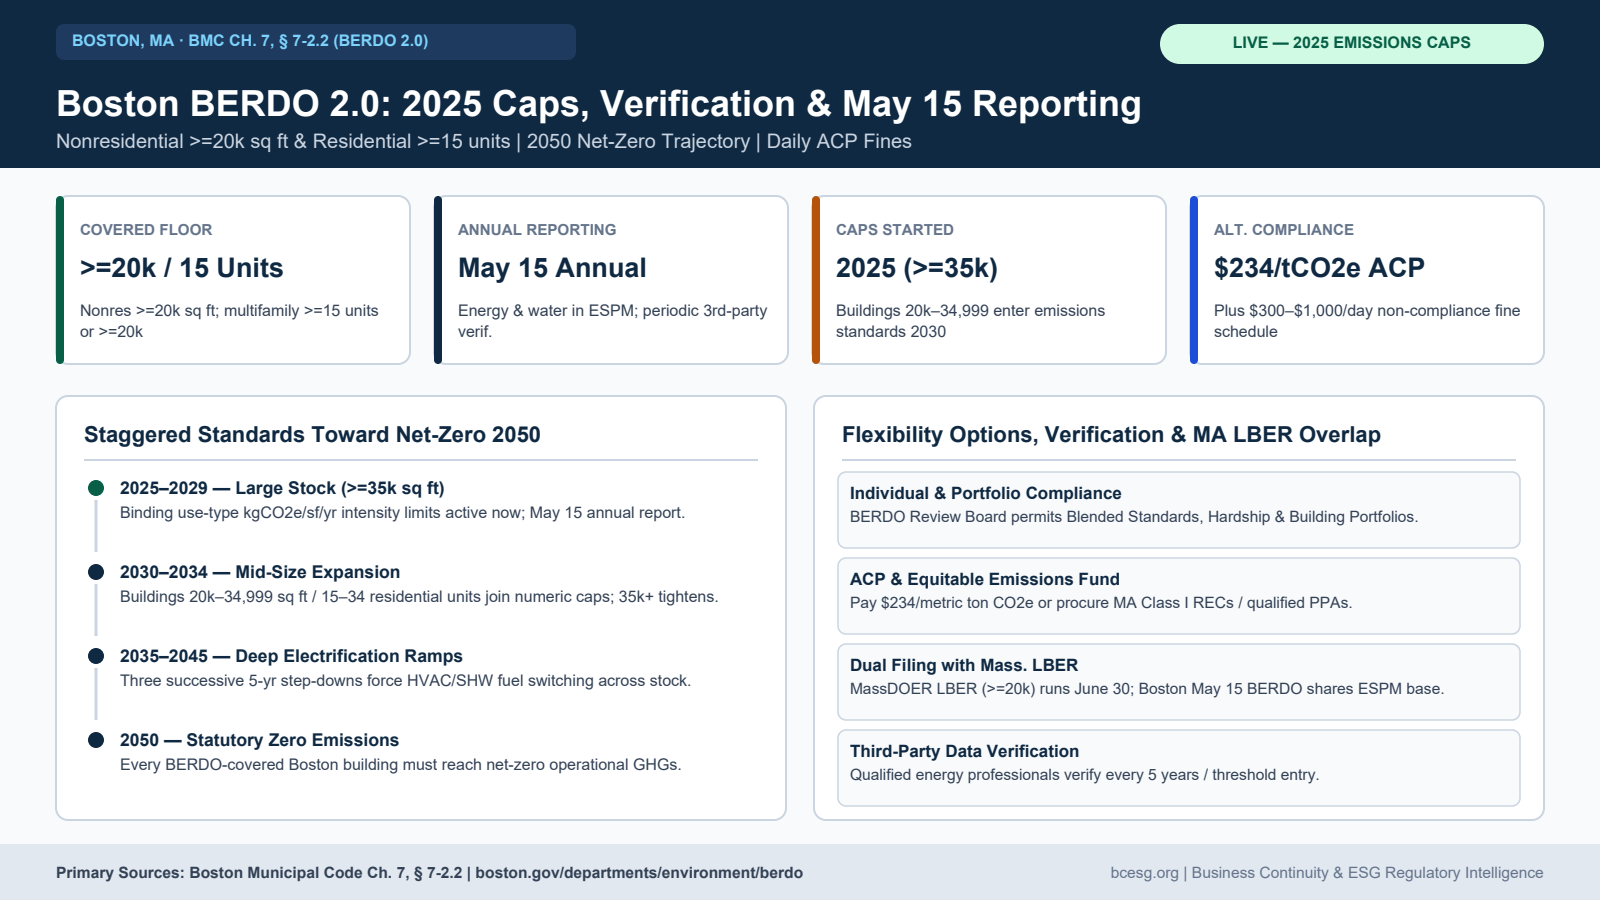
    Short answer: Enacted under Boston Municipal Code Chapter 7, § 7-2.2, Boston’s Building Emissions Reduction and Disclosure Ordinance (BERDO 2.0) is one of the tightest active municipal building decarbonization laws in the United States. Large commercial and multifamily properties (>=35,000 sq ft, or residential properties with >=35 units) entered binding 5-year GHG intensity caps on January 1, 2025, requiring active emissions compliance alongside annual May 15 reporting and periodic third-party data verification.

    Mid-tier buildings (20,000–34,999 sq ft or 15–34 units) already owe annual May 15 energy/water disclosure and step into emissions caps in 2030, progressing uniformly toward net-zero emissions in 2050. Because Massachusetts simultaneously enforces statewide LBER reporting (225 CMR 27.00) — and neighboring Cambridge BEUDO enforces its own net-zero timeline — regional owners should harmonize utility metering across both jurisdictions.

    Statutory Status at a Glance
    • Covered Thresholds: Non-residential >=20,000 sq ft; residential >=15 units or >=20,000 sq ft; or multiple buildings on the same parcel totaling >=20,000 sq ft (or >=15 units).
    • Two-Wave Emissions Caps: >=35,000 sq ft started emissions limits Jan 1, 2025 (with first emissions-year reports covered in 2026); 20,000–34,999 sq ft start emissions caps in 2030.
    • May 15 Annual Deadline & Third-Party Verification: Whole-building energy and water use due annually May 15 via ENERGY STAR Portfolio Manager, paired with third-party qualified verifier attestation every five years (plus first-year baseline verification).
    • Alternative Compliance Payments (ACP) vs. Fines: Excess emissions above occupancy-weighted CO2e limits may be retired at $234 per MTCO2e (deposited into Boston’s Equitable Emissions Investment Fund), whereas failing to comply with emissions standards draws statutory daily fines ($1,000/day for >=35k sf; $300/day for 20k–35k sf).
    Print-First Compliance Brief

    Download the Boston BERDO 2.0 Compliance Reference

    2-page Print-First PDF covering BERDO 2.0 emissions thresholds, third-party verification cadence, $234/tCO2e Alternative Compliance Payments, and MA LBER data alignment.

    Blended Emissions Limits, Class I RECs & Alternative Compliance Payments

    Boston calculates asset limits using 5-year primary-use CO2e intensity factors (kgCO2e/sq ft/yr) blended proportionally across mixed uses inside a parcel (for instance, office vs. multifamily vs. laboratory/healthcare allocations). Where physical fuel switching or heat-pump retrofits lag the 2025–2029 schedule, BERDO 2.0 allows owners to apply eligible Clean Energy purchases — specifically bundled Massachusetts Class I RECs or qualifying Power Purchase Agreements — to electricity emissions.

    Owners facing stubborn fossil-heating loads or phased lease rollovers can apply to the BERDO Review Board for a Blended Emissions Standard (pooling multi-building portfolios), a Hardship Compliance Plan, or an Individual Compliance Schedule modifying interim reduction trajectories — or retire remaining shortfalls via $234/MTCO2e Alternative Compliance Payments.

    • Lab & Healthcare Tiers: High-process facilities receive higher starting EUI/GHG allowances than standard commercial offices, though still stepping to zero by 2050.
    • Mandatory Verification Gate: Unlike simple benchmarking cities, BERDO 2.0 prohibits unverified self-reporting during emissions-cap transition years.
    Building TierAnnual ReportingEmissions Caps StartCompliance Relief & Daily Non-Filing Fines
    Large (>=35k sf or >=35 units)May 15 (PM + 3rd-party verify cycle)Jan 1, 2025 (2025–2029 period)$234/MTCO2e ACP; $1,000/day emissions violation
    Small/Mid (20k–34,999 sf / 15–34 units)May 15 annual energy & waterJan 1, 2030 (2030–2034 period)$234/MTCO2e ACP; $300/day violation (~2030+)
    Multi-Building Parcels>=20k sf combined -> follows >=20k/35k tierMatched to aggregate tierBlended Emissions Standard / Individual Schedule option
    Compliance overview of Boston BERDO 2.0 thresholds (>=20,000 sq ft / >=15 residential units), 2025 vs 2030 cap phases, May 15 verification deadline, and $234/tCO2e Alternative Compliance Payments.
    Boston BERDO 2.0 compliance timeline under Boston Municipal Code Ch. 7, § 7-2.2: benchmarking, third-party verification, 5-year emissions caps, and ACP pricing.

    Coordinating Boston BERDO 2.0 With Massachusetts LBER (225 CMR 27.00)

    Massachusetts’s statewide Large Building Energy Reporting (LBER) program (225 CMR 27.00, >=20,000 sq ft) relies largely on utility-pushed data delivered to DOER on a June 30 cycle, whereas Boston BERDO places strict affirmative legal responsibility directly on building owners every May 15. Confirm whether Eversource and National Grid automated meters align seamlessly across both systems to avoid mismatched square footage or unattributed tenant meters.

    • Utility Data Authorization: Verify whole-building aggregated data consent with Eversource and National Grid ahead of April so tenant-level privacy thresholds do not block May 15 submissions.
    • 2030 Cohort Pre-Audit: Owners of 20,000–34,999 sq ft buildings have four years to use annual BERDO disclosures to cost out 2030 compliance before caps lock in.

    Compliance Execution Checklist

    StepOwner / TeamAuditable Deliverable
    1. Parcel Use & Tier AuditCompliance / LegalConfirm primary occupancy classification and >=35k vs 20k–34,999 sq ft cohort.
    2. 3rd-Party Verifier Sign-OffPE / CEM / Qualified VerifierComplete BERDO data verification checklist ahead of the May 15 filing deadline.
    3. ACP vs REC EconomicsTreasury / SustainabilityCompare MA Class I REC cost against $234/MTCO2e ACP exposure per asset.
    4. MA LBER ReconciliationProperty OperationsCross-check DOER June 30 utility-reported LBER dataset against BERDO May 15 numbers.
    Field & Print Package

    Keep This Boston, MA Compliance Checklist Handy

    Download the formatted 2-page PDF reference brief or pull the structured Markdown edition for internal compliance documentation.

    Frequently Asked Questions

    When did Boston BERDO 2.0 emissions caps actually start?

    Emissions standards took effect January 1, 2025 for buildings >=35,000 sq ft (or residential buildings >=35 units), while smaller covered buildings (20,000–34,999 sq ft) begin active emissions limits in 2030.

    What is Boston BERDO's Alternative Compliance Payment rate?

    Excess CO2e emissions can be settled via Alternative Compliance Payments set at $234 per metric ton of CO2e (MTCO2e), which feed Boston's Equitable Emissions Investment Fund, rather than paying noncompliance fines.

    Does reporting under Boston BERDO exempt a building from Massachusetts statewide LBER?

    Massachusetts LBER (225 CMR 27.00) coordinates municipal reporting for utilities, but building owners must still verify Boston-specific BERDO May 15 disclosures, third-party verifications, and emissions-compliance schedules directly with the City.

    Primary Authorities & Official Resources

    Informational notice: This guide summarizes enacted statutes, regulations, or pending legislative records from the primary authorities linked above as of November 14, 2026. It is not legal, accounting, or licensed engineering advice.
  • NAIC Climate Risk Disclosure Survey: 29-Jurisdiction TCFD Mandate for Insurers (> $100M DWP)

    NAIC Climate Risk Disclosure Survey: 29-Jurisdiction TCFD Mandate for Insurers (> $100M DWP)

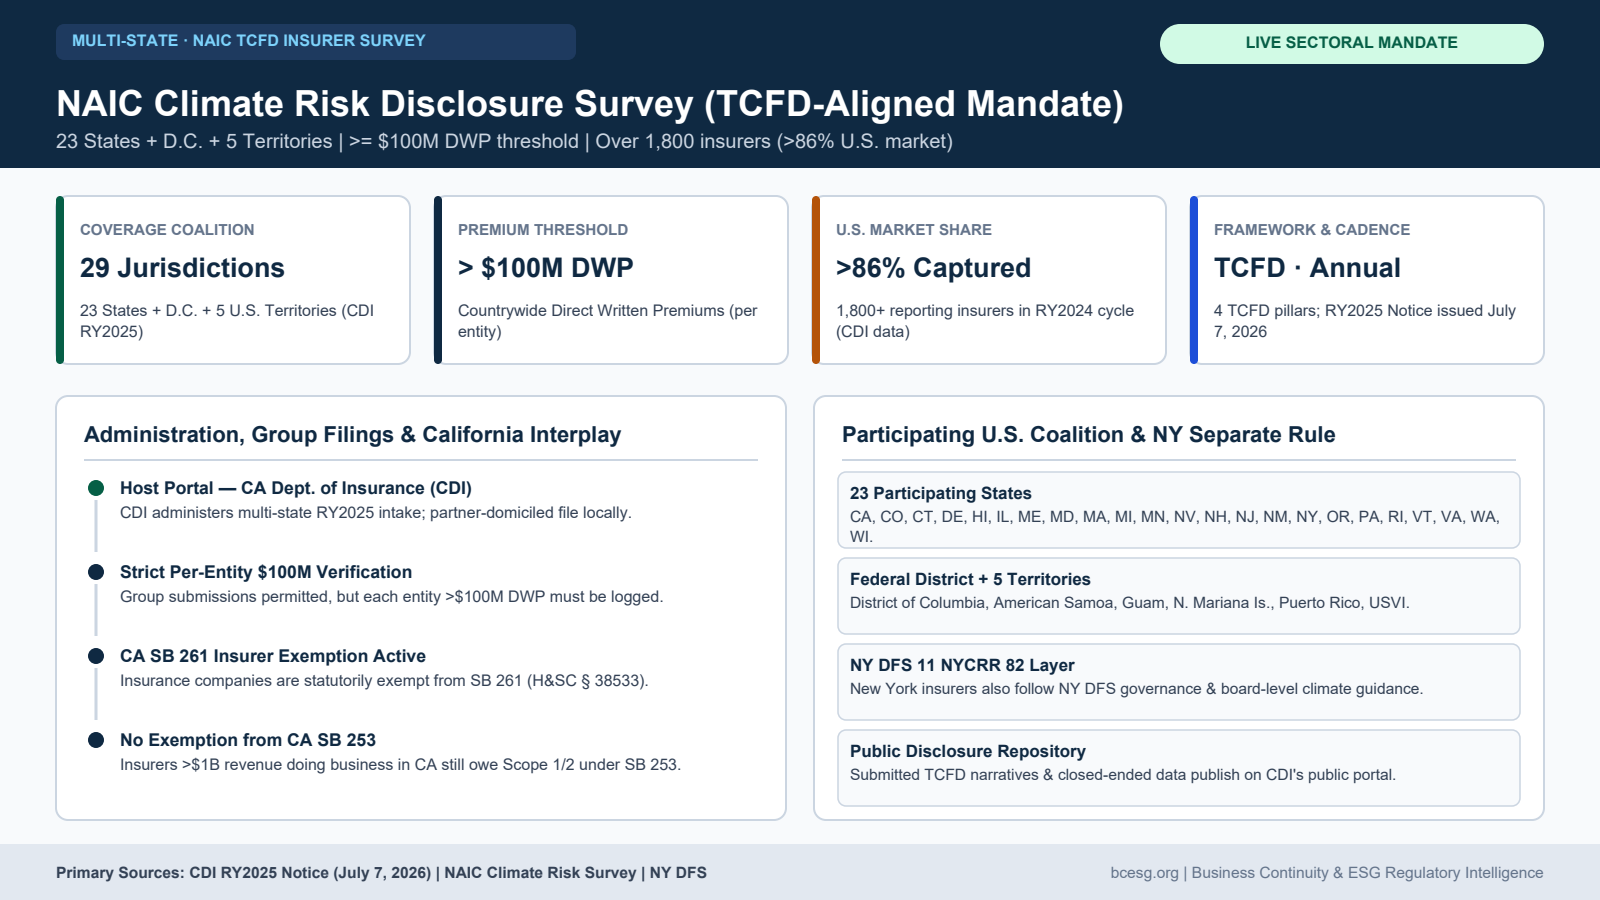
    Short answer: While cross-sector state climate laws remain limited outside California, the U.S. insurance industry already operates under a nationwide mandatory climate-risk reporting regime. Administered jointly by the California Department of Insurance (CDI RY2025 Notice, July 7, 2026) and partner regulators across 23 states, Washington, D.C., and 5 U.S. territories, the Task Force on Climate-Related Financial Disclosures (TCFD)-aligned NAIC Survey captured more than 1,800 companies representing over 86% of the U.S. insurance market.

    Unlike California SB 261—from which insurers are expressly exempt—the NAIC Survey has remained continuously active and un-enjoined. Crucially for compliance teams at multi-line carriers (>$1B revenue), neither the NAIC Survey nor SB 261’s insurer exemption waives California SB 253 GHG Scope 1 and 2 emissions obligations for major carriers doing business in California.

    Statutory Status at a Glance
    • Governing Coalition (29 Jurisdictions): CA (host) + CO, CT, DE, DC, HI, IL, ME, MD, MA, MI, MN, NV, NH, NJ, NM, NY, OR, PA, RI, VT, VA, WA, WI + AS, GU, MP, PR, VI.
    • Mandatory Premium Floor: >$100 million in countrywide Direct Written Premiums (DWP) if licensed in any participating jurisdiction.
    • Required Content Architecture: TCFD 4-pillar narrative (Governance, Strategy, Risk Management, Metrics & Targets) submitted via CDI’s portal or partner commissioner portal, plus voluntary closed-ended NAIC questions.
    • Per-Entity Group Rule: Uniform group policy narratives are allowed across affiliates, but CDI strictly requires an individual submission document per licensed legal entity >$100M DWP.
    • New York & California Intersections: NY carriers also adhere to NY DFS 11 NYCRR 82 climate governance; CA SB 261 exempts insurers, whereas CA SB 253 (>$1B) does NOT.
    Print-First Compliance Brief

    Navigate the Multi-State NAIC TCFD Insurer Survey & SB 261 Carve-Out

    2-page Print-First reference covering the 23-state + DC + 5-territory CDI coalition, per-entity $100M DWP verification, NY 11 NYCRR 82, and CA SB 253/261 boundary.

    Who Must File, Reciprocal Portal Routing, and Per-Entity Group Rules

    Under CDI’s Reporting Year 2025 notice (covering calendar 2025 direct written premiums for the August 2026 call), jurisdiction attaches through state licensure combined with countrywide premium volume >$100 million — not in-state premium volume alone. A mid-sized carrier with $120M nationwide DWP and just $5M of business in Oregon or Pennsylvania is fully in scope.

    To prevent duplicate reporting across the 29 participating regulators, CDI allows carriers required to file in another participating partner state or jurisdiction to submit there rather than filing twice. However, CDI specifically audits multi-entity insurance holding companies: even when group-wide policies match identically across subsidiaries, each legal entity individually exceeding $100M DWP must have a corresponding filing tied to its NAIC company code.

    • Public Record Publication: All participating survey narratives and prior-year responses publish openly on CDI’s Climate Risk Disclosure database, creating public comparability across underwriting, investment portfolio carbon risk, and physical catastrophe pricing.
    • Closed-Ended Supplemental Questions: Alongside the narrative TCFD document, CDI requests responses to aligned closed-ended Y/N SurveyMonkey benchmarking items supporting NAIC industry aggregation.
    Coalition / DimensionScope & Participating JurisdictionsKey Rule / Threshold
    Partner States (23)CA, CO, CT, DE, HI, IL, ME, MD, MA, MI, MN, NV, NH, NJ, NM, NY, OR, PA, RI, VT, VA, WA, WILicensed insurer >$100M countrywide DWP triggers annual filing
    District & Territories (6)District of Columbia + American Samoa, Guam, N. Mariana Is., Puerto Rico, USVIPartner filing reciprocity avoids double submission
    CA SB 261 vs. SB 253CA H&SC §§ 38533 (SB 261) & 38532 (SB 253)EXEMPT from SB 261; NOT exempt from SB 253 if >$1B revenue
    New York DFS Layer11 NYCRR 82 / NY Insurance Circular Letter No. 15Board governance & enterprise risk integration alongside NAIC
    Compliance overview of the NAIC Climate Risk Disclosure Survey across 23 states, D.C., and 5 territories for insurers >$100M direct written premium, showing TCFD pillars and CA SB 261 exemption.
    NAIC Climate Risk Disclosure Survey (CDI RY2025 July 7, 2026 Call): 23 partner states + D.C. + 5 territories, >$100M DWP threshold, and interplay with CA SB 253 / SB 261.

    Why State Insurance Regulation Intersects with Cross-Sector Disclosure Laws

    Even in states listed as ‘None Found’ for cross-sector corporate disclosure statutes—such as New York, New Jersey, and Illinois—the NAIC TCFD Survey binds major carriers every single year.

    At the same time, California Health & Safety Code § 38533 expressly carved insurers out of SB 261 precisely to defer to the NAIC/CDI framework—making the NAIC TCFD submission the de facto national insurer financial-risk standard while SB 261 sits in Ninth Circuit litigation.

    Compliance Execution Checklist

    StepOwner / TeamAuditable Deliverable
    1. Legal-Entity DWP ScreenRegulatory / ActuarialFlag every licensed insurance affiliate exceeding $100M countrywide DWP for the reporting year.
    2. Home-State Reciprocity CheckCompliance LeadConfirm whether domiciliary partner state (e.g., NY, PA, IL) collects directly vs. California CDI portal.
    3. 4-Pillar TCFD NarrativeERM / Chief InvestmentUpdate Governance, Strategy, Risk Mgmt & Metrics/Targets plus closed-ended NAIC Y/N supplement.
    4. Separate CA SB 253 GateESG ReportingIf insurer group entities >$1B rev do business in CA, maintain Scope 1 & 2 GHG filings + Dec 10 fee track.
    Field & Print Package

    Keep This Multi-State Coalition (23 States + D.C. + 5 U.S. Territories) Compliance Checklist Handy

    Download the formatted 2-page PDF reference brief or pull the structured Markdown edition for internal compliance documentation.

    Frequently Asked Questions

    How many states enforce the NAIC TCFD Climate Risk Disclosure Survey?

    As of the July 7, 2026 Reporting Year 2025 Notice, California plus 22 partner states (23 states total), the District of Columbia, and 5 U.S. territories (29 U.S. jurisdictions) enforce the TCFD-aligned NAIC Survey.

    Can an insurance holding company file one group PDF for all subsidiaries?

    Uniform group narratives are allowed when affiliate policies and practices match, but CDI requires an individual filing document submitted for each licensed legal entity exceeding $100 million in countrywide DWP.

    Are insurers exempt from California SB 253 as well as SB 261?

    No. Health & Safety Code § 38533 exempts insurance companies from SB 261 (financial risk reporting), but H&SC § 38532 (SB 253 Scope 1/2/3 GHG emissions for >$1B entities) contains no insurer exemption.

    Primary Authorities & Official Resources

    Informational notice: This guide summarizes enacted statutes, regulations, or pending legislative records from the primary authorities linked above as of November 14, 2026. It is not legal, accounting, or licensed engineering advice.
  • Illinois Climate Corporate Accountability Act (HB 3673): Rule 19(a) Status & Live Compliance Check

    Illinois Climate Corporate Accountability Act (HB 3673): Rule 19(a) Status & Live Compliance Check

    Short answer — PENDING BILL, NOT LIVE LAW: Illinois House Bill HB 3673 (the Climate Corporate Accountability Act, 104th General Assembly) remains stalled in the House Rules Committee after its March 21, 2025 re-referral under Rule 19(a). Because HB 3673 was never enacted, the drafted July 1, 2026 rulemaking deadline and January 1, 2027 reporting date printed in the introduced text carry zero legal effect.

    Many national ESG compliance calendars still flag Illinois’ drafted January 1, 2027 date as active. This watch brief clears that confusion while identifying the two regimes that are enforceable in Illinois today: the NAIC TCFD Climate Risk Disclosure Survey for licensed insurers (>=$100M DWP) and municipal building benchmarking in Chicago (>=50,000 sq ft), alongside any Illinois-headquartered enterprise triggering California SB 253 through California revenue nexus.

    Statutory Status at a Glance
    • Enacted Status: NONE (Re-referred House Rules Rule 19(a) March 21, 2025).
    • Bill Design (>$1B Entities): Modeled on CA SB 253 with Scope 1, Scope 2, and Scope 3 emissions (+180 days post Scope 1/2) plus third-party verification.
    • Distinct Governance Design: Assigns corporate registry oversight to the Illinois Secretary of State (consulting the Attorney General) plus macro-analysis by the University of Illinois or a national laboratory.
    • Unpassed Dates Mooted: Drafted July 1, 2026 rulemaking & Jan 1, 2027 filing text are unpassed bill language — no filing is owed in Springfield.
    • Live Illinois Obligations Today: NAIC TCFD Survey (insurers >=$100M DWP) and Chicago Energy Benchmarking Ordinance (>=50,000 sq ft annual June 1).
    Print-First Compliance Brief

    Verify Illinois HB 3673 Legislative Status & Active Illinois Filings

    2-page Print-First regulatory watch clarifying why HB 3673’s unpassed 2026/2027 dates are not law while separating live Chicago Benchmarking and NAIC duties.

    Why Drafted January 1, 2027 Text in HB 3673 Keeps Tripping Automated Calendars

    When Rep. Kimberly Du Buclet introduced HB 3673 in February 2025, the bill text hard-coded statutory rollout dates — Secretary of State rules by July 1, 2026 and first-year Scope 1/2 disclosures starting January 1, 2027 (with Scope 3 180 days thereafter). Regulatory scrapers frequently index those printed dates without checking subsequent legislative posture.

    In the 104th Illinois General Assembly, however, HB 3673 hit Rule 19(a) re-referral on March 21, 2025 without clearing committee or chamber floor votes. Any future revival in Springfield would require amended statutory deadlines after passage.

    • Distinct Institutional Home: Rather than naming an environmental agency like CARB (CA) or NYSDEC (NY), HB 3673 places the public disclosure platform under the Secretary of State’s corporate division.
    • Research Partner Mandate: Directs an academic institution such as the University of Illinois or a national laboratory to publish aggregate trend analysis from corporate disclosures.
    Measure / MandateApplies ToLegal Status (Nov 14, 2026)Calendar Reality
    IL HB 3673 (104th GA)Entities >$1B doing business in ILPENDING (House Rules Rule 19(a) Mar 2025)Printed Jul 2026 / Jan 2027 dates NOT live law
    NAIC Climate Risk SurveyIL-licensed insurers >=$100M countrywide DWPLIVE Sectoral MandateAnnual TCFD disclosure via CDI / IL DOI portal
    Chicago BenchmarkingCovered Chicago buildings >=50,000 sq ftLIVE Municipal MandateAnnual June 1 Portfolio Manager + 3-yr data verif.
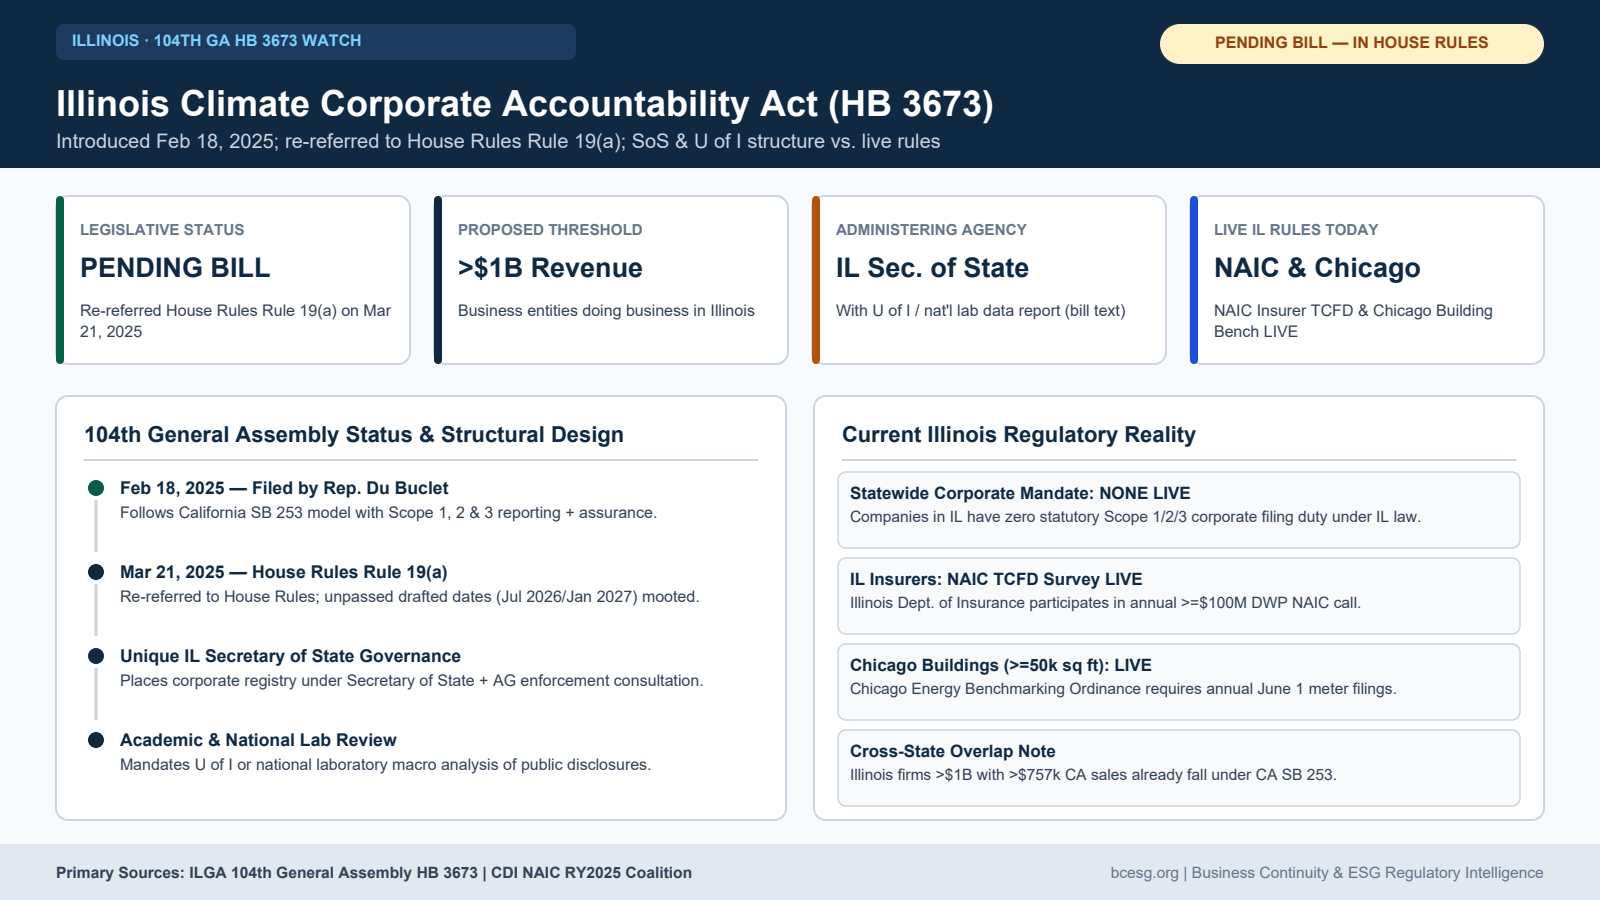
    Legislative status infographic for Illinois 104th General Assembly HB 3673 showing Rule 19(a) referral in House Rules, Secretary of State governance model, and live IL insurance/Chicago rules.
    Illinois 104th General Assembly HB 3673 (Pending Watch — House Rules Rule 19(a)) contrasted against live Illinois NAIC insurer disclosures and Chicago Benchmarking.

    What Companies Operating in Illinois Actually Owe Today

    While Illinois corporations owe zero state-level corporate GHG filings under HB 3673, major Illinois firms frequently sit inside live climate reporting requirements via two adjacent channels: out-of-state nexus (>$757,070 California sales for >$1B entities under California SB 253) or sectoral/city mandates inside Illinois.

    Illinois Department of Insurance partner carriers (>=$100M nationwide DWP) remain bound by the multi-state NAIC TCFD Climate Risk Disclosure Survey, and commercial/multifamily buildings >=50,000 sq ft in Chicago file annual energy disclosures every June 1.

    Compliance Execution Checklist

    StepOwner / TeamAuditable Deliverable
    1. Purge False DeadlineLegal / RiskCorrect any internal tracker showing 'IL Jan 1, 2027 Scope 1/2' — cite 104th GA Rule 19(a) status.
    2. Test CA NexusTax / SustainabilityVerify if IL enterprise >$1B revenue crosses $757k CA sales (triggering live CA SB 253 instead).
    3. Separate City/Insurer DutiesCRE / InsuranceConfirm Chicago >=50k sq ft building benchmarking & IL NAIC >=$100M insurer filings separately.
    4. 105th GA MonitorGov AffairsWatch post-election 2027 Illinois session introductions for successor Climate Corporate bills.
    Field & Print Package

    Keep This Illinois Compliance Checklist Handy

    Download the formatted 2-page PDF reference brief or pull the structured Markdown edition for internal compliance documentation.

    Frequently Asked Questions

    Do companies in Illinois have to report Scope 1 and Scope 2 emissions starting January 1, 2027 under HB 3673?

    No. Although the introduced text of Illinois HB 3673 listed a January 1, 2027 start date, the bill was re-referred to the House Rules Committee under Rule 19(a) on March 21, 2025 and never enacted into law.

    Who would administer Illinois HB 3673 if a future bill passes?

    HB 3673 designated the Illinois Secretary of State (in consultation with the Illinois Attorney General) to adopt rules and contract for a public corporate emissions registry, paired with research analysis by the University of Illinois or a national laboratory.

    Are there any live climate reporting laws in Illinois right now?

    Yes, within specific sectors and cities: Illinois participates in the annual NAIC Climate Risk Disclosure Survey for insurers writing >= $100M countrywide DWP, and the City of Chicago enforces annual June 1 benchmarking for covered buildings >= 50,000 sq ft.

    Primary Authorities & Official Resources

    Informational notice: This guide summarizes enacted statutes, regulations, or pending legislative records from the primary authorities linked above as of November 14, 2026. It is not legal, accounting, or licensed engineering advice.
  • New Jersey Climate Corporate Data Accountability Act (S679): Scope 1/2 Pivot & Pending Watch

    New Jersey Climate Corporate Data Accountability Act (S679): Scope 1/2 Pivot & Pending Watch

    Short answer — PENDING BILL, NOT LIVE LAW: New Jersey Senate Bill S679 (2026–2027 Legislative Session, successor to earlier S4117) remains pending in the Senate Budget & Appropriations Committee and imposes zero current corporate emissions filing obligations.

    Yet S679’s February 12, 2026 committee reprint (679_R1.PDF) marks an important national policy signal: unlike California SB 253 and New York S9072A, New Jersey’s Senate Environment & Energy Committee explicitly removed Scope 3 emissions reporting, narrowing the proposal to Scope 1 and Scope 2 GHG emissions verified by an independent consultant under NJDEP oversight. Meanwhile, New Jersey commercial buildings over 25,000 sq ft do owe active July 1 benchmarking filings under our live New Jersey Clean Energy Act Benchmarking Guide.

    Statutory Status at a Glance
    • Enacted Status: NONE (Pending in Senate Budget & Appropriations). Committee reprint 679_R1 adopted Feb 12, 2026.
    • Proposed Covered Entities: U.S. business entities with >$1 billion in total annual revenue doing business in New Jersey.
    • Proposed Scope (Amended R1): Scope 1 and Scope 2 emissions only (Scope 3 deleted in Feb 2026 amendment) plus independent third-party/consultant verification.
    • Proposed Runway: Drafted to require first reporting 3 years after enactment under New Jersey Department of Environmental Protection (NJDEP) rules.
    • Live NJ Obligations Today: NJ BPU CEA Benchmarking (Class 4A/4C buildings >25k sq ft due July 1) & NAIC TCFD Insurer Survey (>=$100M DWP).
    Print-First Compliance Brief

    Track New Jersey S679's Scope 3 Stripping Amendment & Live NJ Rules

    2-page Print-First watch explaining how Senate Env. & Energy amended S679 to Scope 1 & 2 only (679_R1.PDF) vs. active NJ BPU July 1 benchmarking.

    Why S679 Dropped Scope 3 — And Why That Matters to Corporate Data Teams

    When state climate disclosure bills spread east after California enacted SB 253, Scope 3 value-chain reporting became the single sharpest legislative sticking point for mid-sized industrial, logistics, and life-sciences firms headquartered in New Jersey. By removing Scope 3 in 679_R1, Senate drafters turned S679 into a utility-and-fleet Scope 1 & 2 transparency bill.

    Even if S679 clears Senate Budget & Appropriations and passes both houses in 2027, its 3-year post-enactment lead time plus Scope 1/2 restriction means New Jersey-only companies would rely overwhelmingly on utility electricity and natural gas billing records—the exact meter datasets already standardized by Portfolio Manager under NJ CEA.

    • Compare Against NY & CA: Multinationals with >$1B revenue touching California already fall under full Scope 3 planning for CARB’s 2027 schedule, regardless of whether New Jersey’s bill omits Scope 3.
    • Audit Verification Model: S679 maintains an independent verification requirement over Scope 1 & 2 data prior to public disclosure by NJDEP.
    InstrumentUniverseScope / RequirementLive Status (Nov 14, 2026)
    NJ S679 (679_R1 Reprint)Entities >$1B revenue doing business in NJScope 1 & 2 ONLY (Scope 3 removed) + verification; 3 yrs post-enactmentPENDING in Sen. Budget & Appropriations
    NJ Clean Energy Act (N.J.S.A. 48:3-87.10)Commercial Class 4A/4C buildings >25,000 sq ftAnnual ENERGY STAR Portfolio Manager energy & water (July 1)LIVE & Enforced by NJ BPU
    NAIC Climate Risk SurveyInsurers >=$100M nationwide DWP licensed in NJAnnual 4-pillar TCFD climate financial risk narrativeLIVE Sectoral Mandate
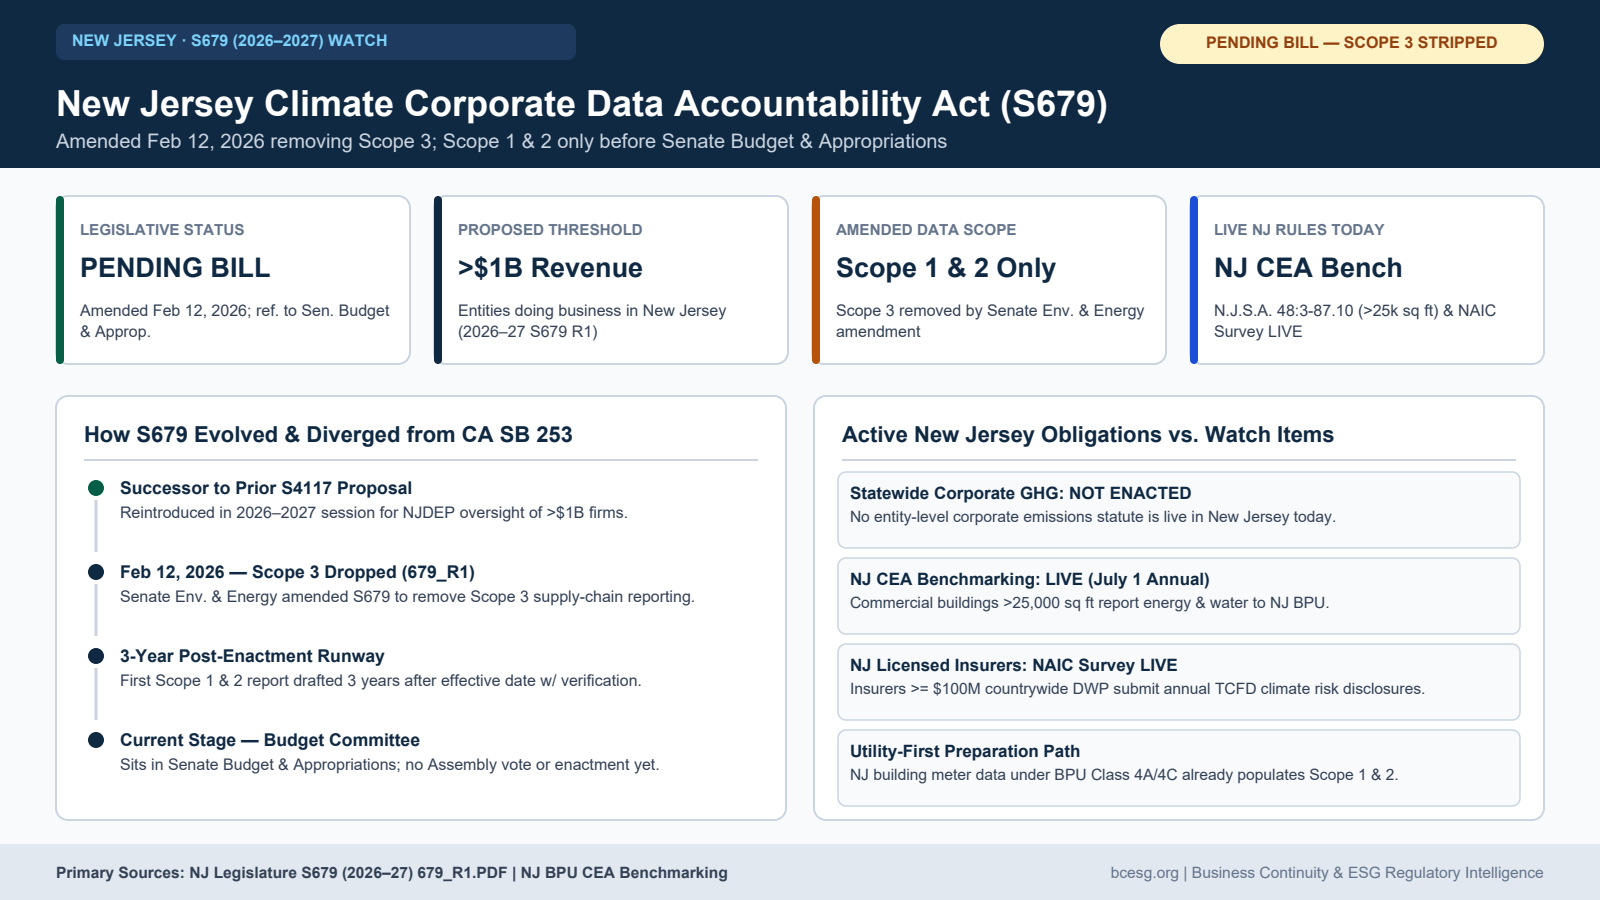
    Visual summary of New Jersey pending S679 Climate Corporate Data Accountability Act showing Feb 12 2026 Senate amendment removing Scope 3 and active NJ CEA building benchmarking.
    New Jersey S679 (2026–2027 Session, 679_R1.PDF) Pending Status: amended to Scope 1 & 2 only in Senate Budget & Appropriations vs. live NJ CEA benchmarking.

    Active New Jersey Compliance Today: CEA Benchmarking & NAIC Insurers

    Corporate real-estate and facility directors often mistake New Jersey’s July 1 benchmarking filings for S679 corporate reporting. Under N.J.S.A. 48:3-87.10, New Jersey Board of Public Utilities (NJBPU) enforces annual July 1 ENERGY STAR Portfolio Manager benchmarking across commercial Class 4A/4C buildings exceeding 25,000 sq ft.

    Similarly, New Jersey participates in the 29-jurisdiction NAIC Climate Risk Disclosure Survey, binding NJ-licensed insurers with >=$100M in countrywide direct written premiums.

    Compliance Execution Checklist

    StepOwner / TeamAuditable Deliverable
    1. Mark S679 PendingCompliance / LegalLog S679 (679_R1) as Watch-Only; exclude from live statutory penalty registers.
    2. Leverage NJ BPU MetersFacilities / EnergyUse active July 1 NJ CEA Portfolio Manager utility exports as clean building blocks for Scope 1 & 2.
    3. Separate CA NexusSustainabilityConfirm whether >$1B corporate parent already owes Scope 1/2/3 via CA SB 253.
    4. Budget Committee TrackGov AffairsTrack Senate Budget & Appropriations scheduling and any Assembly companion amendments.
    Field & Print Package

    Keep This New Jersey Compliance Checklist Handy

    Download the formatted 2-page PDF reference brief or pull the structured Markdown edition for internal compliance documentation.

    Frequently Asked Questions

    Did New Jersey pass its Climate Corporate Data Accountability Act (S679)?

    No. S679 (2026–2027 Session) was amended in the Senate Environment & Energy Committee on February 12, 2026 and referred to the Senate Budget & Appropriations Committee. No cross-sector corporate GHG disclosure law is enacted in New Jersey.

    Does New Jersey S679 still require Scope 3 supply-chain emissions reporting?

    No. Under the February 12, 2026 committee reprint (679_R1.PDF), Scope 3 was removed, narrowing the pending bill to Scope 1 and Scope 2 emissions with independent verification.

    What climate reporting IS mandatory in New Jersey right now?

    Commercial buildings over 25,000 sq ft (Tax Class 4A/4C) must file annual July 1 benchmarking under the NJ Clean Energy Act, and insurers >= $100M countrywide DWP file the annual NAIC TCFD Climate Risk Disclosure Survey.

    Primary Authorities & Official Resources

    Informational notice: This guide summarizes enacted statutes, regulations, or pending legislative records from the primary authorities linked above as of November 14, 2026. It is not legal, accounting, or licensed engineering advice.
  • New York Climate Corporate Data Accountability Act (S9072A / A4282A): Pending Status & Readiness

    New York Climate Corporate Data Accountability Act (S9072A / A4282A): Pending Status & Readiness

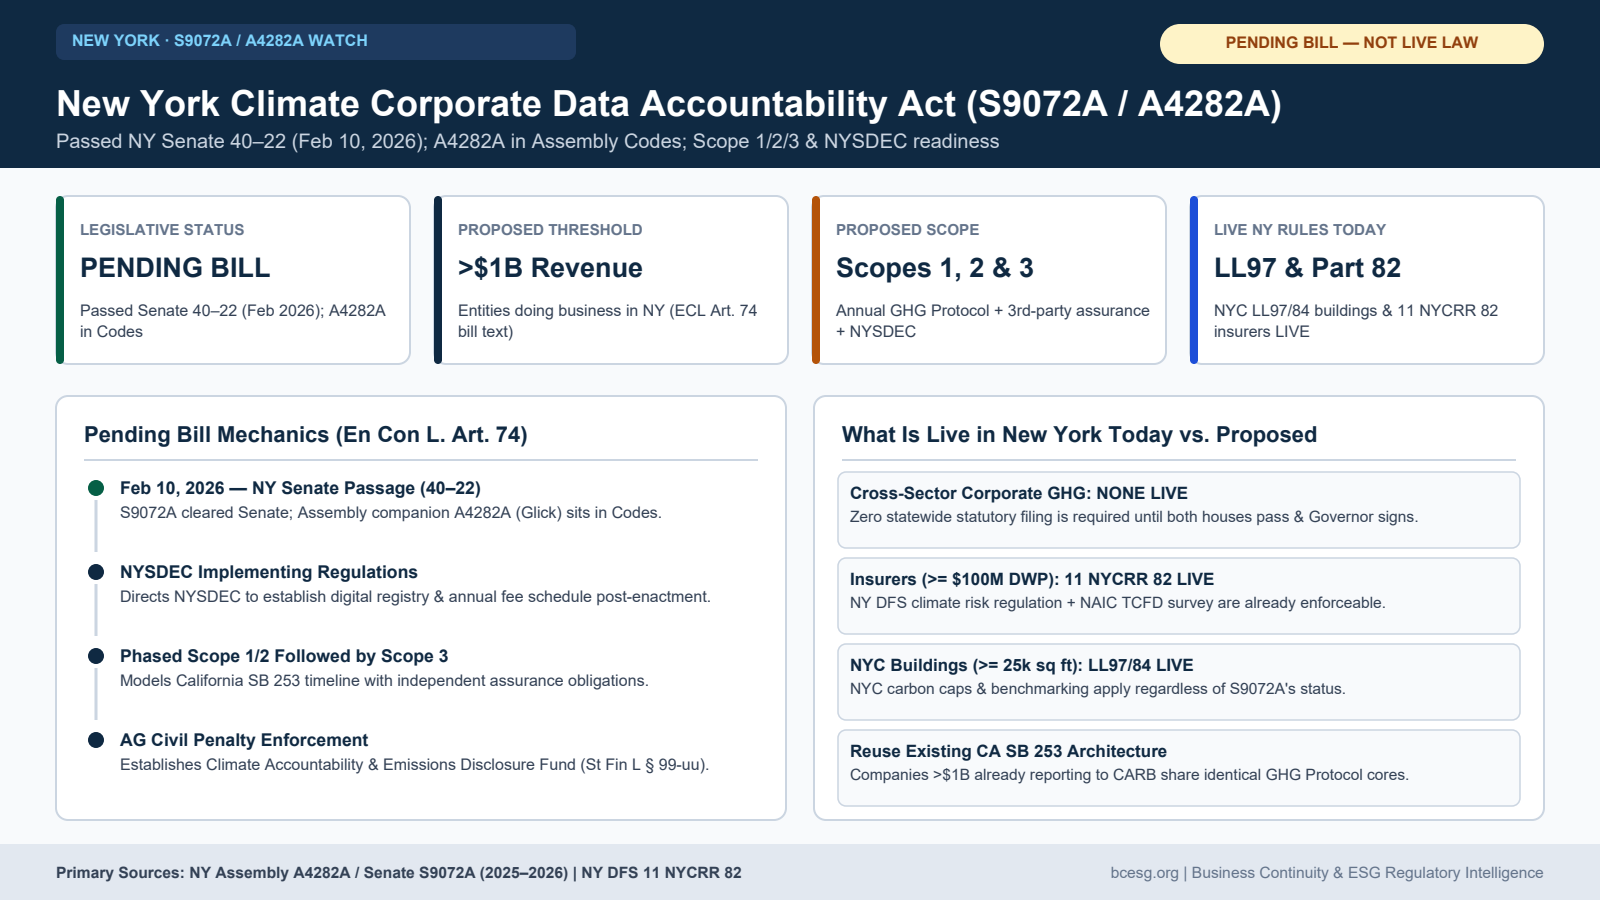
    Short answer — PENDING BILL, NOT LIVE LAW: New York does not have a live statewide cross-sector corporate greenhouse gas disclosure law in effect. Senate Bill S9072A cleared the New York State Senate by a 40–22 margin on February 10, 2026, but identical Assembly companion A4282A remains pending in the Assembly Codes Committee without final passage or gubernatorial signature.

    For general counsel and sustainability teams, the practical governance distinction in New York is sharp: zero filings are due today under ECL Article 74—yet two adjacent New York regimes are already live and actively enforced: 11 NYCRR 82 (NY Department of Financial Services climate-risk governance for insurers alongside the NAIC TCFD Survey) and New York City’s Local Law 97 / Local Law 84 building caps.

    Statutory Status at a Glance
    • Enacted Status: NONE (Pending Legislation). S9072A passed Senate (40–22, Feb 10, 2026); A4282A remains in Assembly Codes.
    • Proposed Covered Entities: U.S. partnerships, corporations, LLCs, or business entities doing business in New York with total annual revenues exceeding $1 billion.
    • Proposed Administering Agency: New York State Department of Environmental Conservation (NYSDEC), backed by Attorney General civil penalty enforcement into State Finance Law § 99-uu.
    • Proposed Emissions Scope: Annual Scope 1, Scope 2, and Scope 3 GHG emissions per GHG Protocol with independent third-party assurance phased across reporting years.
    • What Is Live Today in NY: NYC Local Law 97 & LL84 (buildings >=25k sq ft), NY State benchmarking workflows, and NY DFS climate guidance / 11 NYCRR 82 for insurers.
    Print-First Compliance Brief

    Track New York S9072A / A4282A Without Confusing Pending Bills for Live Law

    2-page Print-First regulatory watch separating pending >$1B cross-sector S9072A/A4282A proposals from live NY insurer (11 NYCRR 82) and NYC LL97/84 mandates.

    Inside S9072A / A4282A: How the Proposed ECL Article 74 Architecture Works

    Drafted as a direct east-coast counterpart to California SB 253, S9072A / A4282A proposes adding Article 74 (§§ 74-0101 and 74-0102) to the New York Environmental Conservation Law alongside a dedicated Climate Accountability and Emissions Disclosure Fund (State Finance Law § 99-uu).

    Unlike New Jersey’s amended S679—where Senate Environment & Energy stripped Scope 3 in February 2026—New York’s Senate-passed text retains full Scope 1, Scope 2, and Scope 3 disclosures plus third-party assurance phased after NYSDEC rulemaking.

    • Consolidated Reporting Alignment: Because both CA SB 253 and NY S9072A rely on the Greenhouse Gas Protocol Corporate Accounting and Reporting Standard and Corporate Value Chain (Scope 3) Standard, multi-state firms >$1B already assembling CARB inventories can reuse identical entity boundaries.
    • Rulemaking Lead Time Guarantee: Even if resurrected in post-election legislative sessions, statutory reporting duties do not begin immediately upon signature; NYSDEC must first adopt implementing regulations, digital registry contracts, and fee schedules.
    Framework / BillTarget UniverseCurrent Status (Nov 14, 2026)Immediate Action
    S9072A / A4282A (ECL Art. 74)U.S. entities >$1B doing business in NYPENDING (Passed Sen. 40–22; A4282A in Codes)Monitor only; map reuse of CA SB 253 Scope 1/2/3 controls
    NY DFS 11 NYCRR 82 & NAICLicensed insurers (>=$100M DWP / NY domestic)LIVE Sectoral MandateMaintain board climate governance & annual TCFD response
    NYC LL97 & LL84Covered NYC buildings >=25,000 sq ftLIVE Municipal Carbon CapFile annual May 1 LL84 & LL97 compliance / mitigation reports
    Legislative status diagram for New York S9072A / A4282A Climate Corporate Data Accountability Act showing Feb 10 2026 Senate passage (40-22), Assembly Codes stall, >$1B scope, and live NY LL97 / Part 82 rules.
    New York S9072A / A4282A (Pending Watch — not live cross-sector law) contrasted with live NY DFS 11 NYCRR 82 insurer rules and NYC Local Law 97/84.

    Separation Check: Live New York Mandates Already Requiring Filings

    Compliance calendars in New York routinely conflate S9072A news headlines with enforceable statutes that already carry financial penalties. Teams operating buildings or insurance carriers in the state must isolate three separate compliance streams.

    First, real-estate owners >=25,000 sq ft inside New York City remain governed by Local Law 84 benchmarking and Local Law 97 carbon-intensity caps regardless of Albany action. Second, NY domestic and licensed insurers >=$100M DWP answer annual TCFD climate risk surveys alongside NY DFS expectations under 11 NYCRR 82.

    • Private Non-Insurer Corporations Outside NYC Real Estate: Zero statutory statewide Scope 1/2/3 filing obligation today unless they also trigger California SB 253 via >$757k California sales.
    • Albany Trigger Watch: Monitor Assembly Codes and 2027 committee reintroduction schedules; post-2026 legislative sessions determine whether S9072A is carried over or refiled with Assembly revenue/assurance revisions.

    Compliance Execution Checklist

    StepOwner / TeamAuditable Deliverable
    1. Calendar HygieneLegal / ComplianceTag S9072A/A4282A strictly as Pending Watch — remove any implied 2026/2027 statutory fine assumptions.
    2. CA SB 253 MappingSustainability LeadDocument whether NY entity already falls under CA SB 253 (> $1B global rev + CA nexus).
    3. NY DFS / LL97 CheckRisk / Real EstateVerify live insurer obligations (11 NYCRR 82) and NYC property LL97/84 filings independently.
    4. Session Carryover WatchGov AffairsTrack Assembly Codes & 2027 committee calendar for amended text or Scope 3 adjustments.
    Field & Print Package

    Keep This New York State Compliance Checklist Handy

    Download the formatted 2-page PDF reference brief or pull the structured Markdown edition for internal compliance documentation.

    Frequently Asked Questions

    Do companies have to file corporate GHG emissions reports with New York State in 2026 or early 2027?

    No. New York's Climate Corporate Data Accountability Act (S9072A / A4282A) passed the Senate in February 2026 but remained pending in Assembly Codes as of November 14, 2026. No cross-sector statewide corporate GHG reporting statute is enacted or in force.

    What does New York S9072A / A4282A require if enacted?

    The bill as passed by the Senate covers entities with annual revenues over $1 billion doing business in New York, phasing in annual Scope 1, Scope 2, and Scope 3 emissions reports under the GHG Protocol with third-party assurance administered by NYSDEC.

    Which climate disclosure rules ARE live in New York today?

    Insurers face live obligations under NY DFS 11 NYCRR 82 and the NAIC TCFD Survey (>= $100M DWP), while covered New York City buildings >= 25,000 sq ft face live annual compliance under Local Law 84 benchmarking and Local Law 97 carbon limits.

    Primary Authorities & Official Resources

    Informational notice: This guide summarizes enacted statutes, regulations, or pending legislative records from the primary authorities linked above as of November 14, 2026. It is not legal, accounting, or licensed engineering advice.
  • Minnesota Building Benchmarking (§ 216C.331): Phase 2 Active & Twin Cities Consolidation

    Minnesota Building Benchmarking (§ 216C.331): Phase 2 Active & Twin Cities Consolidation

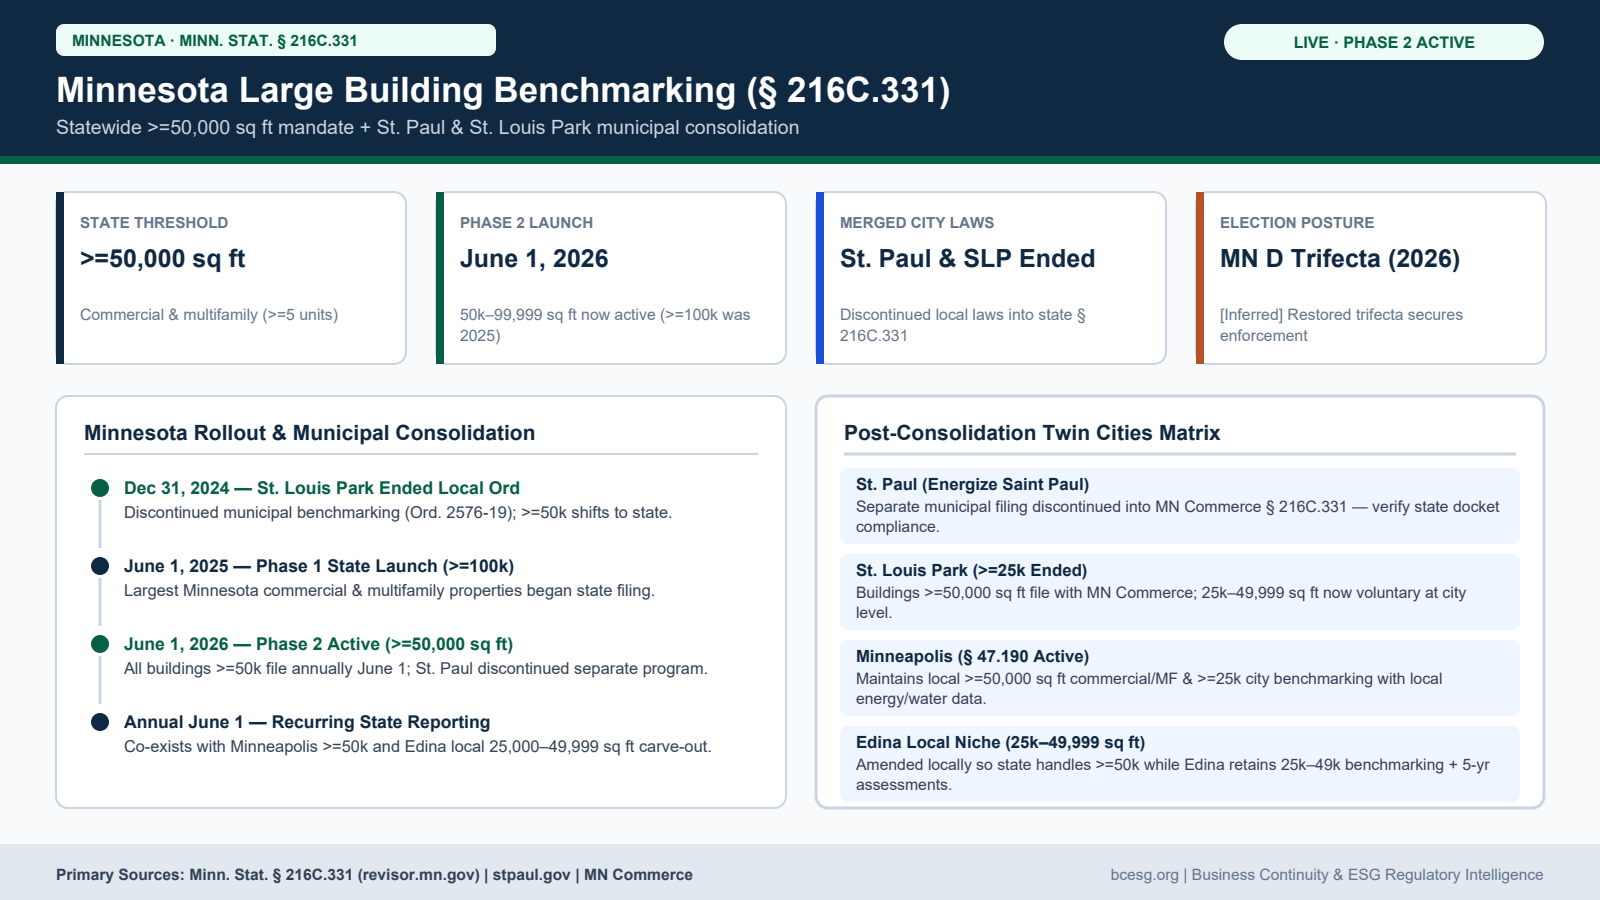
    Short answer: Minnesota’s statewide Large Building Energy Benchmarking Program (Minn. Stat. § 216C.331) reached full Phase 2 coverage on June 1, 2026, requiring commercial and multifamily buildings (5+ units) of ≥50,000 gross sq ft to submit annual energy data to the Minnesota Department of Commerce by June 1.

    Equally important for Twin Cities property managers is what happened locally: both St. Paul (Energize Saint Paul) and St. Louis Park discontinued their standalone municipal benchmarking mandates into state law, while Edina narrowed locally to 25,000–49,999 sq ft and Minneapolis continues co-enforcing ≥50,000 sq ft locally.

    Statutory Status at a Glance
    • Governing Authority: Minn. Stat. § 216C.331.
    • Administering Agency: Minnesota Department of Commerce — Large Building Energy Benchmarking Program.
    • Covered Threshold & Schedule: ≥100,000 sq ft launched June 1, 2025 (Phase 1); ≥50,000 sq ft active June 1, 2026 (Phase 2); recurring June 1 annually.
    • Municipal Consolidations: St. Paul and St. Louis Park retired separate municipal programs into § 216C.331; Edina shifted ≥50k buildings to state law and kept 25k–49,999 sq ft locally.
    • Post-2026 Policy Trajectory (Inferred): Minnesota’s November 2026 House shift restoring a unified DFL trifecta increases legislative durability for state benchmarking enforcement and future building-decarbonization bills.
    Print-First Compliance Brief

    Navigate Minnesota § 216C.331 After St. Paul & St. Louis Park Consolidated Into State Law

    2-page quick card covering Minnesota’s June 1 Phase 2 (>=50k sq ft) schedule, Twin Cities ordinance retirements, Edina’s 25k-49k carve-out, and MN 2026 election posture.

    Statewide Phased Rollout: From 100k (2025) to >=50k Active Now (2026+)

    Minn. Stat. § 216C.331 covers private commercial buildings and multifamily residential buildings with five or more dwelling units across Minnesota’s core metropolitan counties and covered jurisdictions as specified in statute. Phase 1 swept in properties ≥100,000 sq ft for the June 1, 2025 cycle; Phase 2 pulled every qualifying building 50,000 to 99,999 sq ft into active annual June 1 compliance in 2026.

    Because Minnesota winters create high space-heating fuel intensity, accurate Portfolio Manager natural gas and district steam normalization—backed by automated Xcel Energy and CenterPoint utility data feeds—is essential before public score release.

    Jurisdiction / LayerCurrent Floor & LawActive 2026–2027 Status
    Minnesota State (§ 216C.331)Commercial & MF (5+ units) >=50,000 sq ftACTIVE NOW — June 1 annual to MN Commerce
    St. Paul, MNFormer >=50k Energize Saint PaulDISCONTINUED locally — file via MN § 216C.331
    St. Louis Park, MNFormer >=25k Ord. 2576-19DISCONTINUED Dec 31, 2024 — >=50k files with state
    Edina, MNAmended Efficient Buildings Ord.Active locally ONLY for 25,000–49,999 sq ft (June 1)
    Minneapolis, MNCode Ch. 47 § 47.190 (>=50k)Active municipal energy + water filing due June 1
    Minnesota § 216C.331 building benchmarking infographic showing Phase 1 >=100k (2025), Phase 2 >=50k (2026), St. Paul and St. Louis Park local discontinuation, and Minneapolis/Edina overlap.
    Minnesota § 216C.331 Phase 1–2 thresholds and Twin Cities post-consolidation ordinance landscape (St. Paul, St. Louis Park, Minneapolis, Edina).

    Twin Cities Consolidation Matrix: St. Paul, St. Louis Park, Edina & Minneapolis

    Compliance consultants using outdated 2023–2024 checklists routinely tell Twin Cities owners to submit four separate city reports. That is no longer accurate after Minnesota implemented § 216C.331:

    Read alongside our California AB 802 and Massachusetts LBER guides, Minnesota illustrates how state statutes increasingly absorb local ordinances above 50,000 sq ft—leaving smaller municipal niches like Edina’s 25k–49k tier active locally.

    • St. Paul (Energize Saint Paul — Discontinued Locally): Replaced by statewide MN Commerce § 216C.331 reporting for ≥50,000 sq ft assets.
    • St. Louis Park (Discontinued End of 2024): Former ≥25,000 sq ft municipal mandate ended December 31, 2024; properties ≥50,000 sq ft file with MN Commerce while 25k–49k moved to voluntary sustainability programs.
    • Edina (Amended Local Niche 25,000–49,999 sq ft): Defers ≥50,000 sq ft assets to state § 216C.331 while enforcing local June 1 energy/water benchmarking and 5-year energy assessments on 25,000–49,999 sq ft properties.
    • Minneapolis (Ch. 47 § 47.190 Active): Continues local energy and water benchmarking due June 1 alongside state § 216C.331 (≥50,000 sq ft private; ≥25k city).

    Compliance Execution Checklist

    StepOwner / TeamAuditable Deliverable
    1. Jurisdiction MapAsset MgmtTag each MN asset >=25k sq ft as State-Only (incl. St. Paul / >=50k SLP), Dual Mpls+State, or Edina 25k-49k.
    2. Utility ConnectProperty OpsConnect Xcel Energy / CenterPoint automated whole-building Portfolio Manager feeds before April.
    3. File by June 1Compliance LeadSubmit state § 216C.331 (and Minneapolis/Edina where applicable) by June 1 annually.
    4. 2027 Policy WatchESG LeadTrack restored MN trifecta committee activity for potential corporate disclosure or BPS bills.
    Field & Print Package

    Keep This Minnesota Compliance Checklist Handy

    Download the formatted 2-page PDF reference brief or pull the structured Markdown edition for internal compliance documentation.

    Frequently Asked Questions

    Do buildings in St. Paul or St. Louis Park still file separate city benchmarking reports?

    No. Both St. Paul (Energize Saint Paul) and St. Louis Park (effective end of 2024) discontinued their separate municipal benchmarking mandates, consolidating >=50,000 sq ft properties into Minnesota's statewide § 216C.331 program.

    What changed in Edina after Minnesota passed § 216C.331?

    Edina amended its Efficient Buildings Ordinance so buildings >=50,000 sq ft report to the state while Edina retains local June 1 energy and water benchmarking plus 5-year energy assessments specifically for 25,000–49,999 sq ft buildings.

    Does Minnesota § 216C.331 cover residential apartments?

    Yes. Multifamily residential buildings with five or more units and >=50,000 gross sq ft are covered alongside commercial properties.

    Primary Authorities & Official Resources

    Informational notice: This guide summarizes enacted statutes, regulations, or pending legislative records from the primary authorities linked above as of November 14, 2026. It is not legal, accounting, or licensed engineering advice.
  • New Jersey Clean Energy Act Benchmarking (N.J.S.A. 48:3-87.10): Class 4A/4C & July 1 Guide

    New Jersey Clean Energy Act Benchmarking (N.J.S.A. 48:3-87.10): Class 4A/4C & July 1 Guide

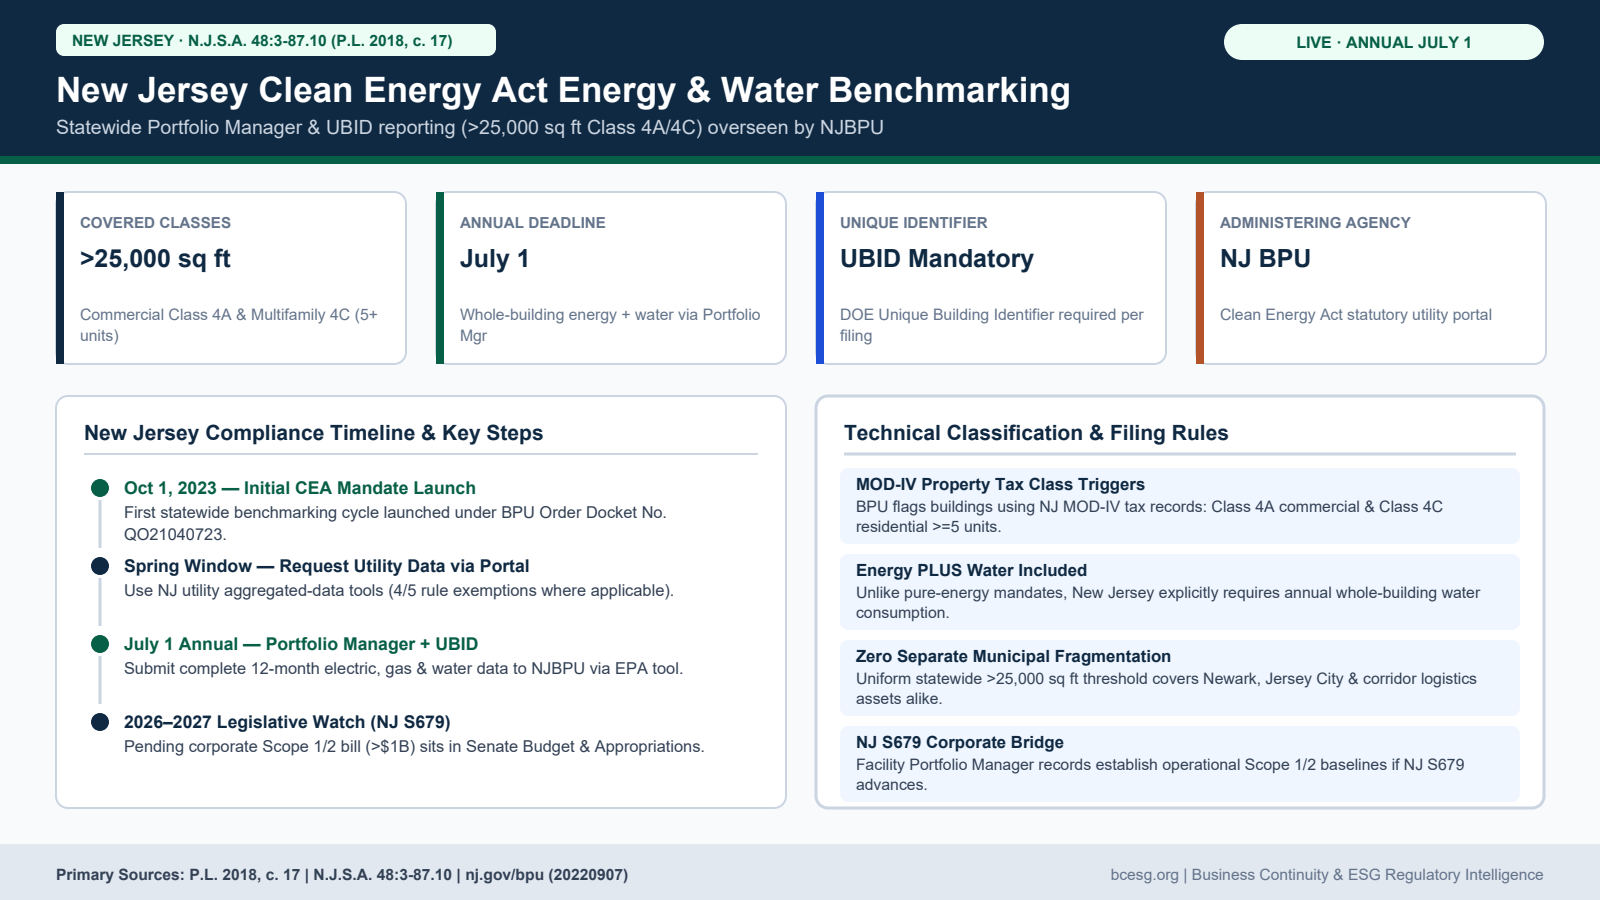
    Short answer: Under New Jersey’s Clean Energy Act (P.L. 2018, c. 17; N.J.S.A. 48:3-87.10), owners of commercial (Class 4A) and multifamily residential (Class 4C, 5+ units) buildings exceeding 25,000 gross sq ft must benchmark and submit whole-building energy and water data annually by July 1 using ENERGY STAR Portfolio Manager and a DOE Unique Building Identifier (UBID).

    For corporate logistics, pharma, and multifamily portfolios operating across the Northeast corridor, New Jersey avoids the municipal patchwork seen in Massachusetts and New York City—one statewide NJBPU standard governs every municipality from Newark and Jersey City down to Camden.

    Statutory Status at a Glance
    • Governing Authority: Clean Energy Act of 2018 (P.L. 2018, c. 17; N.J.S.A. 48:3-87.10) & NJBPU Benchmarking Order.
    • Administering Agency: New Jersey Board of Public Utilities (NJBPU).
    • Covered Tax Classes: MOD-IV Class 4A commercial (office, industrial/warehouse, retail) & Class 4C residential (5+ units) >25,000 gross sq ft.
    • Annual Recurring Deadline: July 1 (following initial October 1, 2023 cycle launch).
    • Distinct Requirements: Mandatory whole-building water data alongside energy, plus U.S. DOE UBID assignment inside Portfolio Manager.
    Print-First Compliance Brief

    Standardize New Jersey >25,000 sq ft Class 4A & 4C Benchmarking Before July 1

    2-page quick card covering NJBPU MOD-IV tax class screening, water reporting, Unique Building Identifier (UBID) rules, and NJ S679 linkage.

    MOD-IV Property Class Screening & the Water + UBID Mandate

    NJBPU determines building applicability using municipal tax-assessor MOD-IV records rather than owner self-reporting. Warehouse and industrial complexes in Middlesex, Hudson, Bergen, and Burlington counties taxed under Class 4A—and apartment complexes of 5+ units taxed under Class 4C—enter scope whenever gross floor area exceeds 25,000 sq ft.

    Two compliance details routinely trigger NJBPU rejection notices: omitting water utility meters (New Jersey explicitly pairs water benchmarking with energy under N.J.S.A. 48:3-87.10) and leaving the Unique Building Identifier (UBID) custom ID field blank inside Portfolio Manager.

    • Regulated Utility Data Tools: NJ electric and gas utilities provide automated or portal-based aggregated whole-building usage under BPU privacy/aggregation guidelines (4/5 rule thresholds).
    • Uniform Statewide Scope: New Jersey imposes no separate city-level EUI or GHG performance cap ordinances today, though NJBPU’s public benchmarking scores increasingly surface in municipal green-building and lender underwriting reviews.
    Program DimensionNew Jersey CEA RuleCompliance Requirement
    Statutory ThresholdN.J.S.A. 48:3-87.10MOD-IV Class 4A commercial & Class 4C (5+ units) >25,000 sq ft
    Covered UtilitiesNJBPU Order / Portfolio MgrWhole-building electric, gas/thermal fuel AND water consumption
    Property IdentifierCustom Field in ESPMMandatory DOE Unique Building Identifier (UBID) + NJ tax block/lot
    Annual Filing SchedulePost-2023 Recurring CadenceJuly 1 annually via NJBPU ENERGY STAR Portfolio Manager link
    New Jersey Clean Energy Act Energy and Water Benchmarking Program summary showing >25,000 sq ft Class 4A/4C threshold, annual July 1 deadline, UBID requirement, and NJ S679 legislative bridge.
    New Jersey Clean Energy Act Energy & Water Benchmarking Program rules under N.J.S.A. 48:3-87.10 and NJBPU oversight.

    Strategic Link: Portfolio Manager Baselines & Pending NJ S679 Disclosure

    While New Jersey’s benchmarking law carries no statewide EUI penalty cap today, facility energy data feeds directly into corporate GHG reporting—particularly if New Jersey advances NJ S679 (pending corporate climate disclosure legislation amended in 2026 to cover Scope 1 and Scope 2 emissions for firms >$1B revenue).

    Compare New Jersey’s July 1 schedule against Maryland’s June 1 verified BEPS deadline and NYC’s May 1 LL84 deadline to keep Mid-Atlantic property managers aligned on one quarterly utility audit cycle.

    Compliance Execution Checklist

    StepOwner / TeamAuditable Deliverable
    1. MOD-IV LookupTax / Asset LeadVerify parcel Class (4A/4C) and >25,000 sq ft status on municipal MOD-IV tax records & BPU list.
    2. UBID AssignmentEnergy AnalystGenerate/confirm building UBID and map NJ municipal Block/Lot numbers inside Portfolio Manager.
    3. Utility + Water SyncProperty OpsPull 12-month aggregated electric/gas data plus municipal water bills ahead of June 1.
    4. Submit July 1Compliance LeadSubmit via NJBPU reporting link and retain confirmation receipt for ESG/NJ S679 audits.
    Field & Print Package

    Keep This New Jersey Compliance Checklist Handy

    Download the formatted 2-page PDF reference brief or pull the structured Markdown edition for internal compliance documentation.

    Frequently Asked Questions

    Are industrial warehouses subject to New Jersey's benchmarking law?

    Yes. Industrial, warehouse, logistics, retail, and office buildings taxed under New Jersey MOD-IV Class 4A that exceed 25,000 gross sq ft are covered by NJBPU benchmarking.

    Does New Jersey require water consumption reporting as well as electricity and gas?

    Yes. N.J.S.A. 48:3-87.10 requires annual whole-building water benchmarking in addition to electric and natural gas/heating energy usage.

    What is a UBID and why does NJBPU require it?

    A Unique Building Identifier (UBID) is a standardized geographic footprint code maintained by the U.S. DOE so NJBPU can match Portfolio Manager submissions cleanly against municipal MOD-IV parcel records.

    Primary Authorities & Official Resources

    Informational notice: This guide summarizes enacted statutes, regulations, or pending legislative records from the primary authorities linked above as of November 14, 2026. It is not legal, accounting, or licensed engineering advice.
  • Massachusetts Large Building Energy Reporting (LBER / 225 CMR 27.00): Thresholds & June 30 Rules

    Massachusetts Large Building Energy Reporting (LBER / 225 CMR 27.00): Thresholds & June 30 Rules

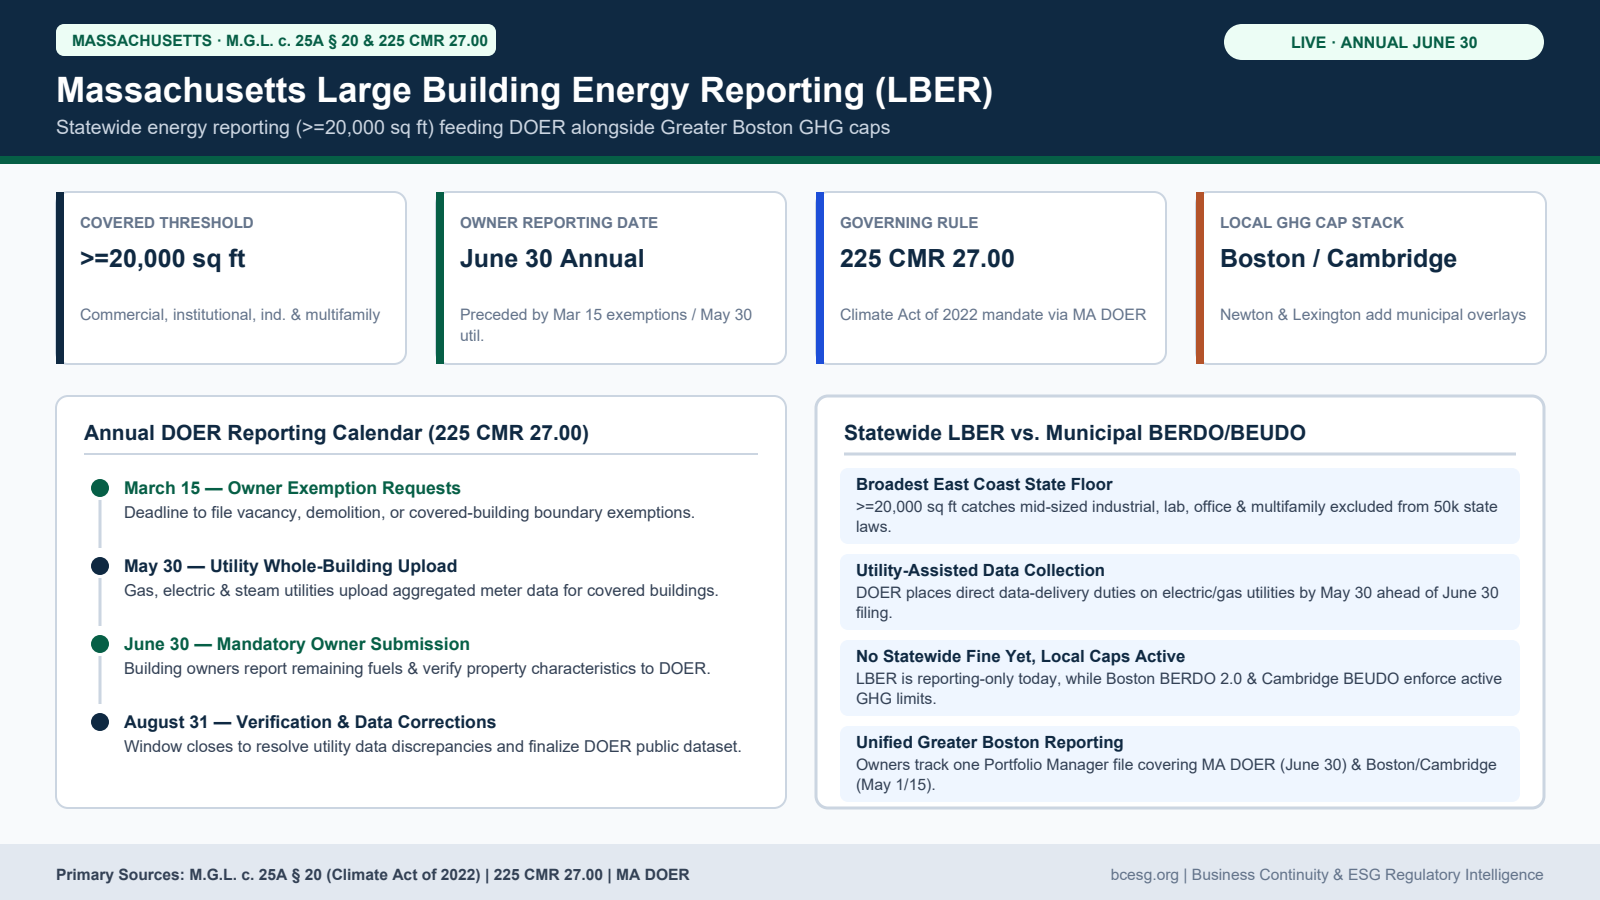
    Short answer: Massachusetts enforces one of the nation’s broadest statewide building energy-reporting thresholds under the Climate Act of 2022 (M.G.L. c. 25A § 20) and Department of Energy Resources regulation 225 CMR 27.00 (MA DOER LBER). Covered commercial, institutional, industrial, and multifamily buildings ≥20,000 gross sq ft must track and reconcile annual whole-building energy consumption with DOER by June 30.

    For Greater Boston owners, statewide LBER serves as the reporting baseline underneath strict local decarbonization ordinances: Boston BERDO 2.0 (≥20k sq ft / 15+ units), Cambridge BEUDO (≥25k sq ft / ≥50 units), Newton BERDO (≥20k), and Lexington BEU-D (>25k) all enforce independent municipal spring filings and active emissions limits.

    Statutory Status at a Glance
    • Governing Authority: M.G.L. c. 25A § 20 (2022 Climate Act) & 225 CMR 27.00.
    • Administering Agency: Massachusetts Department of Energy Resources (DOER).
    • Covered Threshold: Commercial, industrial, institutional, and multifamily buildings ≥20,000 gross sq ft statewide.
    • 4-Step Annual Calendar: March 15 (exemptions) → May 30 (utilities upload metered electric/gas/steam) → June 30 (owner reporting) → August 31 (verification/corrections).
    • Performance vs. Reporting Split: Statewide LBER is reporting-only today; municipal Boston BERDO 2.0 and Cambridge BEUDO impose binding GHG limits starting 2025–2026.
    Print-First Compliance Brief

    Align Massachusetts >=20,000 sq ft LBER Filing With Local BERDO & BEUDO Caps

    2-page quick card charting DOER’s 4 annual milestones (Mar 15, May 30, Jun 30, Aug 31) alongside Boston, Cambridge, Newton, and Lexington.

    Inside DOER's Four-Date LBER Reporting Architecture

    Unlike state benchmarking programs that leave owners chasing tenant meter consent, 225 CMR 27.00 places a direct statutory data-delivery duty on Massachusetts electric, gas, and steam distribution utilities. By May 30 each year, utilities submit aggregated consumption records for covered premises directly into the DOER system.

    Property owners remain legally responsible for verifying parcel coverage, submitting delivered-fuel bills (fuel oil, propane, biomass), claiming vacancies or industrial exemptions by March 15, completing owner submissions by June 30, and resolving any utility anomalies prior to August 31.

    • Industrial & Lab Coverage: Because M.G.L. c. 25A § 20 includes industrial buildings ≥20,000 sq ft, Route 128 life-science labs, cold storage, and suburban manufacturing plants are swept in alongside office towers.
    • Parcel vs. Condominium Boundaries: Multiple buildings sharing single parcels require careful gross-floor-area verification against municipal assessor records before the March 15 exemption cutoff.
    DOER Milestone DateResponsible PartyAction Under 225 CMR 27.00
    March 15Building OwnerSubmit boundary, vacancy, or statutory exemption requests to DOER
    May 30Utilities (Electric/Gas/Steam)Upload aggregated whole-building energy usage for covered >=20k properties
    June 30Building OwnerComplete owner energy submission (incl. delivered oil/propane & property metadata)
    August 31Owner & DOER VerificationFinalize discrepancy corrections before public DOER dataset publication
    Massachusetts Large Building Energy Reporting (LBER / 225 CMR 27.00) infographic showing >=20,000 sq ft threshold, March 15-August 31 DOER calendar, and local Boston BERDO / Cambridge BEUDO caps.
    Massachusetts LBER (M.G.L. c. 25A § 20 & 225 CMR 27.00) four-milestone annual reporting calendar and local GHG cap interaction.

    Synchronizing Statewide LBER With Boston BERDO 2.0 & Neighboring States

    Inside Boston and Cambridge, owners run two distinct calendars out of the same Portfolio Manager dataset: Cambridge BEUDO filings land on May 1 and Boston BERDO 2.0 filings land on May 15—more than six weeks before Massachusetts DOER’s June 30 owner deadline. Ensuring third-party data verification covers both local emissions compliance and DOER records eliminates mid-summer rework.

    Northeast regional managers should track Massachusetts alongside New Jersey’s July 1 benchmarking (>25k sq ft) and NYC’s May 1 LL84/LL97 stack.

    Compliance Execution Checklist

    StepOwner / TeamAuditable Deliverable
    1. DOER List AuditAsset MgmtCheck DOER covered-building list for every MA commercial/industrial/MF parcel >=20,000 sq ft.
    2. Mar 15 ExemptionsCompliance LeadFile any demolition, under-threshold, or vacancy exemption documentation prior to March 15.
    3. Utility MatchFacilities /OpsConfirm May 30 utility uploads capture all meters and compile delivered heating oil/propane invoices.
    4. Local Overlay SyncSustainabilityAlign May 1 (Cambridge) / May 15 (Boston) filings with June 30 MA LBER owner certification.
    Field & Print Package

    Keep This Massachusetts Compliance Checklist Handy

    Download the formatted 2-page PDF reference brief or pull the structured Markdown edition for internal compliance documentation.

    Frequently Asked Questions

    Are industrial warehouses and life-science labs covered by Massachusetts LBER?

    Yes. M.G.L. c. 25A § 20 and 225 CMR 27.00 explicitly include commercial, institutional, industrial, and multifamily buildings of 20,000 gross sq ft or more.

    Does Massachusetts LBER impose carbon emissions fines like Boston BERDO 2.0?

    Statewide LBER is an annual energy reporting mandate overseen by DOER and does not currently levy numeric carbon-cap penalties, whereas Boston BERDO 2.0 and Cambridge BEUDO impose binding emissions limits and Alternative Compliance Payments locally.

    When must a building owner submit LBER reports to DOER?

    Owner reports are due June 30 annually, following March 15 exemption filings and May 30 utility uploads, with verification/corrections closing August 31.

    Primary Authorities & Official Resources

    Informational notice: This guide summarizes enacted statutes, regulations, or pending legislative records from the primary authorities linked above as of November 14, 2026. It is not legal, accounting, or licensed engineering advice.
  • California Building Energy Benchmarking (AB 802): June 1 Filing, Penalties & SB 253 Bridge

    California Building Energy Benchmarking (AB 802): June 1 Filing, Penalties & SB 253 Bridge

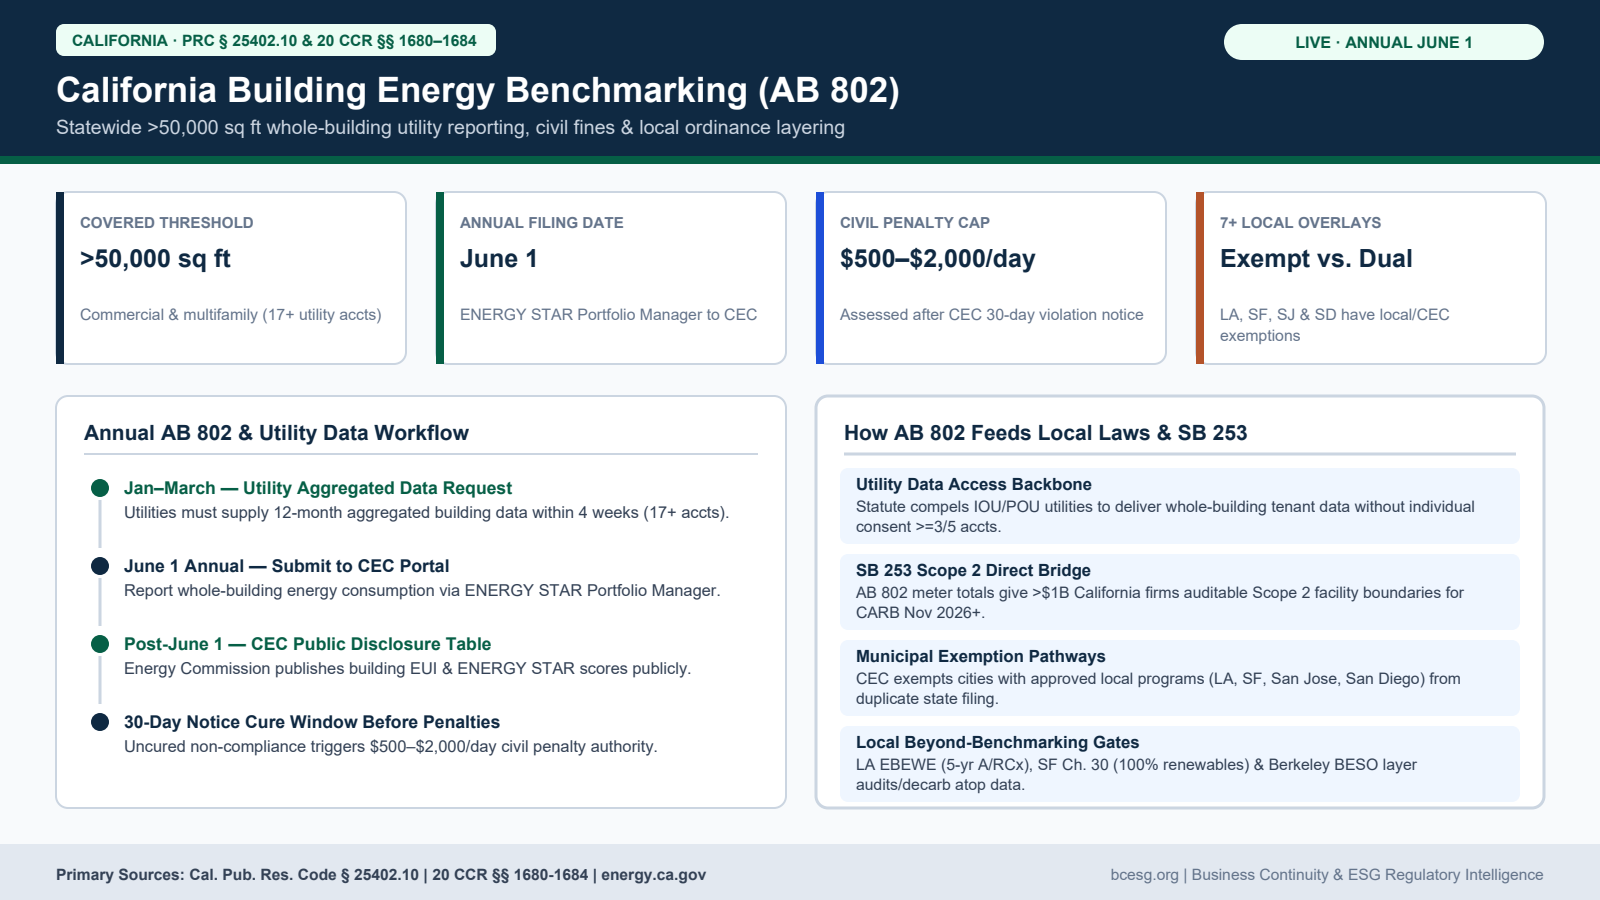
    Short answer: California’s statewide AB 802 Building Energy Benchmarking Program (Cal. Pub. Res. Code § 25402.10; 20 CCR §§ 1680–1684) requires owners of commercial and multifamily buildings over 50,000 gross sq ft with 17 or more active utility accounts to report whole-building energy use via ENERGY STAR Portfolio Manager every June 1.

    Even for corporations focused on California’s broader corporate rules—such as SB 253 Scope 1–3 GHG reporting—AB 802 is the operational data engine: its mandatory utility aggregation rule unlocks tenant-metered whole-building electricity and gas figures that feed directly into corporate Scope 2 inventories and local municipal audits across seven California cities.

    Statutory Status at a Glance
    • Governing Authority: Cal. Pub. Res. Code § 25402.10 (AB 802) & CEC Regulations 20 CCR §§ 1680–1684.
    • Administering Agency: California Energy Commission (CEC).
    • Covered Threshold: Commercial buildings (>50,000 sq ft, any account count above utility aggregation rules—generally >50k w/ 0/17+ rules per CEC account triggers) and multifamily buildings (>50,000 sq ft with ≥17 active residential/commercial utility accounts).
    • Deadline & Penalty: Annual June 1 filing; civil penalties of $500–$2,000 per day after 30-day uncured violation notice.
    • Local Exemptions: CEC recognizes approved local programs (LA EBEWE, SF EBO, San Jose BPO, San Diego) so owners avoid redundant state reporting while complying locally.
    Print-First Compliance Brief

    Connect California AB 802 Meter Data to Municipal Audits & SB 253 Scope 2

    2-page quick card detailing CEC June 1 reporting, utility aggregated data requests (4-week rule), local exemptions (LA, SF, SJ, SD), and civil fines.

    Threshold Nuances: The 17-Utility-Account Rule & Utility Data Rights

    AB 802 pairs two legal triggers that separate multi-tenant assets from single-user campuses: a building must exceed 50,000 gross sq ft and fall within CEC’s active utility account rules (notably 17+ active utility accounts for multifamily residential, or covered commercial configurations with no residential/non-residential exceptions).

    Crucially, AB 802 empowers owners against recalcitrant tenants: utilities must provide aggregated whole-building energy usage within four weeks of request, automatically bypassing individual tenant written authorization when a building contains at least 3 commercial accounts or 5+ residential accounts.

    • Public Transparency: CEC publishes benchmarked Energy Use Intensity (EUI) and ENERGY STAR scores on a public database for disclosable buildings.
    • 30-Day Cure Notice: Before imposing daily fines ($500–$2,000/day), CEC issues a formal written warning granting 30 days to cure missing submissions.
    Program ElementAB 802 Rule CitationOwner Requirement & Enforcement
    Covered Size & AccountsCal. Pub. Res. Code § 25402.10>50,000 gross sq ft commercial & multifamily (>=17 active utility accts)
    Utility Aggregation20 CCR § 1682 / Utility MandateUtilities deliver 12-mo aggregated data within 4 weeks (3 com / 5 res thresh)
    Annual CEC Deadline20 CCR § 1683Annual June 1 ENERGY STAR Portfolio Manager submission
    Civil Penalty ScheduleCal. Pub. Res. Code § 25402.10(f)$500–$2,000/day after 30-day uncured CEC notice
    California AB 802 building energy benchmarking visual summary showing >50,000 sq ft threshold, June 1 CEC deadline, $500-$2,000/day penalty window, and links to SB 253 and local cities.
    California AB 802 statewide benchmarking duties, utility data access rules, civil penalty range, and municipal exemption map under 20 CCR §§ 1680–1684.

    Bridge to California Local Ordinances & SB 253 Scope 2 Inventories

    California does not enforce a single statewide Building Performance Standard cap yet—local cities carry the performance and audit teeth. While CEC exempts properties already reporting under approved local ordinances (Los Angeles EBEWE, San Francisco EBO, San Jose BPO, and San Diego), owners inside those cities face much lower square-footage floors (10,000–20,000 sq ft) and five-year retro-commissioning or renewable electricity obligations.

    Meanwhile, large corporations (>$1B revenue) subject to California SB 253 Scope 1 and Scope 2 disclosures rely on AB 802 utility aggregates to reconcile leased-building operational boundaries without double counting.

    Compliance Execution Checklist

    StepOwner / TeamAuditable Deliverable
    1. Local vs. CEC CheckPortfolio LeadVerify if building sits in a CEC-exempt approved city (LA, SF, San Jose, San Diego) vs. direct CEC filing.
    2. Request Utility FeedsProperty OpsRequest aggregated 12-month data from IOU/POU utilities in Feb/Mar (allow 4+ weeks SLA).
    3. File by June 1Asset MgmtRun Portfolio Manager data quality checker and submit via annual CEC reporting link before June 1.
    4. Reconcile SB 253Corporate ESGMap Portfolio Manager meter boundaries to corporate SB 253 Scope 2 & Cat 13 disclosures.
    Field & Print Package

    Keep This California Compliance Checklist Handy

    Download the formatted 2-page PDF reference brief or pull the structured Markdown edition for internal compliance documentation.

    Frequently Asked Questions

    Do buildings in Los Angeles or San Francisco have to file twice for AB 802 and local ordinances?

    No, provided the property complies fully with a CEC-approved local benchmarking program (including LA EBEWE, San Francisco EBO, San Jose BPO, and San Diego), CEC exempts the building from duplicate state submission—though local filing deadlines (such as May 1 in SF/SJ) differ from June 1.

    Why does AB 802 matter for California SB 253 Scope 2 compliance?

    AB 802's statutory whole-building utility aggregation gives corporate tenants and building owners auditable electricity and gas totals across multi-tenant assets needed for Scope 2 and Scope 3 Category 13 GHG inventories.

    What is the penalty for ignoring a California Energy Commission AB 802 notice?

    After issuing a 30-day written notice of violation, the CEC may assess administrative civil penalties ranging from $500 to $2,000 per day until compliance is demonstrated.

    Primary Authorities & Official Resources

    Informational notice: This guide summarizes enacted statutes, regulations, or pending legislative records from the primary authorities linked above as of November 14, 2026. It is not legal, accounting, or licensed engineering advice.
  • Oregon Statewide Building Performance Standard (HB 3409 & OAR 330-300): Tier 1 & Tier 2 Guide

    Oregon Statewide Building Performance Standard (HB 3409 & OAR 330-300): Tier 1 & Tier 2 Guide

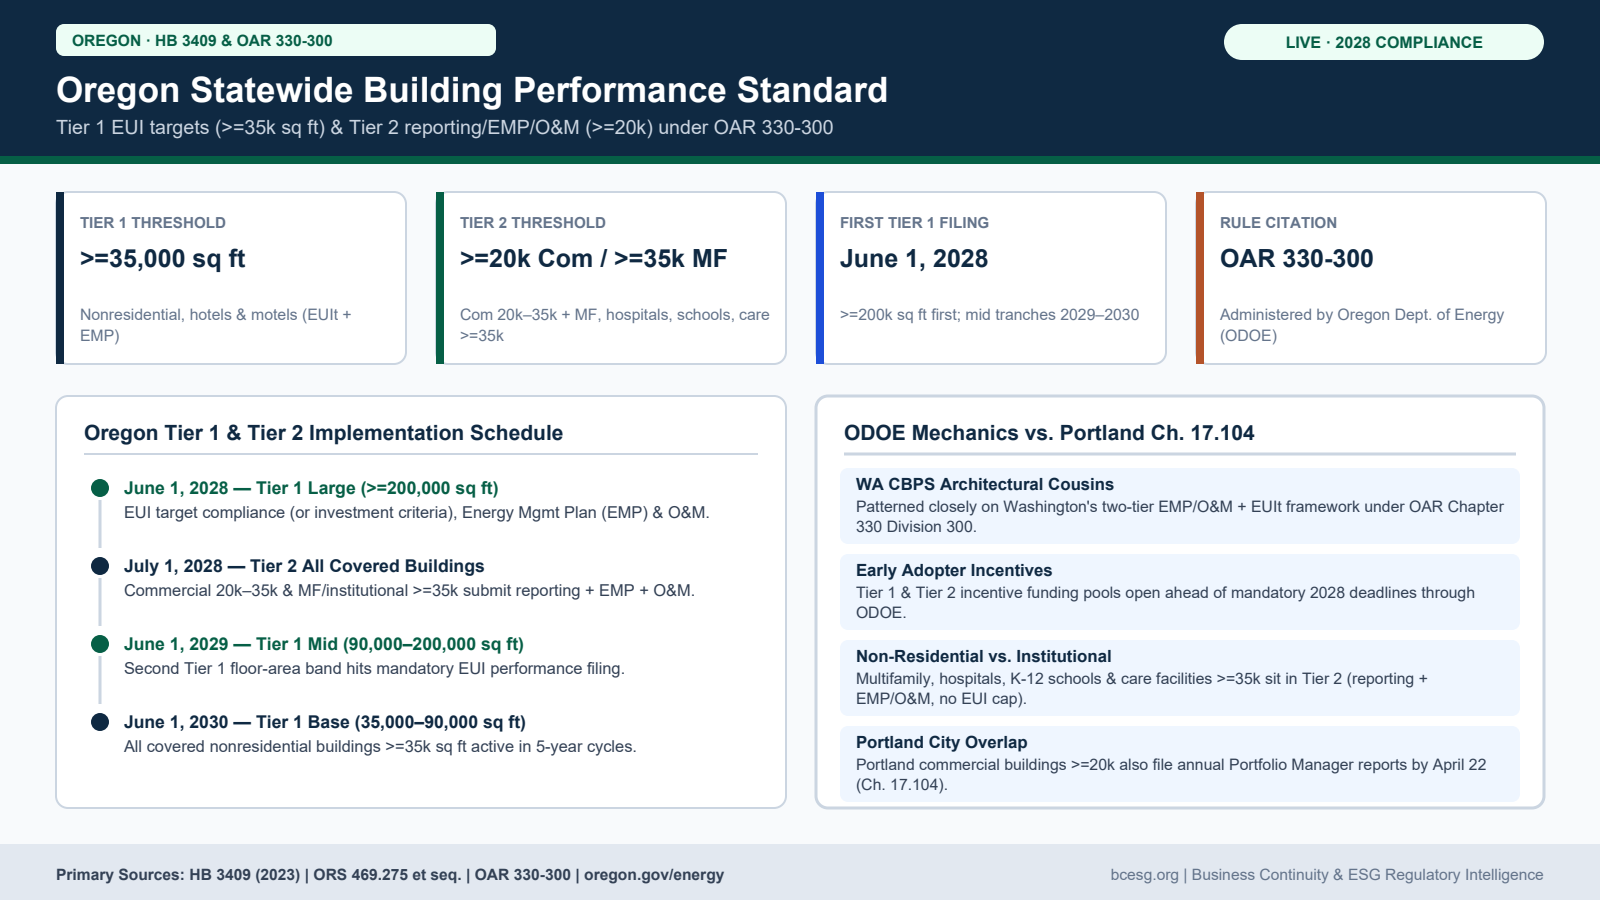
    Short answer: Oregon adopted a statewide two-tier Building Performance Standard under HB 3409 (codified at ORS 469.275 et seq.) and finalized operational rules in Oregon Department of Energy (ODOE) OAR Chapter 330, Division 300. Modeled directly on Washington’s Clean Buildings architecture, Oregon requires Tier 1 nonresidential buildings (≥35,000 sq ft) to hit Energy Use Intensity targets or investment criteria starting June 1, 2028, while Tier 2 commercial and institutional/multifamily properties begin mandatory reporting, EMP, and O&M compliance on July 1, 2028.

    Crucial rule-citation note: ODOE’s binding BPS rules live in OAR 330-300 (not OAR 330-135), and statewide compliance runs separately from Portland’s local energy reporting and 2050 carbon step-down ordinance track.

    Statutory Status at a Glance
    • Governing Authority: HB 3409 (2023), ORS 469.275 et seq., and ODOE Administrative Rules OAR 330-300.
    • Administering Agency: Oregon Department of Energy (ODOE).
    • Tier 1 (≥35,000 sq ft Nonresidential/Hotels/Motels): EUI target (or LCCA investment criteria) + EMP + O&M due June 1, 2028 (≥200k), June 1, 2029 (90k–200k), and June 1, 2030 (35k–90k).
    • Tier 2 (20k–35k Com & ≥35k MF/Hospitals/Schools/Care): Reporting + EMP + O&M due July 1, 2028 (no numeric Tier 1 EUIt cap in Cycle 1).
    • Incentives Window: ODOE Early Adopter Incentive funds support early Tier 1 & Tier 2 compliance preparation prior to 2028 enforcement.
    Print-First Compliance Brief

    Map Oregon HB 3409 Tier 1 & Tier 2 Compliance Under OAR 330-300

    2-page quick card distinguishing Oregon’s statewide OAR 330-300 rules (2028–2030 Tier 1/2 dates) from Portland City Code Ch. 17.104.

    Tier 1 vs. Tier 2 Classification Under OAR 330-300

    Understanding where an Oregon asset lands between Tier 1 and Tier 2 determines whether the owner faces capital retrofit obligations (or an LCCA investment audit) versus operational governance and energy reporting. Unlike Washington’s >50,000 sq ft Tier 1 floor, Oregon pulls nonresidential buildings down to 35,000 sq ft inside Tier 1.

    Conversely, Oregon places multifamily housing, hospitals, K-12 schools, universities, and senior care buildings ≥35,000 sq ft into Tier 2 alongside smaller commercial buildings (20,000–34,999 sq ft)—requiring benchmarking, an Energy Management Plan, and an O&M program without immediate EUIt caps.

    • ASHRAE Standard 100 Adaptation: ODOE builds EUIt benchmarks by building activity type and climate zone, requiring a qualified Energy Manager to sign EMP and O&M documentation.
    • 5-Year Recurring Cycles: After initial 2028–2030 filings, covered Tier 1 & Tier 2 buildings re-verify compliance every five years.
    Oregon BPS TierBuilding Types & Square FootageFirst Compliance Date & Core Duties
    Tier 1 — LargestNonresidential, hotels, motels >=200,000 sq ftJune 1, 2028 — EUIt / LCCA + EMP + O&M
    Tier 1 — MidNonresidential, hotels, motels 90,000–199,999 sq ftJune 1, 2029 — EUIt / LCCA + EMP + O&M
    Tier 1 — BaseNonresidential, hotels, motels 35,000–89,999 sq ftJune 1, 2030 — EUIt / LCCA + EMP + O&M
    Tier 2 — Com & Inst/MFCommercial 20k–35k sq ft; MF/hospitals/schools >=35kJuly 1, 2028 — Energy reporting + EMP + O&M
    Oregon Statewide Building Performance Standard (HB 3409 / OAR 330-300) summary showing Tier 1 >=35,000 sq ft EUI targets, Tier 2 >=20,000 sq ft reporting/EMP/O&M, 2028-2030 dates, and Portland Ch. 17.104 distinction.
    Oregon Statewide Building Performance Standard (HB 3409 / OAR 330-300) compliance schedule and Portland dual-reporting structure.

    Pacific Northwest Portfolio Alignment: Oregon, Washington & Portland

    For commercial real estate portfolios spanning I-5 from Seattle to Portland, Oregon’s OAR 330-300 deliberately tracks Washington’s CBPS (WAC 194-50)—allowing engineering teams to reuse Energy Management Plan templates and O&M manuals with Oregon-specific EUIt tables.

    Inside Portland city limits, owners must also track Portland City Code Chapter 17.104 (annual April 22 energy reporting for commercial buildings ≥20,000 sq ft) alongside the city’s 2050 building carbon step-down policy. Waiting until 2028 leaves insufficient time for a mandatory 12-month metered O&M baseline.

    Compliance Execution Checklist

    StepOwner / TeamAuditable Deliverable
    1. Tier VerificationAsset MgmtClassify each OR property >=20,000 sq ft under Tier 1 (>=35k nonres) vs Tier 2 under OAR 330-300.
    2. Incentive ScreenFinance / ESGCheck ODOE Early Adopter Incentive eligibility before 2028 funding windows close.
    3. EMP & O&M BuildOperationsStand up written EMP and 12 months of logged preventive O&M records at least 18 months pre-deadline.
    4. Portland SyncCompliance LeadPair statewide ODOE preparation with Portland April 22 Ch. 17.104 annual Portfolio Manager filings.
    Field & Print Package

    Keep This Oregon Compliance Checklist Handy

    Download the formatted 2-page PDF reference brief or pull the structured Markdown edition for internal compliance documentation.

    Frequently Asked Questions

    Where are Oregon's binding BPS rules codified?

    Oregon Department of Energy (ODOE) implements HB 3409 (ORS 469.275 et seq.) inside Oregon Administrative Rules Chapter 330, Division 300 (OAR 330-300).

    Are Oregon multifamily buildings subject to numeric Tier 1 EUI caps?

    No. Multifamily residential buildings of 35,000 sq ft or larger fall under Tier 2, requiring energy use reporting, an Energy Management Plan (EMP), and an O&M program starting July 1, 2028.

    Does complying with Portland Ch. 17.104 satisfy Oregon HB 3409?

    No. Portland City Code Chapter 17.104 governs annual April 22 commercial energy reporting in Portland, whereas OAR 330-300 enforces statewide Tier 1 EUIt targets and Tier 2 EMP/O&M governance through ODOE.

    Primary Authorities & Official Resources

    Informational notice: This guide summarizes enacted statutes, regulations, or pending legislative records from the primary authorities linked above as of November 14, 2026. It is not legal, accounting, or licensed engineering advice.
  • Maryland BEPS (COMAR 26.28 & HB 49): June 1 Verification, Fees & Montgomery County Carve-Out

    Maryland BEPS (COMAR 26.28 & HB 49): June 1 Verification, Fees & Montgomery County Carve-Out

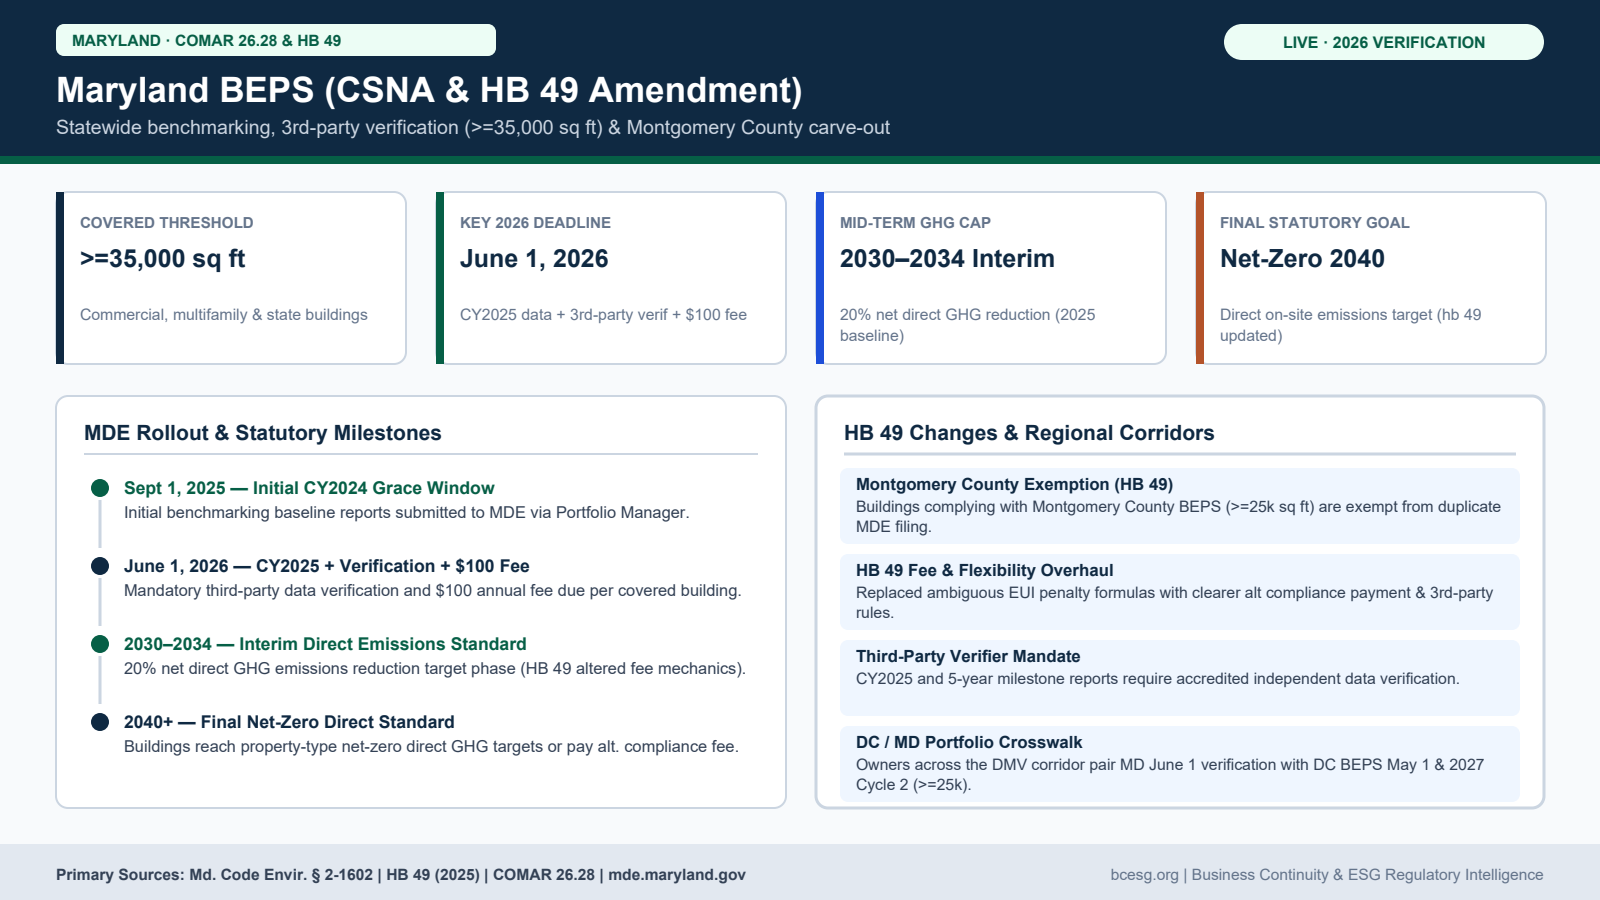
    Short answer: Maryland’s statewide Building Energy Performance Standards (MDE BEPS / COMAR 26.28) moved from initial grace benchmarking into verified, fee-backed execution on June 1, 2026. Owners of commercial, multifamily, and state buildings ≥35,000 gross sq ft must file CY2025 energy data backed by third-party data verification and a $100 annual reporting fee—on the path toward 2030 interim and 2040 net-zero direct emissions caps.

    Just as critical for DMV-area portfolios: House Bill 49 (2025) resolved the state-versus-county overlap by exempting buildings complying with Montgomery County’s BEPS ordinance from filing duplicate state reports—while neighboring Washington, D.C. BEPS drops its Cycle 2 threshold to 25,000 sq ft on January 1, 2027.

    Statutory Status at a Glance
    • Governing Authority: Md. Code Envir. § 2-1602 (Climate Solutions Now Act of 2022), amended by HB 49 (2025); COMAR 26.28.
    • Administering Agency: Maryland Department of the Environment (MDE) Clean Buildings Program.
    • Covered Threshold: Commercial, multifamily, and state-owned buildings ≥35,000 gross sq ft (excluding parking garages).
    • Annual Verification & Fee: June 1 annual Portfolio Manager filing; CY2025 milestone (June 1, 2026) introduced mandatory third-party verification + $100 fee.
    • Direct GHG Trajectory: Interim 2030–2034 targets leading to net-zero direct (Scope 1) on-site emissions in 2040.
    Print-First Compliance Brief

    Prepare Maryland >=35,000 sq ft Buildings for Third-Party Verification & Direct GHG Caps

    2-page quick card mapping MDE COMAR 26.28 verification rules, HB 49 fee reforms, Montgomery County exemption boundaries, and DC BEPS portfolio coordination.

    What HB 49 Changed for Owners, Fees, and Local Carve-Outs

    When MDE first promulgated COMAR 26.28, building owners challenged both the initial EUI compliance friction and duplicate state/county compliance burdens in Montgomery County. The 2025 passage of HB 49 streamlined administration without delaying decarbonization.

    First, HB 49 clarified that buildings covered by and compliant with Montgomery County BEPS (≥25,000 sq ft) need not submit duplicative filings under MDE’s state program. Second, HB 49 formalized the $100 annual benchmarking fee schedule and adjusted EUI vs. direct GHG alternative-compliance fee structures to align with achievable electrification cycles.

    • Direct vs. Site EUI Lens: Maryland uniquely targets net direct (on-site fossil fuel) greenhouse gas emissions rather than electricity-heavy total emissions caps—accelerating heat-pump water heating and HVAC electrification.
    • Accredited Verifiers Required: Starting with CY2025 reports and recurring every five years (as well as interim compliance milestones), an accredited third-party verifier must attest to meter boundaries and square footage.
    Milestone / ProvisionApplicabilityStatutory Deadline & Rule
    Initial CY2024 Benchmarking>=35,000 sq ft commercial/MF/stateSept 1, 2025 (initial grace deadline completed)
    CY2025 Verified FilingNon-exempt buildings >=35,000 sq ftJune 1, 2026 + mandatory 3rd-party verifier + $100 fee
    Montgomery County ExemptionMontgomery County BEPS >=25k buildingsExempt from duplicate MDE state filing per HB 49 (2025)
    2030 & 2040 Direct GHG CapsInterim 2030–2034 -> Final 204020% net direct GHG cut (2030+) -> Net-zero direct 2040
    Maryland BEPS statutory breakdown showing >=35,000 sq ft scope, June 1, 2026 third-party verification and $100 fee deadline, 2030/2040 direct GHG targets, and Montgomery County HB 49 exemption.
    Maryland Building Energy Performance Standards (BEPS) compliance roadmap under Md. Code Envir. § 2-1602, HB 49 (2025), and COMAR 26.28.

    Synchronizing Maryland (≥35k) With D.C. BEPS (≥25k) and Regional Law

    Real estate operators across the Baltimore–Washington corridor manage overlapping calendars: Washington D.C. closes BEPS Cycle 1 (≥50k sq ft) on December 31, 2026 and drops into Cycle 2 (≥25,000 sq ft) on January 1, 2027, with annual D.C. benchmarking due May 1. One month later, Maryland owners face their June 1 MDE filing deadline.

    Read alongside our D.C. BEPS Cycle 1 & Cycle 2 pathway guide and New Jersey CEA benchmarking guide, Mid-Atlantic asset teams can consolidate ENERGY STAR Portfolio Manager utility feeds and third-party verifier engagements into one spring assurance window.

    Compliance Execution Checklist

    StepOwner / TeamAuditable Deliverable
    1. Exemption CheckCompliance LeadConfirm whether assets sit in Montgomery County BEPS carve-out or <35k sq ft exclusion (excl. parking).
    2. Retain VerifierFacilities / PEContract an MDE-recognized third-party data verifier ahead of spring utility reconciliation.
    3. File & Remit $100Property OpsSubmit verified CY data in Portfolio Manager + pay $100 annual fee to MDE by June 1.
    4. Electrification PlanCapEx EngineeringModel on-site gas equipment replacements ahead of 2030 direct GHG targets and 2040 net-zero rules.
    Field & Print Package

    Keep This Maryland Compliance Checklist Handy

    Download the formatted 2-page PDF reference brief or pull the structured Markdown edition for internal compliance documentation.

    Frequently Asked Questions

    What buildings are exempt under HB 49's Montgomery County provision?

    Buildings located in Montgomery County that comply with Montgomery County's local Building Energy Performance Standards (>=25,000 sq ft) are exempt from filing duplicate statewide reports with MDE under HB 49 (2025).

    When is Maryland BEPS third-party verification required?

    First required with CY2025 data due June 1, 2026 (alongside the $100 annual fee), and at subsequent 5-year compliance verification milestones under COMAR 26.28.

    Does Maryland BEPS regulate electricity emissions or only on-site gas?

    Maryland's interim 2030 and 2040 statutory standards focus specifically on direct on-site greenhouse gas emissions (Scope 1 combustion), though whole-building electric and fuel consumption are both benchmarked annually.

    Primary Authorities & Official Resources

    Informational notice: This guide summarizes enacted statutes, regulations, or pending legislative records from the primary authorities linked above as of November 14, 2026. It is not legal, accounting, or licensed engineering advice.
BC ESG

ESG Strategy, Sustainability Intelligence, and Business Continuity for Forward-Thinking Organizations

© 2026 BC ESG — Business Continuity, ESG & Sustainability Intelligence