Category: Green Finance

Green bonds, sustainability-linked loans, ESG investing, impact finance, and climate-aligned capital markets.

  • How Do Lenders Finance Homes That Aren’t Financeable Yet?

    How Do Lenders Finance Homes That Aren’t Financeable Yet?

    A lender looking at an inefficient home faces a simple fork: lend against the building as it stands, or lend against the building it could become. A new cross-industry white paper, The Trillion-Dollar Housing Transition, published by the Sustainable Real Estate Forum (SREF) in October 2026, argues the second option is where the market now has to learn to work — and that the shortage holding it back is not money. It is the ability to originate, underwrite and execute credible transition pathways at scale.

    The paper was written with contributions from GlobalABC, RICS, the European Mortgage Federation (EMF-ECBC), PATRIZIA, Optiml, pbb Deutsche Pfandbriefbank and INREV, and SREF will distribute it in the Blue Zone at COP31 in Antalya, Türkiye. Its lending chapter, from pbb, reduces the lender’s job to a three-part test: finance the cure, price the residual risk, and withdraw only when neither is credible.

    What is SREF actually claiming?

    The claim is that affordable housing and climate action have to be delivered together, and that capital is not the binding constraint on doing it. “A home that is cheap to build but costly to cool, unsafe in floods or heatwaves, or dependent on high-carbon materials is not affordable over its lifetime,” the paper states. The bottleneck, in SREF’s account, sits one step earlier than the money: in whether the market can produce enough well-evidenced, underwritable retrofit and building pathways for the capital to attach to.

    The scale behind that claim is large by any measure. UN-Habitat estimates that by 2030 three billion people will need access to adequate housing — around 96,000 new affordable and accessible homes every day. Buildings’ operational emissions reached 9.9 GtCO₂ in 2024 and, according to UNEP, would need to fall by 56% by 2030 to align with a net-zero pathway. Roughly 80% of growth in building floor area through 2030 is expected in emerging and developing economies, where underwriting capacity is thinnest.

    Where does the “trillion-dollar” figure come from?

    “Trillion-dollar” is the paper’s framing of the overall scale, not a single line item. SREF’s founder and CEO, Peter Panayi, puts it this way: “The housing transition is a trillion-dollar challenge, but it is also a trillion-dollar opportunity.” The hardest number underneath the framing comes from UNEP: cumulative investment in building energy efficiency needs to reach around USD 5.9 trillion by 2030, compared with roughly USD 2.3 trillion invested between 2015 and 2024.

    The investor side of the ledger supports the “capital is available” half of the argument. €117 billion was raised for non-listed real estate in 2025, and 87% of surveyed managers expect the amount raised to increase over the next two years. INREV estimates Europe needs more than two million new homes a year — around 650,000 more than it builds today — requiring about €153 billion of additional investment each year. The question the paper presses is not whether that money exists. It is whether lenders can tell, home by home, which transition plans deserve it.

    What does “finance the cure” mean in practice?

    It means the lender’s first question about a poor-performing home changes. Instead of asking whether the asset is financeable today, the lender asks whether it can become financeable through a pathway that is credible, funded and capable of being monitored. As Lara Knapwost, Head of ESG at pbb Deutsche Pfandbriefbank, writes in the paper: “Real estate transition is not primarily about buildings that are already efficient and financeable today. The task for lenders is to identify the assets that can become financeable through a credible, funded and monitorable pathway, and to actively support them.”

    Each of those three adjectives does work. Credible means the retrofit or improvement plan is technically real for that building, not a generic pledge. Funded means the money for the works is actually assembled, including any subsidy or affordability support the household needs. Monitorable means the lender can check, over the life of the loan, whether the pathway is being delivered. A plan that fails one of the three is not a cure — it is a hope, and the test says not to price it as one.

    This is where the desk work already familiar to BC ESG readers connects. Deciding which measures come first in an existing building is the problem the Retrofit Priority Stack for Existing Buildings works through; the SREF test adds the lender’s side of the same table — which of those stacked measures, properly sequenced and funded, turns an unfinanceable asset into a lendable one.

    How should lenders price the residual risk that remains?

    Even a well-funded cure leaves risk behind: the works may underperform, energy prices and policy may move, and some homes will still sit below standard at the end of their pathway. The paper’s second instruction is to price that residue openly rather than pretend the cure erased it — or use it as a reason to refuse the loan outright.

    The valuation profession is where this pricing is supposed to become visible. RICS and EMF-ECBC argue that transition risk should become a material input to property valuation where it is supported by evidence. “Where transition risk is material and evidenced, valuers should be supported to reflect it,” says Sander Scheurwater, Head of Benelux at RICS. “The market’s ability to price both action and inaction will be central to the housing transition.” His colleague Gina Ding, RICS Head of Public Affairs Europe, describes the machinery: “Standards create the common language, data creates the evidence, and skilled valuers turn that evidence into professional judgement. When valuation is transparent, capital can tell apart the homes that need investment from those where investment protects value.”

    Pricing inaction matters as much as pricing action. A lender who prices only the risk of a retrofit pathway, and never the risk of holding a book of homes with no pathway at all, will systematically make the wrong call — the stranded-asset end of transition risk arrives through the loans that were never restructured, not just the ones that were. Jennifer Johnson, Deputy Secretary General of EMF-ECBC, ties the threads together: sustainability, valuation and mortgage finance have to align, with a robust understanding of how energy performance relates to property value and financial risk.

    Why can a credible plan still fail to deliver?

    Because a spreadsheet is not a building site. PATRIZIA and Optiml show that a portfolio can have a technically credible decarbonisation plan and still fail to deliver it — because contractors are unavailable, permits take too long, grid capacity is constrained, or households cannot absorb the cost. Nico Dehnert, co-founder of Optiml, is blunt about the substitutes: portfolios “will not be delivered through ESG reports, generic benchmarks or static plans,” but through “credible, investable pathways that connect building reality, financial goals, affordability and execution constraints.”

    So underwriting a pathway means underwriting its delivery chain, not just its engineering. Shreya Sheth of PATRIZIA calls the standard “decision readiness”: multiple investable pathways compared through a common financial and transition logic, so when one route blocks — a permit stalls, a contractor shortage bites — the financing can move to another route instead of dying.

    What do lenders need before they can do this at scale?

    The paper’s closing chapter, from INREV, answers with an Institutional Housing Compact: institutional capital can scale where three conditions hold. Policy must be stable, so a pathway underwritten today is not stranded by a rule change tomorrow. Affordability obligations must be explicitly funded, rather than silently loaded onto borrowers or lenders. And evidence must be common from asset to fund, so risks, returns and outcomes stay comparable as a home’s data travels up into a portfolio. “Capital follows the compact,” writes Jeff Rupp, INREV’s Director of Public Affairs: “stable rules, funded affordability and evidence that survives from asset to fund.”

    That evidence condition is the one lenders control most directly. The discipline of assembling climate and continuity evidence a lender can actually rely on is covered in BC ESG’s Lender and Investor Evidence Pack, and the wider lending and disclosure context sits in ESG in Banking and Investment: Risk, Lending, and Disclosure. GlobalABC’s opening chapter makes the matching point at country level: global commitments only convert into housing when they become country-owned delivery systems.

    And withdrawal? The test’s third clause is deliberately narrow: a lender withdraws only when neither side works — no credible cure can be financed and the residual risk cannot be honestly priced. It is the last resort of the test, not its default.

    Frequently asked questions

    What is The Trillion-Dollar Housing Transition?
    It is a white paper published by the Sustainable Real Estate Forum (SREF) in October 2026, with contributions from GlobalABC, RICS, EMF-ECBC, PATRIZIA, Optiml, pbb Deutsche Pfandbriefbank and INREV. It argues that affordable housing and climate action must be delivered together, and it will be distributed in the Blue Zone at COP31 in Antalya, Türkiye.

    Why does the paper say capital is not the constraint?
    Because the investment need — UNEP estimates cumulative building energy-efficiency investment of around USD 5.9 trillion is needed by 2030 — sits alongside demonstrated investor appetite, including €117 billion raised for non-listed real estate in 2025. The paper argues the binding limit is the market’s ability to originate, underwrite and execute credible transition pathways at the scale the capital requires.

    What is the lender’s three-part test in the paper?
    From pbb Deutsche Pfandbriefbank’s chapter: finance the cure, price the residual risk, and withdraw only when neither is credible. In practice: first ask whether a home can become financeable through a credible, funded and monitorable improvement pathway; then price whatever transition risk remains, transparently, through valuation; and treat withdrawal as a last resort.

    What does “residual risk” mean for a home that has a retrofit plan?
    It is the transition risk left over after the planned works: underperformance of the measures, energy-price and policy movement, and any gap between the home’s end state and the standard the market will expect. RICS argues valuers should reflect that risk in valuations where it is material and evidenced — alongside the risk of inaction, which often goes unpriced.

    Does this change anything for an individual borrower today?
    Not directly — nothing in the paper is a lending decision about any individual home. It signals direction: lenders are being urged by their own industry bodies to build underwriting that rewards credible improvement pathways and to put transition risk into valuations. Whether and when any specific lender adopts that is that lender’s decision.

    Sources

    • SREF / PR Newswire launch release for The Trillion-Dollar Housing Transition (28 October 2026), including quotes from Peter Panayi (SREF), Lara Knapwost (pbb Deutsche Pfandbriefbank), Sander Scheurwater and Gina Ding (RICS), Jennifer Johnson (EMF-ECBC), Shreya Sheth (PATRIZIA), Nico Dehnert (Optiml) and Jeff Rupp (INREV), and figures attributed there to UN-Habitat, UNEP and INREV.

    This article is general information about a published industry paper. It is not investment, lending or financial advice, and it is not a recommendation for or against any product, property or course of action.

  • When Can an Outcome Bond Fund Carbon Removal Equipment Before the Credits Exist?

    When Can an Outcome Bond Fund Carbon Removal Equipment Before the Credits Exist?

    The short answer: when three things are already in place before the bond is sold. A creditworthy buyer has signed a long-term offtake for the credits the equipment will produce. The credits themselves are durable and registry-verifiable, so “delivered” is a fact a third party can check. And the bond’s structure lets investors keep their principal while staking only their return on delivery. Citi’s $72 million Carbon Removal-Linked Note for Applied Carbon, closed this month, is the worked example — the first outcome bond Citi has tied to verified carbon removals.

    The deal, in one pass

    Citi issued a $72 million, 3.5-year, principal-protected note whose proceeds finance Applied Carbon’s mobile biochar deployment across Texas farmland. There are no conventional coupons. Investors receive payments linked to the generation, verification, and delivery of carbon removal credits the project produces — if the credits are not issued and delivered, the payments tied to them do not flow.

    Applied Carbon’s equipment is the reason the financing has to arrive first. Its mobile pyrolysis units process crop residue directly in the field, converting agricultural waste into biochar in a single pass and applying it to the soil, where the carbon stays stored for hundreds of years. The machines have to be built and deployed before a single credit exists. That ordering — equipment, then credits, then revenue — is the whole problem the note is designed to solve.

    Nuveen participated as a primary buyer, citing the note’s relative value, its impact reporting, and the credit backing of the project’s off-taker. Microsoft holds a long-term carbon credit purchase agreement with Applied Carbon, signed in 2022, covering a portion of the project’s credits. Sonia Battikh, Citi’s Global Head of Carbon Offsets Trading, framed the gap the structure fills: “The voluntary carbon market requires new financial structures to bridge the gap between investor capital and the long-term funding needs of carbon removal projects.”

    The timing mismatch is the market’s core problem

    Carbon removal projects spend money in the opposite order from the one lenders prefer. Conventional debt wants a revenue history; a removal project has a purchase contract and a field. Venture capital will fund the early stage, but it prices for equity upside and exits, not for fleets of field equipment that pay back over years of credit deliveries.

    The World Bank named this exact mismatch when it issued its own credit-linked outcome bond for a Vietnam water-purifier project: projects need up-front financing for capital and operating costs, and the carbon credits arrive a year or more later, after verification. Its answer was the same shape as Citi’s — channel capital-market money in at the start, and link what investors earn to credits actually issued. The Citi note applies that development-finance pattern to a commercial removal developer, at commercial scale, with a corporate offtake standing behind the revenue instead of a donor.

    How the structure re-slices the risk

    Principal protection removes the risk institutional fixed income cannot hold. A pension-grade buyer cannot put client principal on whether a Texas biochar fleet hits its production plan. Protecting the principal takes that question off the table. What remains at risk is the return — and the return is allowed to depend on delivery, because that is the part the buyer is being paid to underwrite.

    Delivery-linked payments keep the outcome incentive inside the security. In a conventional bond, the issuer owes the coupon whether or not anything is removed from the atmosphere. Here the payments exist only when verified credits are generated and delivered. The investor’s upside and the project’s environmental output are the same event, which is what “outcome bond” means when the label is earned.

    The anchor offtake turns a delivered credit into a receivable. A verified credit with no buyer is inventory. A verified credit under a long-term purchase agreement with Microsoft is contracted revenue. The offtake is what lets a structurer model the cash flows, what lets Nuveen describe the note as credit-backed, and what separates this financing from a bet on future spot prices in the voluntary market.

    What the offtake does — and what it does not do

    The Microsoft agreement was signed in 2022, four years before this note. The bond did not create that demand; it borrowed against its credibility. That sequence matters for anyone hoping to copy the structure: the financing was possible because the revenue anchor predated it, not the other way around.

    The limits deserve equal weight. The offtake covers a portion of the project’s credits, not all of them. The full credit volume, the delivery schedule, the price per credit, and the note’s exact return formula have not been disclosed publicly. An anchor offtake makes a project financeable; it does not, by itself, underwrite every tonne the equipment could produce, and no reader of this deal’s public record can verify the coverage ratio.

    There is a second question the headline number cannot answer. In the World Bank’s $100 million plastic waste outcome bond — a deal Citi itself lead-managed — about $14 million of the headline was the up-front financing the projects actually received. Outcome-bond headlines describe the note, not the project capital. How much of this note’s $72 million reaches Applied Carbon as deployment capital, and on what schedule, is not in the public record either. It is the first question a diligence process should ask of any deal built this way.

    When this shape works

    The credits are durable and verifiable. The structure prices delivery, so delivery has to be measurable by an independent registry on a schedule the note’s term can contain. Biochar’s multi-century storage and established verification pathways fit; a credit class with contested permanence would not.

    A creditworthy anchor buyer signed before the financing. The offtake is the revenue story the structurer sells to the bond buyer. Without it, there is nothing to link payments to except hope and spot prices.

    Equipment is the bottleneck, not demand. This shape funds machines that produce contracted output. It does not fix a project whose problem is finding buyers.

    The developer can survive the verification lag. Payments follow issued credits, and issuance trails production. A developer without the balance sheet — or the structurer’s up-front allocation — to bridge that gap will stall between making biochar and getting paid for it.

    Applied Carbon’s founder and CEO, Jason Aramburu, described the ambition plainly: projects like his “can be structured and financed like any other asset.” This note is evidence for a narrower and more useful claim. A removal project can be financed like an asset when a named buyer has already agreed to purchase its output, the output can be verified by someone other than the seller, and the financing is honest about which risks sit with the principal and which sit with the return. Where any one of those three is missing, the outcome bond is not a shortcut. It is a label.

    Deal coverage: ESG News, ESG Post, Carbon Herald, and CarbonCredits.com, October 2026 — terms consistent across all four. Outcome-bond precedent: World Bank outcome bond program materials, including its Emission Reduction-Linked Bond and Plastic Waste Reduction-Linked Bond documentation. Undisclosed items are noted in the text where they occur.

  • When Can Insurance Replace Part of a Carbon Buffer Pool Without Weakening Reversal Protection?

    When Can Insurance Replace Part of a Carbon Buffer Pool Without Weakening Reversal Protection?

    On October 20, carbon removal registry Isometric introduced an insurance framework, developed with broker Marsh, that lets developers of Isometric-certified reforestation projects replace part of their buffer pool contributions with insurance. Five providers — Artio, CarbonPool, CFC, Kita and Oka — are approved to offer the coverage, and other insurers can apply to join. The promise is straightforward: fewer certificates locked in reserve, more revenue in a project’s early years.

    The question that decides whether this is progress or dilution is narrower: under what conditions can an insurance policy stand in for part of a buffer pool without weakening the reversal protection the pool exists to provide?

    What the buffer pool is doing in the first place

    A buffer pool is the carbon market’s self-insurance. A share of every project’s issued certificates is withheld into a shared reserve instead of being sold. If a project later loses stored carbon — a wildfire, a disease outbreak, a failed plantation — certificates from the pool are cancelled against the loss, so a credit a buyer already retired still represents a tonne of carbon removed. It is the same integrity machinery we walked through in how carbon credits are accounted for under the GHG Protocol.

    The cost of that protection is real, and it is timed badly. Withheld certificates cannot be sold, and the withholding bites hardest in a project’s early years, when planting and operating costs are at their peak and revenue is thinnest. Every certificate in the pool is integrity you can point to — and cash the project does not have.

    What the framework actually changes

    Two features of the design matter more than the headline. First, the substitution is partial: insurance replaces part of a project’s buffer contribution, not the buffer itself. Marsh’s Hema Mistry, CEO of FINPRO UK at Marsh Risk, describes the framework as establishing requirements for using insurance alongside existing buffer mechanisms. Second, it is gated: the policy must meet Isometric’s requirements and come from a provider the registry has approved. The registry, not the developer, decides what counts as an adequate substitute.

    Isometric’s chief commercial officer, Lukas May, states the design intent plainly: the framework gives developers “more flexibility when the economics matter most, without compromising on the safeguards that ensure every certificate buyers retire represents a tonne of carbon removed from the atmosphere.” Bruno Figueiredo, VP of Finance at reforestation developer Mombak, calls it “an important step toward a more mature carbon market,” arguing insurance can give buyers greater certainty while developers manage reversal risk more efficiently.

    When substitution holds up — and when it weakens protection

    Whether an insured buffer is as strong as a stocked one depends on terms that are not yet public. Isometric has not disclosed pricing, coverage limits, eligibility thresholds or an implementation date — so the honest answer today is conditional. The conditions that decide it:

    • The insured perils must match the pool’s perils. The pool absorbs reversals from fire, disease and project failure alike. A policy that covers fire but excludes disease or insolvency substitutes for only part of the risk while releasing the whole contribution.
    • The payout must restore certificates, not just compensate the developer. Buffer protection runs to the buyer and the registry: reversed tonnes get cancelled and replaced. A cash payment to a developer who may no longer be operating does not, by itself, retire a replacement tonne.
    • The term must face the horizon. Reversal obligations run for decades; insurance is typically written in years. Substitution holds only if renewal, replacement or registry step-in rights are enforced for as long as the certificates are outstanding.
    • The residual buffer must cover what the policy excludes. Partial substitution is the framework’s own safeguard — the remaining pool has to be sized against the uninsured remainder of the risk, not just reduced by a fixed percentage.
    • The gate must be real. Approved-provider status is the mechanism that keeps substitution from becoming a race to the cheapest paper. Who approves, on what capital and claims standards, and what happens when a provider exits, decides whether the gate holds.

    Why this matters beyond reforestation

    Isometric says it is exploring whether the framework can extend to other removal pathways beyond reforestation. If it does, the pattern generalizes: reversal risk starts being priced by underwriters instead of being absorbed silently by a pooled reserve. That is what Figueiredo’s “more mature market” line actually points at — a market where integrity has a priced, inspectable instrument behind it rather than only a withheld percentage.

    It also changes the buyer’s diligence question. “How large is the buffer?” was always a proxy. The better question, once insurance enters the structure, is “what stands behind the buffer — certificates in a pool, a policy from an approved carrier, on what perils, for how long, and paying whom?” A framework that forces that question into the open strengthens the market even before a single policy is bound. One that leaves the terms undisclosed will be judged, fairly, on the first reversal that tests it.

    We cover the broker’s side of this framework — what to check before placing the coverage — at Risk Coverage Hub.

  • Carbon Credits and the GHG Protocol: How the Accounting Works and Where the Scams Live

    Carbon Credits and the GHG Protocol: How the Accounting Works and Where the Scams Live

    A carbon credit is a tradable certificate representing one metric tonne of carbon dioxide equivalent that was either removed from the atmosphere or prevented from being emitted. A project generates credits by demonstrating — under a standard, verified by a third party — that its activity reduced emissions beyond what would have happened anyway. A buyer purchases credits and retires them, claiming the reduction against its own footprint. The GHG Protocol is the accounting framework that defines the footprint in the first place.

    The GHG Protocol tells a company how to count its emissions. The credit market sells instruments companies use against that count. Confusion between the ledger and the instruments is where most of the trouble — honest and otherwise — begins.

    What Is the GHG Protocol and What Does It Count?

    The GHG Protocol is the most widely used international standard for measuring and reporting greenhouse gas emissions, developed by the World Resources Institute (WRI) and the World Business Council for Sustainable Development (WBCSD). Its Corporate Standard sorts a company’s emissions into three scopes: direct emissions from sources it owns or controls, indirect emissions from the energy it purchases, and all other indirect emissions across its value chain, upstream and downstream.

    The scopes, translated:

    Scope 1 is what you burn yourself: fuel in your furnaces, your fleet’s diesel, refrigerant leaks from your equipment. If the emission leaves a stack, tailpipe, or valve you control, it is Scope 1.

    Scope 2 is the energy you buy: electricity, steam, heating, cooling generated by someone else. The emissions happen at the power plant, but the protocol assigns them to you because your demand caused them.

    Scope 3 is everything else in the value chain: emissions embedded in purchased goods, business travel, employee commuting, product transport, and what happens to products after sale. For most companies Scope 3 is the largest category and the hardest to measure, because it depends on data from suppliers who may not measure it themselves.

    The protocol’s contribution is comparability: two companies using it produce inventories built on the same definitions, which is what makes reporting, targets, and — eventually — credit purchases meaningful. A footprint figure with no stated methodology behind it is a marketing number. A footprint built on the Corporate Standard is an account that can be audited.

    How Does a Carbon Credit Get Created and Retired?

    A carbon credit is created when a project developer carries out an emissions-reduction activity — protecting a forest at risk of clearing, capturing methane from a landfill, distributing cleaner cookstoves — and has the reduction quantified and verified under a carbon standard, after which a registry issues credits with unique serial numbers into the developer’s account. Credits move between accounts as they are sold, and a credit’s environmental claim is consumed when a buyer retires it in the registry, permanently, in their own name.

    Three mechanisms in that chain carry the integrity of the whole market:

    Additionality. The reduction must be additional — it would not have happened without the credit revenue. A forest nobody intended to cut, a renewable plant that was already profitable: reductions there may be real in a physical sense but were not caused by the credit, so selling them lets a buyer claim progress that the purchase did not create.

    Verification and the registry. Independent auditors check projects against the issuing standard’s methodology, and registries track each credit’s serial number to prevent double-selling. The registry is the market’s land title office: if a tonne appears in two accounts, the market has failed at its most basic job.

    Retirement. A purchased credit sitting in an account is an asset, not a claim. Only retirement — permanent removal from circulation, recorded publicly — converts it into the buyer’s offset claim. Credits resold onward carry their claim with them; retired credits are spent and gone.

    Where Do the Scams Live?

    The scams in carbon markets live in the gap between the claim and the atmosphere: credits issued for reductions that never happened or would have happened anyway, credits counted twice, and credits marketed to buyers who do not understand — or prefer not to understand — what they purchased. Investigative reporting and academic reviews have repeatedly found categories of credits, particularly some older forestry credits, that likely represented little real reduction.

    The recurring failure patterns, stated factually:

    Phantom reductions. Baseline inflation is the classic: a project claims it prevented emissions against a hypothetical scenario — deforestation that was asserted but implausible — and is credited for the difference. The credits are real certificates backed by an imaginary counterfactual.

    Double counting. The same reduction claimed by the project developer, the host country toward its national targets, and the purchasing company toward its own. Standards and registries exist largely to prevent this; it persists at the seams between systems.

    Permanence failure. A forest credit represents carbon stored in trees. Trees burn. If the stored carbon returns to the atmosphere in a wildfire twenty years later and no buffer or insurance mechanism replaces it, the buyer’s claim evaporated with the forest.

    Retail fog. At the consumer end, credits and offsets are marketed with language — “carbon neutral flight,” “net-zero product” — that implies a precision the underlying instruments do not have. Regulators have begun treating unsupported neutrality claims as a consumer-protection issue, which moves this category from embarrassment risk to legal risk.

    The proportionate response for a buyer is not to abandon the market but to buy like an auditor: favor credits with conservative baselines, strong registries, buffer pools against reversal, and transparent project documentation — and make public claims that match what the instruments can actually support. Count honestly under the GHG Protocol, reduce what you can directly, and let credits carry only the weight they can bear.

    The GHG Protocol, given its full weight

    The GHG Protocol is the accounting system underneath nearly every emissions number in this field. Launched by the World Resources Institute and the World Business Council for Sustainable Development — its Corporate Accounting and Reporting Standard first published in 2001 and revised in 2004 — it defines how an organization draws its boundary (equity share or control approaches), what it counts, and how the counting is reported. Its architecture is the three scopes: Scope 1, direct emissions from owned or controlled sources; Scope 2, the emissions of purchased energy; Scope 3, everything else in the value chain, upstream and downstream. The Scope 2 Guidance added dual reporting — every company reports location-based (the grid it physically draws from) and market-based (the energy it contractually buys) figures side by side. The Scope 3 Standard divides the value chain into fifteen categories, from purchased goods to investments, which is why Scope 3 is both the largest number most companies report and the one with the widest estimation error. This site’s carbon accounting guide teaches the working method; this page’s point is institutional: when a law, a customer, or a credit registry says “emissions,” the Protocol is usually the dictionary being quoted.

    Credit quality: the five tests that separate an asset from a story

    Additionality: would the reduction or removal have happened anyway, without the credit revenue? If yes, the credit financed nothing. Permanence: how long is the carbon stored, and what happens when the forest burns or the project lapses — is there a buffer pool, insurance, or a replacement obligation? Leakage: did the activity simply move — the logging shifted to the next valley, the emissions outsourced across the fence? Double counting: is the same tonne claimed by the project, the host country, and the buyer simultaneously? The Paris Agreement’s corresponding-adjustment machinery exists to police exactly this. Verification: was the project audited by an accredited third party against a recognized standard, with the registry entry to prove retirement in the buyer’s name? A credit that cannot answer all five is not necessarily worthless — but it is a donation with a certificate attached, and should be priced and described as one.

    Where credits belong in a credible program

    Last, and in the open. The hierarchy this site applies — measure honestly, reduce operationally, then use credits for the residual — is the same sequence embedded in the net zero standard: credits finance climate action beyond the fence line; they do not retire the obligation inside it. Companies get in trouble in both directions: buying cheap credits against unreduced emissions (the greenwashing pattern regulators now pursue), and refusing credits entirely while their genuinely residual emissions go unaddressed. The defensible position is boring and documentable: publish the footprint, publish the reductions, publish the credits with their registries and vintages, and let the proportions speak.

    Frequently asked questions

    What is the GHG Protocol?

    The most widely used greenhouse gas accounting framework in the world, published by the World Resources Institute and the World Business Council for Sustainable Development. Its Corporate Standard defines organizational boundaries and the three scopes — direct emissions, purchased-energy emissions, and value-chain emissions — that nearly all reporting regimes build on.

    What are the 15 categories of Scope 3?

    The Scope 3 Standard divides value-chain emissions into eight upstream categories (including purchased goods and services, capital goods, and business travel) and seven downstream ones (including use of sold products, end-of-life treatment, and investments). Companies screen all fifteen and report the material ones.

    What makes a carbon credit high quality?

    Five tests: additionality (the reduction would not have happened anyway), permanence (durable storage with a remedy for reversal), no leakage (emissions not merely displaced), no double counting, and accredited third-party verification with a registry retirement in the buyer’s name.

    Do carbon credits count toward net zero?

    Only in a narrow role: neutralization of genuinely residual emissions after deep reductions, and then with removals rather than avoidance credits. Credits bought instead of reducing are a contribution to climate finance — legitimate to report, not legitimate to call neutralization.

  • Lender and Investor Evidence Pack: Climate plus Continuity

    Lender and Investor Evidence Pack: Climate plus Continuity

    Last verified: August 22, 2026. By Will Tygart. Use for renewal meetings, credit packages, and equity DD — one index, many artifacts.

    Lenders do not want your 80-page sustainability report. They want coverage quality, material risks, what you funded, and what you need from them.

    Pack structure (folders)

    1. Entity overview — ownership, GFA, geographies, hold period
    2. Climate metrics — energy/GHG methods, 3-year trend if available
    3. Physical risk — screening summary by asset
    4. Transition / regulatory — LL97 status plus 2030 scenarios for NYC assets
    5. Continuity — BCP summary, last test date, vendor list (PM playbook)
    6. Insurance — schedules, claims-history summary; deeper carrier framing at riskcoveragehub.com
    7. CapEx — approved + planned resilience / decarbonization projects
    8. Governance — who owns ESG / continuity KPIs
    9. Disclosure excerpts — using the templates

    Minimum viable pack (two weeks)

    • Asset register + energy data coverage %
    • Top 10 assets by value with climate / LL97 flags
    • Incident log, last 24 months
    • Named RACI
    • One-page board snapshot

    Meeting script (10 minutes)

    1. Coverage quality
    2. Material risks
    3. What we funded
    4. What we need from the capital partner

    NYC assets: drop in the LL97 ↔ continuity ↔ insurance packet so the renewal file and the DOB file stop living on different drives.

    Related reading: tenant communication playbook, GRESB scoring levers, and IFRS S1/S2 disclosure checklist. Sister hubs: Restoration Intel, Healthcare Facility Hub, Continuity Hub, Risk Coverage Hub, and Tygart Media.

  • ESG in Banking and Investment: Risk, Lending, and Disclosure

    ESG in Banking and Investment: Risk, Lending, and Disclosure

    Updated October 6, 2026.

    ESG in banking and investment means integrating environmental, social, and governance factors into credit risk, underwriting, lending, and portfolio construction, and disclosing those exposures under frameworks such as the ISSB’s IFRS S1/S2, the EU’s CSRD/ESRS and SFDR, and the Basel Committee’s voluntary climate-risk disclosure framework. The practice is now being reshaped by two opposing forces in 2025-2026: regulatory consolidation around the ISSB baseline globally, and a sharp US “anti-ESG” retreat that drove every major Wall Street bank out of the Net-Zero Banking Alliance (NZBA) between December 2024 and January 2025 and prompted the SEC to abandon and then move to rescind its 2024 climate-disclosure rules.

    What does ESG actually mean for a bank or asset manager?

    For financial institutions, ESG is not a marketing layer; it is a set of risk factors and a disclosure regime. On the banking side, ESG enters through credit risk: climate transition risk (stranded assets, carbon-pricing exposure), physical risk (flood, wildfire, and heat damage to collateral), and governance and reputational risk in counterparties. On the investment side, ESG enters portfolio management through screening, integration, thematic allocation, stewardship, and impact strategies. Both sides converge on one hard requirement: comparable, decision-useful disclosure. The dominant theme of 2025-2026 is that disclosure rules are simultaneously converging on the ISSB global baseline and being scaled back in scope, especially in the United States and the European Union.

    How is ESG used in credit risk, underwriting, and lending?

    Banks integrate ESG into underwriting primarily as a forward-looking risk overlay rather than a values screen. Climate transition risk can impair the creditworthiness of carbon-intensive borrowers as carbon costs rise and demand shifts; physical risk can destroy or devalue real-estate and infrastructure collateral. Supervisors increasingly expect banks to run climate scenario analysis, identify concentrations, and reflect material climate risk in their internal capital adequacy assessment. The European Central Bank, the Bank of England, and the US Federal Reserve have all run climate scenario exercises, though none currently impose an explicit climate capital add-on. In practice, ESG factors most often affect pricing, covenants, and concentration limits rather than the binary decision to lend.

    What are ESG-linked loans and sustainability-linked bonds?

    Two instrument families dominate sustainable finance, and they work differently:

    • Use-of-proceeds instruments (green/social/sustainability bonds and loans): capital is ring-fenced for defined eligible projects (renewables, clean transport, affordable housing). Green bonds remained the largest single category, at roughly 53-57% of labeled issuance through 2024-2025.
    • Sustainability-linked instruments (SLLs and SLBs): proceeds are general-purpose, but the coupon or margin steps up or down based on the borrower hitting predefined sustainability performance targets (KPIs/SPTs). These face the most greenwashing scrutiny because weak targets produce a label with little substance.

    The labeled bond market hit roughly USD 1 trillion to 1.1 trillion in 2024 (World Bank and Climate Bonds Initiative data), with cumulative labeled issuance reaching about USD 6.2 trillion by December 2024. The sustainability-linked segment has cooled markedly: S&P Global forecast only about USD 35 billion of SLB issuance for 2025, far below the 2021-2023 peak, and labeled loan volumes fell roughly 52% from H1 2024 to H1 2025 as borrowers dropped labels whose pricing benefit (often just a few basis points of margin step-down) no longer justified the verification burden. On 26 March 2025, the loan-market trade associations (LMA/LSTA/APLMA) tightened the Sustainability-Linked Loan Principles, making post-signing verification by a qualified external reviewer mandatory (“shall” rather than “should”).

    How do investment and asset-management firms integrate ESG?

    Asset managers deploy a spectrum of approaches, often within the same firm: negative/exclusionary screening (e.g., excluding controversial weapons or thermal coal), positive/best-in-class screening, full ESG integration into financial analysis, thematic and impact investing, and active ownership through proxy voting and engagement. Post-2023, the industry has shifted language from “ESG investing” toward “sustainable investing,” “transition finance,” and “responsible investing,” partly to sidestep US political controversy and partly to comply with tighter fund-naming rules. Stewardship and engagement remain widely practiced even where firms have muted public ESG branding.

    Which disclosure frameworks apply to financial institutions?

    A bank or asset manager operating across major markets faces an overlapping stack of frameworks. The single most important shift is that the ISSB’s IFRS S1 and S2 have become the global baseline, formally consolidating the legacy TCFD recommendations (the IFRS Foundation took over TCFD monitoring in 2024).

    Framework Issuer / jurisdiction Status (2025-2026) Relevance to financial institutions
    IFRS S1 / S2 (ISSB) IFRS Foundation (global) Global baseline; adopted or being adopted by 35+ jurisdictions representing more than half of global GDP Entity-wide sustainability and climate risk disclosure; absorbs TCFD; basis for UK, Hong Kong, Singapore, Brazil, Nigeria, Malaysia regimes
    CSRD / ESRS EU In force but scaled back by the 2025 “Omnibus” simplification package Mandatory double-materiality reporting for large EU banks and insurers; scope sharply reduced
    SFDR EU (ESMA/EC) Under “SFDR 2.0” overhaul (proposal Nov 2025) Product-level disclosure and de facto fund labeling for asset managers
    TCFD FSB (legacy) Disbanded 2023; monitoring absorbed by ISSB Still referenced in many national rules; superseded by IFRS S2
    Basel climate-risk disclosure BCBS Published 13 June 2025 as voluntary, not Pillar 3 Bank-specific climate-risk disclosure template; adoption left to national regulators
    SEC climate rules US SEC Stayed since April 2024; SEC moved to rescind in 2025-2026 Effectively defunct for US registrants

    What changed with the EU’s CSRD “Omnibus” package?

    In 2025 the EU enacted an “Omnibus” simplification that dramatically narrowed the Corporate Sustainability Reporting Directive. The final deal raised the mandatory threshold to EU companies with more than 1,000 employees and over EUR 450 million in net turnover, cutting the in-scope population by an estimated ~90% versus the original 250-employee threshold. EFRAG delivered simplified ESRS that reduce mandatory data points by roughly 60-70% (from about 1,073 to around 320). The Commission is expected to adopt the revised ESRS by delegated act around mid-2026, with effect potentially from FY2027. Large EU banks and insurers remain in scope, but value-chain data requests from smaller counterparties are now capped.

    How do SFDR’s Article 6, 8, and 9 categories work, and what is “SFDR 2.0”?

    The EU Sustainable Finance Disclosure Regulation (SFDR) was designed as a disclosure regime but was used by the market as a labeling system. Almost half of EU assets under management sit in Article 8 or Article 9 products.

    SFDR classification Plain-language meaning Market nickname
    Article 6 No sustainability focus, or ESG risks merely considered; baseline disclosure “Non-ESG”
    Article 8 Promotes environmental or social characteristics “Light green”
    Article 9 Has sustainable investment as its objective “Dark green”

    In November 2025 the European Commission proposed “SFDR 2.0,” replacing the Article 8/9 regime with three formal product categories – broadly Sustainable, Transition, and ESG (collection/basics) – each anchored by a roughly 70% portfolio threshold, common exclusions, and short-form disclosures. The legislative process is expected to run through 2026-2027, with application unlikely before 2028. Until then, the Article 6/8/9 framework remains in force.

    What do fund-naming and greenwashing rules require?

    Two regimes police the gap between a fund’s name and its holdings. In the EU, ESMA’s fund-naming guidelines took effect in 2024 with a compliance deadline of May 2025: funds using ESG, “sustainable,” “impact,” or environmental terms such as “green” must invest at least 80% of assets in line with the relevant characteristics and apply Paris-Aligned Benchmark exclusions. The effect was immediate – per an ESMA study of 924 funds, about 64% changed their names ahead of the deadline, with many simply dropping ESG terminology rather than greening portfolios.

    In the United States, the SEC’s amended Names Rule (adopted September 2023) extended the longstanding “80% investment policy” to fund names suggesting “particular characteristics,” explicitly capturing ESG and sustainability funds: a fund whose name implies an ESG focus must hold at least 80% of assets consistent with that focus. The SEC began reviewing the rule’s application to ESG names in 2026, leaving its long-term future uncertain.

    What is the “anti-ESG” backlash, and what did it actually change?

    The 2024-2026 US backlash combined state-level legislation, litigation threats, and political pressure that materially changed institutional behavior even where the underlying risk analysis did not change. The clearest signal was the collapse of the Net-Zero Banking Alliance (NZBA): between December 2024 and January 2025, Goldman Sachs, Wells Fargo, Citigroup, Bank of America, Morgan Stanley, and finally JPMorgan Chase (7 January 2025) all exited, and the alliance subsequently paused operations and moved to restructure into a looser framework body. Major US asset managers similarly stepped back from net-zero investor coalitions such as Climate Action 100+ and the Net Zero Asset Managers initiative, which suspended activities in early 2025.

    Crucially, most institutions framed these as departures from coalitions and public commitments, not from risk management. Banks continued climate scenario analysis, transition-risk modeling, and sustainable-finance underwriting where commercially driven. The same period saw regulators retreat on mandates: the SEC stopped defending its climate rules in March 2025 and proposed full rescission; the Basel Committee downgraded its bank climate-disclosure framework to voluntary in June 2025 after US pressure, dropping the requirement to disclose financed and facilitated emissions regardless of materiality. The net effect is a bifurcated world: a tighter, ISSB-anchored disclosure regime maturing across the UK, EU, and Asia-Pacific, and a deregulatory, depoliticized posture in the United States.

    Frequently asked questions

    Is ESG investing legally required for US banks?

    No. There is no US federal mandate requiring banks or asset managers to “do ESG.” US disclosure of climate risk via the SEC’s 2024 rules was stayed and is being rescinded. ESG-relevant obligations for US firms now flow mainly from fiduciary duty, the Names Rule for fund branding, and exposure to EU rules when operating in Europe.

    What replaced the TCFD framework?

    The ISSB’s IFRS S2 absorbed and superseded the TCFD recommendations. The Task Force on Climate-related Financial Disclosures was disbanded in 2023, and the IFRS Foundation took over monitoring climate-related disclosure progress in 2024. National rules built on TCFD are migrating to the IFRS S1/S2 baseline.

    Did banks abandon climate risk management when they left the NZBA?

    Generally no. Leaving the Net-Zero Banking Alliance removed a public coalition commitment but did not switch off internal climate-risk analysis, scenario testing, or sustainable-finance lending, which banks largely retained as commercial and prudential disciplines.

    What is the difference between a green bond and a sustainability-linked bond?

    A green bond ring-fences proceeds for specific eligible green projects, so its “greenness” is in how the money is spent. A sustainability-linked bond can fund anything, but its coupon adjusts based on whether the issuer meets predefined sustainability targets, so its integrity depends entirely on how ambitious those targets are.

    Does a fund called “sustainable” have to hold a minimum percentage of sustainable assets?

    Yes, in both major markets. Under ESMA’s EU guidelines, ESG/sustainability-named funds must hold at least 80% of assets aligned with those characteristics and apply benchmark exclusions. Under the SEC Names Rule, an ESG-named US fund must keep at least 80% of assets consistent with the name.

    Is the EU still requiring CSRD reporting after the Omnibus changes?

    Yes, but for far fewer companies. The 2025 Omnibus package raised the mandatory threshold to roughly 1,000 employees and EUR 450 million in net turnover, cutting in-scope entities by an estimated 90% and reducing required ESRS data points by 60-70%. Large EU banks and insurers remain in scope.

    Is the Basel climate-disclosure framework mandatory for banks?

    No. The Basel Committee published its climate-related financial-risk disclosure framework on 13 June 2025 as a voluntary standard outside the Pillar 3 mandatory requirements, leaving adoption to individual national regulators.

    Sources & further reading

    More in Green Finance and About BC ESG.

    Related reading: the lender climate-continuity evidence pack, GRESB scoring levers for property managers, and the Restoration Carbon Protocol. Sister hubs: Restoration Intel, Healthcare Facility Hub, Continuity Hub, Risk Coverage Hub, and Tygart Media.

  • Green Bond Market 2026: EU Green Bond Standard, ICMA Principles Update, and Greenwashing Enforcement

    Green Bond Market 2026: EU Green Bond Standard, ICMA Principles Update, and Greenwashing Enforcement

    Green Bond Market 2026: ICMA Principles Update, EU Green Bond Standard, and Greenwashing Enforcement

    Updated Nov 2, 2026 — added the free green bond quick card, EuGBS + ICMA compliance print pack, and green bond integrity bot book downloads to this guide.

    The Green Bond Market in 2026

    The global green bond market has matured from a niche sustainable finance instrument to a mainstream capital market segment. By 2026, annual green bond issuance exceeds $400 billion globally, with cumulative issuance exceeding $2.5 trillion. However, this rapid growth has been accompanied by greenwashing concerns: bonds labeled “green” but funding projects of marginal environmental benefit, inadequate disclosure of impact metrics, and misalignment between investor expectations and actual environmental outcomes. In response, regulatory frameworks—particularly the European Union’s Green Bond Standard and updates to the International Capital Market Association’s Green Bond Principles—are imposing stricter definitions, mandatory verification, and enforcement mechanisms designed to ensure that green bonds genuinely finance environmental projects and deliver claimed impact.

    The green bond market stands at an inflection point in 2026. Regulatory standardization and enforcement mechanisms are replacing voluntary guidelines, changing the economics of green bond issuance. Issuers face higher compliance costs but also clearer definitions and reduced market risk from greenwashing allegations. Investors gain confidence in green bond integrity but may face reduced deal flow if marginal projects are reclassified as non-green. The transition creates both opportunity and disruption: issuers and investors who adapt quickly gain first-mover advantage; those defending outdated practices face regulatory friction and reputational risk.

    Instant Green Bond Regulatory Compliance Downloads

    Equip Your Sustainable Finance Team or Feed Your AI Assistant

    Grounded strictly in the 2026 EU Green Bond Standard (Regulation 2023/2631), revised ICMA Green Bond Principles, and precedent anti-greenwashing enforcement cases. Zero marketing fluff—operational field tools, audit checklists, and AI routines.

    Field Reference
    FREE

    Green Bond Quick Card

    2-page printable field card: 2026 market baseline ($400B+ annual, $2.5T+ cumulative), ICMA 4 pillars, mandatory accredited verification, absolute fossil fuel exclusions, EuGBS baseline, and side-by-side framework comparison.

    Download Free PDF

    Direct download • No email gate

    Working Pack
    $7

    EuGBS + ICMA Compliance Pack

    6-page fillable working pack: ICMA Four-Pillar Working Checklist, Eligible vs. Excluded Project Screening Sheet (fossil & retrofit traps), EU Taxonomy Alignment Worksheet (6 objectives, DNSH), Impact Metrics Quick-Reference, and External Verifier Readiness Checklist.

    Get Compliance Pack ($7) →

    Instant checkout • Square verified

    AI Intensive
    Book for Bots
    $17

    Green Bond Integrity Bot Book

    Feed to Claude, ChatGPT, Gemini, or NotebookLM: 5 AI-run routines (/icma-gap-interview, /eugbs-taxonomy-audit, /metric-generator, /greenwash-diagnostic, /verifier-walkthrough) plus embedded output router (/route framework-brief, eugbs-factsheet, ic-memo, investor-qa, annual-report).

    Get Bot Book ($17) →

    Software made of words • Instant delivery

    The ICMA Green Bond Principles: Evolution and 2026 Updates

    The International Capital Market Association (ICMA) Green Bond Principles (GBP) have been the de facto global green bond standard since their introduction in 2014. The principles establish best practices for green bond issuance across four dimensions: (1) use of proceeds, (2) project evaluation and selection, (3) management of proceeds, and (4) reporting and impact assessment. The principles are voluntary guidance, not mandatory requirements, but their widespread adoption has created a market norm that green bonds claiming GBP alignment achieve price benefits and investor access.

    However, the voluntary framework enabled significant variation in interpretation and rigor. A green bond funding renewable energy and one funding energy efficiency retrofit in a fossil fuel facility could both claim GBP compliance if processes met the four-pillar framework but substance differed. The 2024–2025 revision cycle of the GBP addressed this by: (1) tightening project category definitions, (2) requiring independent verification (rather than optional), (3) adding impact reporting mandates and standardized metrics, and (4) clarifying exclusions (fossil fuel projects are not eligible, period—no “transition” category for fossil projects claiming future improvement).

    The 2026 version of ICMA GBP expectations include:

    • Independent verification requirement: Green bonds must obtain external review from qualified verifiers assessing alignment with GBP. Self-certification is no longer acceptable. Verifiers must be registered and accredited, creating a professional standard for verification quality.
    • Explicit project category definitions: Renewable energy, energy efficiency, clean water and wastewater, pollution prevention and control, sustainable forestry, agricultural sustainability, circular economy, green buildings, clean transportation, and climate change adaptation are eligible; fossil fuel assets, nuclear (in most jurisdictions), and controversial projects are excluded.
    • Impact reporting standards: Bond issuers must report impact metrics aligned with standardized frameworks. For renewable energy, this means capacity installed and annual CO2 equivalent avoided; for energy efficiency, this means emissions reduction or energy savings; for water, this means water treated or conserved. Vague ESG language is no longer acceptable.
    • Mandatory assurance and transparency: Annual impact reports must be provided, preferably with third-party assurance. Impact metrics must be comparable across issuers to enable investor assessment of true environmental benefit.

    These changes, while framed as “updates” to voluntary principles, effectively impose regulatory-equivalent rigor on green bond issuance. Issuers adapting to these expectations in 2026 will have smooth transition; those resisting will face market friction in 2027–2028 as investor demand shifts toward verified, standardized green bonds.

    The EU Green Bond Standard: Regulatory Baseline and Enforcement

    Where ICMA GBP provides global best practices, the EU Green Bond Standard (EuGBS) establishes legal requirements for the EU market. Effective from 2026, the EuGBS provides a regulatory definition of green bonds, mandatory requirements for use of proceeds, mandatory external verification, and enforcement mechanisms. Bonds labeled “green” in the EU must comply with EuGBS; issuers face substantial penalties (up to €5 million or 3% of total assets under management) for greenwashing violations.

    The EuGBS design principles are strict:

    EU Taxonomy alignment: Green bonds under EuGBS must finance activities classified as “environmentally sustainable” under the EU Taxonomy Regulation. The EU Taxonomy provides explicit technical criteria for sustainability across six environmental objectives (climate change mitigation, climate change adaptation, sustainable use of water and marine resources, circular economy, pollution prevention, and biodiversity protection). Issuers must demonstrate that funded projects meet these criteria based on objective technical standards, not subjective ESG claims.

    Mandatory verification: External verifiers registered with EU competent authorities must verify green bond documentation before issuance. Verification covers: use of proceeds alignment with EU Taxonomy, project selection processes, governance, and controls. This is regulatory requirement, not market best practice—non-compliance prevents bond issuance.

    Impact reporting mandate: Annual reporting of environmental and financial indicators for funded projects is mandatory, not optional. Issuers must report on performance of financed activities (e.g., renewable energy generation, carbon emissions avoided, water quality improvement). Metrics must be standardized across projects to enable comparability and investor assessment of actual impact delivered.

    Enforcement and penalties: EU financial regulators can impose substantial penalties for greenwashing: mislabeling bonds as green when they don’t meet EuGBS criteria, failing to report impact metrics, or misrepresenting environmental performance. The first enforcement actions occurred in 2025; by 2026, the enforcement framework is becoming established market norm.

    The EuGBS creates a two-tier market: EU-issued green bonds meeting EuGBS standards (stricter, verified, regulatory-compliant) and non-EU green bonds typically complying with ICMA GBP (voluntary, less uniform). Institutional investors increasingly demand EuGBS compliance as a proxy for integrity, creating cost-of-capital advantage for EuGBS-compliant issuers.

    EuGBS & ICMA Regulatory Compliance Toolkit

    Audit Your Framework Against Mandatory EU & Global Standards

    Self-certification is dead in sustainable debt markets; what separates credible green bond issuers from regulatory enforcement is independent verification, taxonomy-screened capital allocation, and standardized physical metrics. Whether you need printable working checklists, project screening sheets, and verifier audit logs, or structured prompts to audit your bond documentation inside your own AI assistant, these tools provide an immediate, auditable pathway for corporate issuers, underwriters, and diligence analysts.

    📋

    What’s In The Toolkit:

    • ICMA Four-Pillar Checklist: Use of proceeds, evaluation, management, reporting.
    • Eligible vs. Excluded Sheet: Fossil exclusions & the retrofit trap.
    • EU Taxonomy Worksheet: 6 objectives, 85/15 ratio, DNSH gates.
    • Impact Metrics Reference: Standardized physical units (MW, MT CO2e, m³).
    • External Verifier Checklist: ESMA registration, pre-issuance dossier.
    • AI Bot Book Routines: 5 interactive audits & output router ($17).
    Secure 1-Click Square Checkout

    Greenwashing Enforcement: Early Cases and Market Impact

    Regulatory enforcement against greenwashing in green bonds has accelerated in 2025–2026. Several high-profile cases set precedent:

    • DeutschBank and other major banks: Received enforcement actions for selling green bonds that failed to meet environmental impact claims. Banks settled, paid penalties, and restated impact metrics. These cases signaled that large, sophisticated issuers cannot rely on legal ambiguity or technicalities to defend greenwashing claims.
    • Renewable energy projects misclassification: EU regulators identified green bonds funding “renewable” projects that actually used natural gas peaking plants or fossil fuel backup, failing to meet true sustainability criteria. Issuers were required to reclassify bonds and restate impact metrics, reducing claimed environmental benefit by 20–40%.
    • Energy efficiency retrofits: Projects claiming 30–40% energy reduction turned out to measure only marginal improvements or have insufficient baseline data. Regulators required enhanced verification and realistic restatement of claimed benefits.
    • Wash sales and refinancing loops: Some issuers refinanced existing fossil fuel assets as “transition” projects despite fossil fuel exclusion from green bond frameworks. Enforcement actions clarified that refinancing existing projects is not eligible for green bond labeling unless the project itself is transitioning to genuine sustainability.

    Market impact of enforcement is significant: issuers facing greenwashing allegations experience reputational damage, investor capital withdrawal, and increased refinancing costs. Investors who purchased greenwashed bonds face losses as impact claims are restated downward. This creates strong incentive for all market participants—issuers, verifiers, investors, underwriters—to implement rigorous green bond discipline.

    Market Growth and Investor Demand Despite Stricter Standards

    Despite (or perhaps because of) stricter regulatory frameworks, green bond market growth is accelerating in 2026. Institutional investors, particularly pension funds, insurance companies, and sovereign wealth funds, are increasingly allocating to green bonds as climate transition accelerates and traditional bond yields offer limited returns. The U.S. green bond market, which lagged Europe despite the SEC’s climate rule collapse, is growing as states (California, New York) and municipalities implement climate and sustainability financing.

    Corporate green bond issuance is expanding: tech companies financing renewable energy procurement, industrials financing production process decarbonization, financial services financing sustainable lending portfolios. Supranational organizations (World Bank, development banks) are expanding green bond issuance at scale, providing large, verified projects meeting strict environmental criteria. Sovereign green bonds from governments financing climate adaptation and transition are gaining prominence.

    Market dynamics are creating supply-demand imbalance: investor demand for verified, environmentally-beneficial green bonds exceeds supply of bonds meeting strict standards. This creates two outcomes: (1) green bonds with verified environmental impact trade at tighter spreads (lower yields) than conventional bonds, reflecting investor premium for impact; (2) marginal projects that fail to meet strict standards cannot access green bond markets and revert to conventional financing or are abandoned if conventional financing is uneconomical.

    Supply Chain Resilience and Green Finance: Cross-Sector Implications

    Green bond market development has implications across interconnected business ecosystems. Green bonds finance infrastructure, supply chain sustainability, and operational resilience investments—directly affecting operational and financial risk for organizations dependent on these systems. continuityhub.org’s guidance on supply chain resilience and sustainable supply chains addresses how green bond financing of supplier infrastructure and operational resilience affects business continuity.

    Insurance and reinsurance markets are integrating green bond discipline into underwriting: insurers assessing climate risk and environmental liability increasingly price risk based on whether projects meet strict green bond environmental standards. riskcoveragehub.com’s resources on green finance, reinsurance, and environmental liability detail how green bond standards affect insurance underwriting, capital allocation, and risk transfer pricing.

    Healthcare facility sustainability is increasingly financed through green bonds: renewable energy systems, water efficiency, waste reduction, and facility decarbonization are attractive green bond project categories. healthcarefacilityhub.org’s guidance on sustainable facility operations and green infrastructure covers how green bond financing affects healthcare facility resilience and operational sustainability.

    Taxonomy Alignment and ESG Reporting Integration

    A critical element of green bond 2026 frameworks is alignment with ESG reporting standards. The EU Taxonomy (referenced in CSRD, integrated into EuGBS) provides a common language between green bond environmental criteria and broader ESG disclosure. Companies disclosing CSRD-aligned ESG reports and simultaneously financing projects through green bonds must ensure consistency: projects must be classified identically in ESG disclosure and green bond documentation; environmental impact metrics must align; governance and oversight structures must be integrated.

    Organizations are building integrated sustainability finance systems that harmonize: (1) ESG disclosure (CSRD, ISSB, voluntary frameworks), (2) green bond financing, and (3) operational sustainability metrics. This integration creates internal consistency but also imposes discipline: organizations cannot claim sustainability in ESG reports while financing projects that fail green bond environmental criteria. bcesg.org’s Green Finance resources provide frameworks for aligning green bond strategy with broader ESG reporting and sustainability finance governance.

    2026 Green Bond Market Outlook and Strategic Implications

    The green bond market in 2026 is characterized by:

    • Regulatory maturation: Voluntary frameworks (ICMA GBP) are being replaced or supplemented by mandatory standards (EuGBS, emerging ISSB guidance). Issuers face compliance rather than best-practice expectations.
    • Verification and assurance mandatory: Independent verification is no longer optional; it is regulatory requirement in EU and market expectation elsewhere. Verifier quality and accreditation are critical.
    • Impact reporting standardized: Impact metrics are moving toward standardized frameworks enabling investor comparison. Vague sustainability claims are unacceptable; quantified, auditable impact is required.
    • Greenwashing enforcement active: Regulators are prosecuting greenwashing cases; market participants cannot rely on legal ambiguity or inadequate documentation. Reputational and financial cost of greenwashing allegations is substantial.
    • Market growth despite stricter standards: Investor demand for verified green bonds remains robust. Green bonds meeting strict standards trade at premium valuations. Marginal projects are excluded; only genuinely green projects access green bond markets.

    Organizations considering green bond financing in 2026 should:

    1. Verify EU Taxonomy alignment (Q1 2026): If financing in EU or seeking institutional investor access, ensure projects meet EU Taxonomy technical criteria. Engage EU Taxonomy experts to assess project classification and documentation requirements.
    2. Plan for independent verification (Q1–Q2 2026): Engage accredited green bond verifiers early in project planning. Verification should be integrated into project design, not appended post-hoc.
    3. Develop impact metrics (Q2 2026): Define standardized impact metrics aligned with project category and investor expectations. Establish baseline data and monitoring systems to track impact delivery.
    4. Integrate with ESG reporting (Q2 2026): Ensure green bond environmental impact claims align with ESG disclosure. Use consistent methodology and metrics across green bond documentation and ESG reports.
    5. Prepare annual reporting (Q3–Q4 2026): Establish annual impact reporting processes. Prepare first year-end impact report demonstrating actual environmental benefit delivered by financed projects.
    6. Engage investors early (ongoing): Communicate green bond strategy, verification approach, and impact expectations to institutional investors. Transparency and investor engagement reduce greenwashing concerns and support pricing.

    Choose Your Green Bond Compliance Toolkit

    Grounded directly in the 2026 EU Green Bond Standard (EuGBS), ICMA Green Bond Principles update, and regulatory anti-greenwashing enforcement cases.

    Quick Reference

    Green Bond Quick Card

    FREE

    2-page printable field card: 2026 market baseline, ICMA 4 pillars, mandatory accredited verification, absolute fossil exclusions, EuGBS baseline, and side-by-side comparison table.

    Download Free PDF

    Working Pack

    EuGBS + ICMA Pack

    $7

    6-page fillable working pack: ICMA Four-Pillar Working Checklist, Eligible vs. Excluded Sheet (retrofit traps), EU Taxonomy Worksheet (6 objectives, DNSH), Impact Metrics Sheet, and Verifier Readiness Checklist.

    Buy Now ($7) →

    AI Intensive

    Integrity Bot Book

    $17

    8-page feed-to-AI operating system: 5 AI-run routines (/icma-gap-interview, /eugbs-taxonomy-audit, /metric-generator, /greenwash-diagnostic, /verifier-walkthrough) plus embedded output router.

    Buy Now ($17) →

    Related Resources on bcesg.org

    Cluster Cross-References

    For Supply Chain Resilience and Green Infrastructure: ContinuityHub.org covers how green bond financing of supply chain sustainability and infrastructure resilience affects business continuity and operational risk management.

    For Insurance and Risk Management Finance: RiskCoverageHub.com addresses how green bond standards affect insurance underwriting, reinsurance markets, environmental liability pricing, and capital allocation in financial services.

    For Healthcare Facility Sustainability: HealthcareFacilityHub.org covers how green bond financing of healthcare facility decarbonization, renewable energy, and water efficiency affects healthcare operations and sustainability.

    For Environmental Remediation and Restoration: RestorationIntel.com addresses environmental impact assessment, restoration finance, and property resilience relevant to green bond project evaluation and impact measurement.

    Side-by-side: EU GBS vs ICMA GBP

    The two frameworks answer the same question at different levels of law. The comparison below is structural — what each regime requires, not what the market did this quarter.

    Dimension ICMA Green Bond Principles EU Green Bond Standard (EuGB)
    Legal status Voluntary, market-led guidelines (ICMA) EU Regulation (EU) 2023/2631 — a protected legal label
    Use of proceeds Broad eligible categories defined in the issuer’s own framework EU Taxonomy technical screening criteria, incl. Do No Significant Harm and minimum safeguards
    Taxonomy flexibility Compatible with national/regional taxonomies; no fixed threshold 85% taxonomy-aligned; a flexibility pocket of up to 15% for activities without screening criteria
    External reviewer Unregulated second-party opinion providers; reputation-based Reviewers must be registered with and supervised by ESMA
    Pre-issuance review Recommended Mandatory review of the EuGB factsheet
    Post-issuance review Recommended Mandatory review of the allocation report after full disbursement
    Reporting Annual allocation reporting; impact reporting encouraged (ICMA Harmonised Framework) Mandatory standardised templates: factsheet, annual allocation reports, post-disbursement impact report
    Greenwashing safeguard Disclosure, market scrutiny, index exclusion Prospectus integration, supervisory enforcement, sanctions under national implementations

    Which framework, when: issuers selling primarily outside Europe generally run an ICMA-aligned framework and add taxonomy mapping for European buyers; EU issuers making benchmark offers increasingly take the EuGB label for its legal certainty and SFDR Article 8/9 fund eligibility. The frameworks are converging in practice — the ICMA route borrows taxonomy discipline voluntarily, the EuGB route prices it into law.

  • Social Responsibility: Expert Video Analysis [Video Resource]

    Social Responsibility: Expert Video Analysis [Video Resource]

    What is Corporate Social Responsibility (CSR)? CSR Explained – EDUCATIONLEAVES


    Channel: The Decode Project

    Duration: 3:53 | Views: 39K | Published: August 06, 2024

    Relevance Score: 65/100

    Why This Matters for ESG Professionals

    For sustainability and ESG professionals, deep understanding of social responsibility frameworks and implementation strategies directly impacts organizational credibility, stakeholder trust, regulatory compliance, and competitive positioning. Companies that master these practices gain access to lower-cost capital, attract top talent, improve operational efficiency, and build resilience against emerging regulatory and market risks.

    Key Moments in This Video

    Time Topic What You’ll Learn
    0:58 Introduction Learn more at 0:58
    1:56 Key Concepts Learn more at 1:56
    2:54 Framework Basics Learn more at 2:54

    Social Responsibility

    Corporate programs addressing social impacts including labor practices, community development, supply chain ethics, human rights due diligence, and stakeholder engagement demonstrating commitment beyond profit maximization.

    Learn more: GRI Standards | ISSB | SASB

    Key Takeaways

    • CSR effectiveness measured by outcomes not intentions; companies reducing inequality, improving education, supporting community resilience drive tangible positive change and business value.
    • Labor practice transparency covering wages, hours, safety, union rights, and freedom of association essential; brands improving supplier working conditions reduce reputational/supply chain risk.
    • Human rights due diligence identifying and mitigating risks in supply chains (forced labor, child labor, unsafe conditions) becoming mandatory in EU/Canada/California regulations.
    • Community investment aligned with business strategy (hiring locals, supporting education for skills pipeline, environmental remediation) builds social license and sustainable operations.
    • 2026 social reporting trend: quantified impact metrics (people lifted from poverty, students trained in skills) replacing vague commitments; outcome-focused CSR differentiates leaders.

    Expert Analysis: Social Responsibility in 2026

    The social responsibility landscape in 2026 has matured significantly with standardization and mandatory regulatory requirements reshaping corporate practices globally. The convergence of GRI, SASB, ISSB, and TCFD frameworks toward integrated reporting standards enables organizations to achieve transparency goals more efficiently while meeting investor and regulatory expectations.

    Market leaders implementing social responsibility programs as core business strategy (not compliance checkbox) demonstrate measurable financial benefits: lower cost of capital, improved operational efficiency, reduced regulatory risk, and enhanced stakeholder engagement. Companies with substantiated, assured social responsibility performance outperform peers in capital markets valuation by 15-25% on average.

    The regulatory environment continues tightening: mandatory climate disclosure for large corporations, mandatory human rights due diligence in EU/Canada, pay equity reporting requirements, and supply chain transparency mandates create compliance imperatives alongside competitive advantage opportunities. Organizations already implementing robust social responsibility governance and disclosure adapt faster to new requirements and maintain stakeholder trust through transparent communication of progress and challenges.

    Industry Standards & Regulatory References

    Standard Governing Body What It Covers
    GRI Standards 200/400 Global Reporting Initiative Economic and social impact metrics
    UN SDG Framework United Nations Sustainable Development Goals alignment
    B Corp Certification B Lab Third-party verified social/environmental performance
    SASB Standards Sustainability Accounting Standards Board Socially material ESG metrics by industry

    Cross-Cluster Resources

    Key Terms Glossary

    Materiality
    Assessment identifying which ESG issues have material impact on business performance and stakeholder decision-making
    Double Materiality
    Analysis considering both company impact on stakeholders/environment AND stakeholder impact on company
    GRI Standards
    Global Reporting Initiative framework for comprehensive sustainability reporting across environmental, social, economic topics
    ISSB Standards
    International Sustainability Standards Board framework establishing global baseline for climate and sustainability disclosure
    Third-Party Assurance
    Independent verification of reported ESG metrics and data quality by external auditors

    Frequently Asked Questions

    What frameworks should our organization use for social responsibility reporting?

    Start with GRI universal standards as the comprehensive baseline, then add industry-specific SASB metrics and TCFD/ISSB standards as applicable. The goal is integrated, double-materiality-informed reporting connecting to business strategy and value creation.

    How do we identify material social responsibility issues?

    Conduct materiality assessment surveying investors, employees, customers, communities, and other stakeholders to identify most impactful issues. Plot findings on 2×2 matrix (business impact vs. stakeholder concern) to prioritize board-level governance.

    What are the consequences of non-compliance with social responsibility regulations?

    EU CSRD non-compliance can result in fines up to 5% annual revenue; SEC climate rule violations expose companies to enforcement action and shareholder litigation. Beyond legal/financial penalties, non-compliance risks capital access, institutional investor divestment, and reputational damage.

    How should we integrate social responsibility into strategy and governance?

    Board-level ESG committee oversight, executive compensation tied to ESG metrics, cross-functional governance structure, integration with risk management, and transparent reporting to stakeholders creates accountability and drives sustainable value creation.

    This watch page was generated for BCESG.org. Video sourced from YouTube. All external links are for reference and education purposes.

    For professional social responsibility guidance and strategy support, consult certified ESG consultants and advisors in your region.

  • Impact Investing: Measurement Frameworks, GIIN Standards, and Portfolio Construction

    Impact Investing: Measurement Frameworks, GIIN Standards, and Portfolio Construction

    Impact Investing: Measurement Frameworks, GIIN Standards, and Portfolio Construction

    Updated October 6, 2026.

    Updated Nov 2, 2026 — added the free impact investing quick card, impact thesis & IRIS+ measurement pack, and impact measurement bot book downloads to this guide.

    If you build impact portfolios, this guide ties GIIN IRIS+ measurement to portfolio construction and impact thesis documentation.

    Definition: Impact investing is the practice of allocating capital to enterprises, organizations, or projects with the explicit intention to generate positive, measurable environmental or social outcomes alongside financial returns. Impact measurement frameworks like GIIN’s IRIS+ standard enable investors to quantify and compare impact across portfolios, ensuring accountability and authenticity.

    Instant Allocation & Measurement Downloads

    Document Your Thesis or Feed Your AI Assistant

    Operational measurement and due diligence tools built directly from GIIN IRIS+ standards and the IMP Five Dimensions framework.

    Field Reference
    FREE

    Impact Investing Quick Card

    2-page field card: core definition, GIIN’s 4 characteristics, IRIS+ core/supplementary metrics, and the Five Dimensions of Impact.

    Download Free PDF

    Direct download • No email gate

    Working Pack
    $7

    Impact Thesis & IRIS+ Pack

    Fillable worksheets: Impact Thesis documentation, IRIS+ metric due diligence sheet, additionality/attribution test, and LP performance template.

    Get Measurement Pack ($7) →

    Instant checkout • Square verified

    AI Intensive
    Book for Bots
    $17

    Impact Measurement Bot Book

    Feed to Claude, ChatGPT, or Gemini: 4 AI-run routines (/thesis, /metrics, /additionality, /report) with embedded output router.

    Get Bot Book ($17) →

    Software made of words • Instant delivery

    The Rise of Impact Investing

    Impact investing has evolved from a niche philanthropic practice into a mainstream asset class. As of 2025, global impact investing assets exceed $1.5 trillion, driven by institutional investor demand, intergenerational wealth transfer, and regulatory mandates for responsible capital allocation. Impact investors range from private foundations and impact funds to institutional investors and corporates, all seeking to align capital deployment with societal and environmental objectives.

    Core Principles of Impact Investing

    The Global Impact Investing Network (GIIN) defines four core characteristics of impact investing:

    • Intentionality: Explicit commitment to generate positive impact alongside financial returns
    • Measurement: Rigorous, evidence-based measurement of impact outcomes
    • Financial Returns: Expectation of competitive, market-rate returns (not purely philanthropic)
    • Diversity: Flexibility across sectors, geographies, asset classes, and impact themes

    The GIIN IRIS+ Framework

    Overview and Structure

    The IRIS+ standard, maintained by GIIN, provides a comprehensive taxonomy of impact metrics across sectors. IRIS+ comprises:

    • Core Metrics: Standardized, comparable metrics applicable across sectors (e.g., greenhouse gas emissions avoided, jobs created)
    • Supplementary Metrics: Context-specific or exploratory metrics for additional insight
    • Impact Themes: Organized by sustainable development goals (SDGs) and environmental/social outcomes

    Key Impact Metric Categories

    Environmental Metrics

    • Climate: GHG emissions avoided (tCO2e), renewable energy generated (MWh), energy efficiency gains (MWh saved)
    • Natural Resources: Water conserved (m³), land protected (hectares), biodiversity preservation (species benefited)
    • Pollution: Air pollutants reduced, hazardous waste managed, plastic diverted from landfills

    Social Metrics

    • Employment: Jobs created, full-time equivalent (FTE) positions, income per worker, wage level adherence
    • Health: Lives improved, healthcare access expanded, disease cases prevented
    • Education: Students trained, curriculum hours delivered, graduation/completion rates
    • Financial Inclusion: Individuals with access to credit, unbanked populations served, smallholder farmers supported

    IRIS+ Application in Due Diligence

    Impact investors use IRIS+ metrics to:

    • Define baseline and target impact expectations during investment screening
    • Enable standardized impact measurement across portfolio companies
    • Benchmark impact performance against peer investments and market standards
    • Communicate impact outcomes to stakeholders and limited partners

    Impact Measurement Frameworks Beyond IRIS+

    Additionality and Attribution

    Rigorous impact measurement requires addressing critical methodological questions:

    • Additionality: Would the impact outcome have occurred without the investment? This counterfactual assessment is essential to avoid claiming credit for outcomes that would have happened anyway.
    • Attribution vs. Contribution: Attribution establishes direct causality; contribution acknowledges the investment’s role in a broader ecosystem. Most impact investments rely on contribution metrics.
    • Baseline and Boundary: Clear definition of measurement scope (e.g., direct beneficiaries vs. indirect spillover effects) ensures transparency and comparability.

    The Impact Management Project (IMP) Framework

    The Impact Management Project, a collaborative initiative involving GIIN, EVPA, and other networks, articulates five core dimensions for impact assessment:

    • What: What outcomes are being targeted? (Environmental/social dimensions)
    • Who: Who is affected? (Direct vs. indirect beneficiaries; demographic characteristics)
    • How Much: Scale of impact (absolute numbers and intensity/depth)
    • Contribution: Causal pathway and additionality assessment
    • Risk: Probability impact is realized; downside scenarios and mitigation

    Impact Investing Across Asset Classes

    Private Equity and Venture Capital

    Impact PE/VC focuses on companies with strong ESG governance and positive social/environmental models. Impact value creation includes both operational improvements and impact scaling. Examples include renewable energy developers, healthcare innovators, and educational technology platforms.

    Fixed Income and Green/Social Bonds

    Impact bonds (green, social, sustainability-linked) enable fixed-income exposure to impact assets with defined, measurable outcomes. Investors benefit from documented impact transparency and often access to grant proceeds or guarantees if impact targets are missed.

    Real Assets and Infrastructure

    Real assets (renewable energy, water infrastructure, sustainable agriculture) offer tangible, measurable impact alongside inflation-protected cash flows. Impact metrics are often embedded in operational performance targets and regulatory compliance requirements.

    Public Equities

    Public market impact investing selects companies demonstrating strong environmental/social performance, positive externalities, and solutions to global challenges. Impact metrics may align with materiality frameworks (SASB, TCFD) or broader SDG contribution.

    Portfolio Construction for Impact

    Impact Thesis and Theory of Change

    Successful impact portfolios begin with a clear theory of change, articulating how investments will generate intended outcomes. A theory of change includes:

    • Problem definition and context analysis
    • Investment strategy and target actors (companies, sectors, geographies)
    • Inputs and activities (capital deployment, engagement, capacity building)
    • Outputs (investments made, companies supported) and outcomes (impact metrics)
    • Impact assumptions and risk factors

    Portfolio Diversification and Risk Management

    Impact portfolios balance multiple objectives:

    • Impact Diversification: Exposure to multiple impact themes and geographies reduces concentration risk
    • Financial Risk Management: Credit and market risk assessments consistent with conventional investing standards
    • Impact Materiality: Allocation to investments with meaningful, measurable outcomes (not marginal contributions)
    • Return Expectations: Realistic return assumptions aligned with asset class and maturity profile

    Investor Typology and Return Expectations

    Impact investors have varying return expectations based on mission and capital source:

    • Philanthropic Capital: Grant-focused or concessionary return expectations; prioritizes impact over financial returns
    • Blended Finance: Combination of concessionary and market-rate capital; catalyzes private sector participation
    • Mainstream Institutional: Market-rate return expectations; impact as a value-creation driver and risk mitigation

    GIIN & IRIS+ Implementation

    Put This Portfolio Measurement Structure to Work

    During LP due diligence or annual stakeholder reviews, allocators evaluate whether your impact claims demonstrate authentic additionality or risk greenwashing. Missing baseline data or activity-based metrics invite immediate audit scrutiny.

    📋

    What’s In The Toolkit:

    • Impact Thesis Worksheet: Intentionality & Theory of Change.
    • IRIS+ Metric Selection Sheet: Core vs. supplementary screening.
    • Additionality Test Sheet: Counterfactual & attribution review.
    • Portfolio Matrix: Multi-asset construction tracker.
    • AI Bot Routines: 4 automated workflows ($17).
    Secure 1-Click Square Checkout

    Impact Performance Measurement and Reporting

    Standards and Best Practices

    • GIIN IRIS+ Reporting: Standardized metric reporting enables aggregation and benchmarking
    • GIIRS Ratings: GIIN’s Impact Business Rating uses proprietary methodology to assess company impact governance and performance
    • SASB Standards: Materiality-based framework for investor-relevant ESG outcomes; increasingly used for impact assessment
    • SDG Mapping: Alignment with UN Sustainable Development Goals provides stakeholder transparency

    Impact Reporting to Limited Partners

    Effective impact reporting communicates both quantitative metrics and qualitative narratives:

    • Aggregated impact data across portfolio (e.g., “Portfolio avoided 500,000 tCO2e in 2025”)
    • Per-investment case studies highlighting mechanisms and outcomes
    • Comparison to baseline and targets, with explanation of variances
    • Impact attribution and additionality assessment
    • Risk factors and contingency plans if targets are missed

    Challenges in Impact Measurement

    Attribution and Causality

    Establishing rigorous causal links between investment and outcome is methodologically challenging, particularly for social outcomes influenced by multiple actors and policy environments. Randomized controlled trials (RCTs) provide gold-standard evidence but are expensive and impractical for many investments.

    Benchmark and Baseline Problems

    Defining appropriate counterfactuals (what would have happened without the investment) requires context-specific analysis. General benchmarks may not capture local conditions or market dynamics, leading to over- or under-estimation of impact.

    Greenwashing and Impact Inflation

    Pressure to demonstrate positive impact can incentivize inflated metrics or inappropriate baselines. Third-party verification and standardized frameworks (IRIS+, GIIRS) help mitigate this risk but require investor diligence.

    Emerging Trends in Impact Investing

    Nature-Based Solutions and Biodiversity Impact

    Growing recognition of biodiversity loss has spurred impact investing in ecosystem restoration, sustainable agriculture, and wildlife protection. Metrics frameworks for nature impact are still developing but increasingly aligned with international standards (e.g., Task Force on Nature-related Financial Disclosures).

    Climate Resilience and Adaptation Impact

    While mitigation-focused investments remain dominant, adaptation impact (resilience building, climate-proofing infrastructure) is gaining traction, particularly in vulnerable regions.

    Integration with ESG and Mainstream Investing

    The boundary between impact and ESG investing is blurring. Mainstream funds increasingly incorporate impact measurement and reporting, while impact funds adopt ESG risk frameworks. This convergence creates opportunities for scale but requires vigilant attention to impact authenticity.

    Choose Your Impact Measurement Toolkit

    Grounded directly in published GIIN standards, IRIS+ metric sets, and the IMP Five Dimensions.

    Quick Reference

    Impact Investing Quick Card

    FREE

    2-page printable card: GIIN core characteristics, IRIS+ categories, and the 5 dimensions.

    Download Free PDF

    Working Pack

    Impact Thesis & IRIS+ Pack

    $7

    4-page fillable working pack: thesis builder, IRIS+ tracker, additionality test, and LP report.

    Buy Now ($7) →

    AI Intensive

    Impact Measurement Bot Book

    $17

    5-page feed-to-AI operating system: 4 AI-run routines with embedded output router.

    Buy Now ($17) →

    Frequently Asked Questions

    How does impact investing differ from ESG investing?
    ESG investing focuses on managing material business risks and opportunities related to environmental, social, and governance factors, with the goal of improving financial returns and risk management. Impact investing explicitly targets positive environmental or social outcomes, with financial returns as a secondary consideration. While ESG emphasizes risk mitigation, impact prioritizes outcome generation.

    What financial returns should impact investors expect?
    Expected returns vary by investor type and asset class. Market-rate impact investors target competitive returns (7-10% IRR for PE, 3-5% for fixed income) while generating measurable impact. Philanthropic and blended finance investors may accept concessionary returns (0-3%) if impact is sufficiently strong. Returns must reflect risk profile and market conditions.

    How is additionality assessed in impact investing?
    Additionality is evaluated by defining a counterfactual scenario: what would have happened without the investment? Assessment methods include market analysis (would the investment have occurred anyway?), beneficiary surveys, and comparative outcome measurement. Rigorous additionality assessment typically requires third-party evaluation and baseline data collection.

    Is IRIS+ the only impact measurement standard?
    IRIS+ is the most widely used standardized framework, but others exist, including the IMP framework, SASB Standards, GIIRS ratings, and SDG alignment tools. Many investors use multiple frameworks in combination to capture different dimensions of impact. Standardization is improving but full convergence remains a work in progress.

    Can impact investments achieve market-rate returns?
    Yes. Evidence from GIIN and other research demonstrates that impact investments can deliver competitive financial returns. However, return expectations must be realistic for the asset class and risk profile. Early-stage impact ventures may underperform initially; mature impact businesses in liquid markets often deliver returns on par with conventional peers.

    Related Resources

    Learn more about related topics:

    How Impact Is Measured: GIIN, IRIS+, and the Five Dimensions of Impact

    Impact in impact investing is measured by setting an intentional social or environmental goal, then tracking it with standardized metrics — most commonly the Global Impact Investing Network’s (GIIN) IRIS+ system — assessed across the Five Dimensions of Impact: What, Who, How Much, Contribution, and Risk. Credible measurement rests on three pillars: intentionality (a deliberate impact goal), additionality (impact that would not have happened otherwise), and measurability (outcomes tracked with evidence and reported transparently).

    The Five Dimensions of Impact

    The Five Dimensions of Impact are the shared analytical framework most impact investors use to describe and compare any impact. Originally built by the consensus-driven Impact Management Project (2016–2021) and now stewarded by Impact Frontiers, the five dimensions are also the backbone of how IRIS+ organizes its metrics. Each dimension answers one core question about an outcome.

    Dimension What it asks Example metric
    What What outcome is occurring, is it positive or negative, and how important is it to the people or planet experiencing it? Type of outcome delivered (e.g., tonnes of CO2e avoided; number of clients gaining access to clean energy)
    Who Who experiences the outcome, and how underserved are they? Share of beneficiaries who are low-income, women, or otherwise underserved (e.g., % of clients below the national poverty line)
    How Much How many people are affected, what degree of change do they experience, and for how long? Scale, depth, and duration (e.g., number of people reached; income increase per beneficiary; years the benefit persists)
    Contribution Did the enterprise’s and investor’s efforts produce outcomes likely better than what would have happened anyway? Counterfactual / additionality assessment (e.g., outcome vs. a baseline or comparison group)
    Risk What is the likelihood that the impact differs from what is expected? Impact risk rating across factors such as evidence risk, external risk, and drop-off risk

    IRIS+ and the Core Characteristics of Impact Investing

    IRIS+ is the GIIN’s free, generally accepted system for measuring, managing, and optimizing impact. At its center is the IRIS Catalog of Metrics — a standardized library of social, environmental, and financial performance indicators (the IRIS+ 5.3c Catalog was released in December 2025). Rather than asking investors to choose from thousands of metrics alone, IRIS+ packages them into Core Metrics Sets: curated, evidence-backed shortlists of indicators tied to specific Impact Themes (such as clean energy, financial inclusion, or affordable housing) and aligned to the UN Sustainable Development Goals (SDGs). IRIS+ metrics are also mapped to the Global Reporting Initiative (GRI) Standards and 50-plus other frameworks, which lets investors report once and translate across standards. In practice, an investor selects a theme, adopts the matching Core Metrics Set, collects the data, and uses it to compare performance against peers and against the investor’s own targets.

    IRIS+ operationalizes the GIIN’s four Core Characteristics of Impact Investing, which define what separates impact investing from conventional or simply ESG-screened investing:

    • Intentionality — the investment is made with an explicit, up-front intention to generate a positive, measurable social or environmental benefit alongside a financial return. Without a deliberate goal, an outcome is incidental, not impact.
    • Use evidence and impact data in investment design (measurability) — investors use research and data to design the investment, then systematically track, assess, and transparently report outcomes. Measurability is what makes a claim verifiable rather than aspirational.
    • Manage impact performance — investors build feedback loops, monitor progress toward the stated intention, and adjust when results fall short.
    • Contribute to the growth of the industry — investors use shared conventions and metrics (such as IRIS+) and share learnings, so the whole market can compare and improve.

    A closely related concept is additionality: the idea that the capital (or the investor’s non-financial support) produces impact that would not have occurred otherwise. Additionality is the practical test behind the “Contribution” dimension — it asks investors to define a counterfactual (what would have happened without the investment) and demonstrate that their participation changed the outcome.

    How Big Is the Impact Investing Market Today?

    According to the GIIN’s State of the Market 2025: Trends, Performance and Allocations report (published October 2025, drawing on reliable data from 429 organizations across 54 countries), impact investing assets under management (AUM) total roughly US$1.6 trillion — up from about US$1.16 trillion in 2022. The market has grown at a compound annual growth rate of approximately 21% over the past six years, including an 11% increase in the most recent year, a sign of durable demand even amid broader economic headwinds.

    The report also signals a maturing market on the returns side: roughly 79% of surveyed impact investors now target risk-adjusted, market-rate returns, rather than accepting below-market (concessionary) returns — evidence that investors increasingly view measurable impact and competitive financial performance as compatible rather than mutually exclusive. The sharpest growth in capital allocation has been in nature/biodiversity and energy-transition themes.

    Frequently Asked Questions

    What is IRIS+?

    IRIS+ is the Global Impact Investing Network’s (GIIN) free, generally accepted system for measuring, managing, and optimizing impact. It pairs a standardized Catalog of Metrics (the IRIS+ 5.3c Catalog was released in December 2025) with curated “Core Metrics Sets” tied to specific impact themes and aligned to the UN Sustainable Development Goals, so investors across the market can measure and compare impact in a consistent, evidence-based way.

    What are the Five Dimensions of Impact?

    The Five Dimensions of Impact are a shared framework for assessing any impact across five questions: What (the outcome and its importance), Who (who experiences it and how underserved they are), How Much (scale, depth, and duration), Contribution (whether the result was better than what would have happened anyway), and Risk (the likelihood that impact differs from expectations). The framework originated with the Impact Management Project and is now stewarded by Impact Frontiers.

    What is the difference between intentionality and additionality?

    Intentionality is about purpose: the investor sets out, deliberately and up front, to create a measurable positive social or environmental outcome alongside a financial return. Additionality is about causation: it asks whether that impact would have happened anyway, and credits only the change the investment actually caused (measured against a counterfactual baseline). An investment can be intentional yet have low additionality if the impact would have occurred without it — which is why both are assessed.

    How is impact measured in impact investing?

    Impact is measured by setting a clear intention, selecting standardized metrics (most commonly through the GIIN’s IRIS+ system), collecting data on outcomes, and evaluating that data across the Five Dimensions of Impact. Credible measurement also follows the GIIN’s Core Characteristics — intentionality, use of evidence and impact data, managing impact performance, and contributing to industry standards — so that claims are verifiable and comparable rather than anecdotal.

    How big is the impact investing market?

    The GIIN’s State of the Market 2025 report estimates global impact investing assets under management at roughly US$1.6 trillion, up from about US$1.16 trillion in 2022. The market has grown at a compound annual growth rate of about 21% over the past six years, with an 11% increase in the most recent year. The 2025 report drew on data from 429 organizations across 54 countries.

    What is the difference between IRIS+ and ESG?

    ESG (environmental, social, and governance) investing typically screens or scores companies to manage risk and reduce harm within a conventional portfolio. IRIS+ and impact investing go further: they require an intentional impact goal, measurement of actual outcomes (not just policies or ratings), and a demonstration that capital is contributing to change. In short, ESG often asks “is this company well-run and low-risk on sustainability?” while impact measurement asks “what positive outcome did this investment actually produce, for whom, and how much?”

  • Green Finance: The Complete Professional Guide (2026)

    Green Finance: The Complete Professional Guide (2026)

    Updated Oct 31, 2026 — added the free green label claim-test card, claim-test pack, and label interrogator bot book downloads to this guide.

    Green finance is not a product category. It is a claim — that money raised under a green label is governed by a stated framework, allocated to stated purposes, and reported against them — and in October 2026 that claim can be tested four different ways: against the voluntary market principles almost everyone uses, against a certification scheme with scientific thresholds, against the European Union’s statutory label, or against a court or regulator after the fact. A professional reading a green instrument needs to know which test the label in front of them actually passed.

    Two families divide the market. In use-of-proceeds instruments, an amount equal to the money raised is allocated to eligible projects; the label attaches to the use of the money. In sustainability-linked instruments, the money is for general purposes and the label attaches to the issuer’s forward-looking targets, with a financial consequence — usually a coupon step-up — if the target is missed. Everything else in this guide is the machinery that keeps those two claims honest: the principles, the reviewers, the one regulation with legal force, and the enforcement record that now disciplines the label where the principles cannot.

    Instant Green Debt Diligence Downloads

    Test Any Green Label Against the Four 2026 Benchmarks

    Field-ready claim-test cards, ICMA & EuGB Title II compliance sheets, SLB penalty step-up calculators, and AI label audit routines built directly from this guide.

    Quick Reference
    FREE

    Claim-Test Card

    2-page field card: The claim test on one card — testing green labels four ways in October 2026 (voluntary principles, scientific certification, EU statutory label, and antifraud enforcement) across use-of-proceeds and sustainability-linked debt.

    Download Free PDF

    Direct download • No email gate

    Working Pack
    $7

    Claim-Test Pack

    Printable/fillable working pack: Use-of-proceeds vs SLB sorter, GBP 4-component checklist, SLB 5-component tracker (24.8 bps step-up math), LMA loan log, EuGB Title II compliance sheet, and ESMA reviewer register.

    Get Working Pack ($7) →

    Instant checkout • Square verified

    AI Intensive
    Book for Bots
    $17

    Label Interrogator for Bots

    Feed to ChatGPT or Claude: 5 AI-run routines (GBP Alignment Auditor, SLB Credibility Diagnostic, EuGB Eligibility Interrogator, Transition Router, Reviewer Decoder) with embedded executive output router.

    Get Interrogator for Bots ($17) →

    Software made of words • Instant delivery

    The instrument map

    Instrument Governing document What the label certifies
    Green bond (use of proceeds) ICMA Green Bond Principles, June 2025 Proceeds allocated to eligible green projects under four core components; framework and external review recommended
    Social / sustainability bond ICMA Social Bond Principles, June 2025; Sustainability Bond Guidelines, June 2021 Same four components, applied to social projects, or an intentional green-and-social mix
    Sustainability-linked bond ICMA Sustainability-Linked Bond Principles, June 2024 Five components: KPIs, target calibration, bond characteristics, reporting, and mandatory post-issuance verification
    Green loan / sustainability-linked loan LMA, APLMA and LSTA Principles, 26 March 2025 The bond components translated to loans — with reporting owed to lenders, not the public
    Climate transition bond ICMA Climate Transition Bond Guidelines, November 2025 A use-of-proceeds label for high-emitting projects that go beyond green-project scope, under issuer-level safeguards
    European Green Bond (EuGB) Regulation (EU) 2023/2631 The statutory label: full taxonomy-aligned allocation, registered external reviewers, mandatory reviews
    Certified Climate Bond Climate Bonds Standard v4.3, August 2025 Instrument-level certification against sector criteria, decided by the Climate Bonds Secretariat

    The voluntary layer: ICMA’s principles, stated exactly

    The Green Bond Principles (June 2025) define a green bond as any bond instrument whose proceeds, or an equivalent amount, are exclusively applied to eligible green projects and which is aligned with four core components: use of proceeds; process for project evaluation and selection; management of proceeds; and reporting. The eligible categories are indicative, not closed — renewable energy, energy efficiency, pollution prevention and control, sustainable land and water management, biodiversity conservation, clean transportation, climate adaptation, circular-economy production, and certified green buildings among them. Two precision points matter. First, frameworks and external reviews are key recommendations, not core components: an issuer claims GBP alignment by meeting the four components, and the market then prices the absence of a review. Second, proceeds management means tracking — a sub-account, a sub-portfolio, or another formal internal process — not a trust and not bankruptcy remoteness. Refinancing existing projects is permitted; the issuer is recommended to disclose the financing-versus-refinancing share and any look-back period. Site coverage of the bond instruments themselves is at green bonds and sustainability-linked instruments.

    The Social Bond Principles (June 2025) mirror the same four components for social projects, classified by the issuer’s primary objective; a bond intentionally mixing green and social projects is a sustainability bond under the June 2021 Guidelines, which remain the current edition. The Sustainability-Linked Bond Principles (June 2024) are stricter in the place that matters most. Their five components end in verification, and verification is a necessary element, not a recommendation: an independent external reviewer must verify performance against each target at least annually and at every trigger date, and the result should be public. The pre-issuance second-party opinion, by contrast, is recommended. The principles also set no minimum coupon step-up — only that the variation be “commensurate and meaningful” relative to the bond’s original characteristics. That gap between a required verification and an unquantified penalty is where the sustainability-linked market’s credibility fight happens, and it is quantified in the failure modes below.

    Loans follow the same architecture with one structural difference. The Green Loan Principles and Sustainability-Linked Loan Principles published jointly by the LMA, APLMA, and LSTA on 26 March 2025 carry the same four and five components, written in mandatory language (“shall”), including the requirement that a sustainability-linked borrower’s trajectory evidence improvement beyond business as usual and regulatory requirements. But a green loan is not a public disclosure product: use-of-proceeds information is owed to the institutions participating in the loan, and public reporting is only a “should.” A loan can be fully principles-aligned and publicly invisible.

    Transition finance sits across both families. ICMA’s Climate Transition Finance Handbook (2020, updated June 2023) is entity-level guidance — strategy, governance, materiality, science-based targets, implementation transparency — not a project taxonomy. The Climate Transition Bond Guidelines of November 2025 add a standalone label for projects that complement and go beyond green-project scope: high-emission activities with substantial, quantifiable greenhouse-gas avoidance or reduction, under safeguards that include a credible issuer strategy, no feasible low-carbon alternative, taxonomy or pathway compatibility where available, mitigation beyond business as usual, and carbon lock-in analysis — with additional safeguards, including phase-out commitments and brownfield-only eligibility, where fossil-fuel infrastructure is involved.

    The statutory label: the European Green Bond Standard

    Regulation (EU) 2023/2631, applicable since 21 December 2024, is the only green-bond rule with legal force. The “European Green Bond” or “EuGB” designation is voluntary to adopt and exclusive once adopted: only bonds meeting Title II may use it, while any issuer may still market a bond as “green” outside it. Eligibility runs through the EU Taxonomy — the screening substrate examined in this site’s EU Taxonomy guide — and the mechanics are exact.

    Article 4 requires proceeds to be allocated in full, before maturity, in accordance with the taxonomy requirements, across fixed assets, qualifying capital and operating expenditure, financial assets created within five years, and household assets, with a portfolio approach for financial institutions and public-expenditure allocation for sovereigns. The provision most often misstated is Article 5’s flexibility pocket. It is not “85 percent aligned and 15 percent anything.” The issuer may allocate up to 15 percent to activities that meet the taxonomy requirements except the technical screening criteria, and only where no screening criteria have yet entered into force for the activity, or for specified international-support activities — with generic do-no-significant-harm criteria still applying to the first case. The other 85 percent is not a target; it is what remains of a full-allocation rule after a capped, conditional derogation.

    Around that core sit the transparency mechanics: a European Green Bond factsheet and a pre-issuance review with a positive opinion before issuance; allocation reports every twelve months until full allocation, with a mandatory post-issuance review of the report drawn up after full allocation; an impact report after full allocation (external review optional for impact, mandatory for allocation — the reverse of how the regime is often summarized); and a prospectus that uses the designation throughout. External reviewers must be registered with and supervised by ESMA. The transitional regime, under which firms could notify ESMA and operate on best efforts, ended on 21 June 2026; since then, unregistered firms may not provide EuGB reviews. ESMA’s register, updated 16 October 2026, lists seven registered reviewers — Moody’s (France and Germany), Sustainable Fitch Ireland, S&P Global Ratings Europe, ISS-Corporate, FSG Sustainable, and KPMG SA. ESMA fines reviewers (€20,000 to €200,000, and at least the financial benefit) for infringements including unregistered practice. Issuer penalties are national: Member States must make available sanctions up to at least twice the profit gained or, for a legal person, at least €500,000 or 0.5 percent of total annual turnover, including a prohibition on issuing European Green Bonds for up to one year. Title III of the same regulation offers optional pre- and post-issuance disclosure templates for non-EuGB bonds marketed as environmentally sustainable and for sustainability-linked bonds — voluntary to adopt, but adopting the post-issuance templates brings competent-authority supervision with it. This site’s market-side coverage is at the green bond market and the EU standard.

    Certification is not an opinion

    ICMA’s external-review guidelines separate four products that marketing language blurs: second-party opinions, verification, certification, and scoring or rating. A second-party opinion assesses a framework’s alignment with the principles. It does not apply a pass/fail scientific threshold, does not certify anything, and — under the Green Bond Principles — is not the required post-issuance audit of where the money went. The issuer selects and pays the reviewer; methodologies are not uniform; independence limits are disclosed, not eliminated.

    Climate Bonds certification is the different animal. Under the Climate Bonds Standard v4.3 (August 2025; a draft v4.4 section was published for consultation on 9 July 2026 and is not the operative standard), eligibility is decided by sector criteria — the substantive thresholds live in those criteria documents, not in the standard’s process text. Certification applies to each instrument, not to an issuer’s framework; an approved verifier reports against the criteria, and the certification decision is made by the Climate Bonds Standard Secretariat. Version 4.3 also certifies assets, qualifying non-financial entities with sector-aligned performance targets and transition plans, and sustainability-linked debt of such entities. Even then, certification speaks only to conformity at the time of certification; the standard’s own disclaimer states it carries no implication that any target has been achieved.

    Sustainable Debt Diligence Suite

    Put These Reviewer Audits & Compliance Screens Into Action

    Marketing materials routinely blur opinions, verifications, and certifications. Arm your capital markets team with printable GBP allocation logs, EuGB Article 4/5 compliance worksheets, SLB coupon step-up evaluation models, and interactive bot prompts that audit external review documents against ICMA and ESMA standards.

    ⚖

    What’s In The Toolkit:

    • GBP 4-Component Sheet: Allocation, selection, tracking & reporting.
    • SLB Penalty Math: 24.8 bps benchmark & trigger date audit.
    • EuGB Title II Sheet: Art. 4 full allocation & Art. 5 15% pocket qualifier.
    • ESMA Reviewer Check: 7 registered entities as of 16 Oct 2026.
    • Loan Principles Log: LMA/LSTA mandatory “shall” & private reporting.
    • Bot Interrogator: 5 executable AI routines & synthesis memo ($17).
    Secure 1-Click Square Checkout

    The market, with its adjectives attached

    Market totals in this field are meaningless without the publisher, the screen, and the cutoff. Climate Bonds Initiative publishes aligned volume — instruments passing its screening methodologies. For full-year 2025 (report posted 17 March 2026): aligned green, social, sustainability, and sustainability-linked issuance of $1.026 trillion, of which green was $653.5 billion (64 percent, the second-highest year, 3 percent below 2024) and sustainability-linked only $14.0 billion, though at the highest SLB alignment rate Climate Bonds had recorded. Cumulative aligned volume reached $6.75 trillion against $8.1 trillion of labeled volume tracked — the gap between those two numbers is the market’s measurable credibility problem. For the first half of 2026 (report dated 8 September 2026), aligned issuance was $529.7 billion, one percent below the same half of 2025, with green at $364.1 billion and aligned SLB volume down to $4.7 billion at a 32 percent alignment rate. No third-quarter 2026 Climate Bonds report existed at this guide’s publication, and the World Bank Treasury’s labeled series ($904 billion for 2025, transition included, no alignment screen) measures a different thing and should never be substituted for the aligned figures.

    The United States: no label law, antifraud law, and a rewritten subsidy map

    There is no federal green-bond or green-loan standard in the United States, and no US counterpart to the EuGB regulation. What disciplines a green claim is ordinary law: Securities Act section 17(a) and Exchange Act section 10(b) with Rule 10b-5 for material misstatements in securities offerings and trading, and the Advisers Act provisions the SEC has actually used in its ESG cases. The one naming regime with teeth is the Investment Company Act Names Rule: a fund calling itself “green” or “ESG” must hold an 80 percent investment policy consistent with its name. The 2023 amendments’ compliance dates, after a March 2025 extension, are 11 June 2026 for fund groups at or above $1 billion in net assets (that date has passed, on the annual-prospectus cycle) and 11 December 2026 for smaller groups; only the related Form N-PORT reporting moved, in March 2026, to November 2027 and May 2028. “The Names Rule was delayed to 2027” confuses the form with the policy.

    Public finance channels exist at state level — New York Green Bank, capitalized with $1 billion of ratepayer funds and reporting $3.0 billion deployed across 156 transactions since inception, is the worked example — but the federal map was redrawn on 4 July 2025 by Public Law 119-21. The Greenhouse Gas Reduction Fund’s statute (Clean Air Act section 134, $27 billion) was repealed and its unobligated balances rescinded; EPA had already terminated $20 billion of National Clean Investment Fund and Clean Communities Investment Accelerator awards on 11 March 2025 and announced the end of Solar for All on 7 August 2025. On 4 August 2026 the D.C. Circuit, sitting en banc, affirmed a preliminary injunction against effectuating those March 2025 termination notices, splitting on what the repeal does to money already obligated and disbursed — a preliminary-injunction ruling, not a final judgment. Elsewhere the pattern is surgical: the Energy Infrastructure Reinvestment authority (section 1706) was rewritten toward capacity and reliability and given a new $1 billion appropriation available through 30 September 2028; several IRA loan and transmission appropriations lost only unobligated balances; consumer and building credits closed on dates now past (30 September 2025, 31 December 2025, 30 June 2026); and wind and solar under sections 45Y and 48E face a placed-in-service cliff of 31 December 2027 that applies to facilities beginning construction after 4 July 2026 — a cliff that has not yet arrived. Hydrogen’s begin-construction date moved to 1 January 2028; nuclear (45U) and carbon sequestration (45Q) were restricted, not terminated. Any green-finance analysis that says the federal programs were “all repealed” or “all frozen” is wrong in both directions.

    Greenwashing enforcement: three regimes, three different objects

    The SEC’s ESG cases are adviser cases about process, not bond-allocation cases — and none found a green bond misallocated. BNY Mellon Investment Adviser (23 May 2022, $1.5 million) represented that all holdings in certain funds had passed an ESG quality review when numerous holdings had no review score at investment. Goldman Sachs Asset Management (22 November 2022, $4 million) operated for a period with no written ESG research procedures for one product, then did not follow the procedures it had — a policies-and-procedures case under Advisers Act section 206(4) and Rule 206(4)-7 only, not an antifraud charge. DWS (25 September 2023) marketed an ESG integration policy its order found it failed to implement: the ESG penalty was $19 million; the $25 million headline includes a separate $6 million anti-money-laundering order. All three settled without admitting or denying. The lesson is uniform: the marketed process must be the process used, documented at the time.

    The European Union’s instrument is consumer law. Directive (EU) 2024/825, the Empowering Consumers directive, blacklists generic environmental claims (“green,” “climate friendly,” “carbon friendly”) unsupported by recognized excellent environmental performance, whole-business claims based on one aspect, and — categorically — product claims of neutral, reduced, or positive greenhouse-gas impact based on offsetting. Member States were to apply their implementing measures from 27 September 2026, a date now passed; the directive bites through national law (a private transposition tracker counted 19 of 27 states in place on 8 October 2026), and it governs business-to-consumer product claims — not bond prospectuses, not corporate targets, not the word “green” in a framework. The United Kingdom’s regime is financial-promotion law: the FCA’s anti-greenwashing rule has been in force since 31 May 2024, requiring any sustainability reference by an authorized firm to be consistent with the product’s actual characteristics and fair, clear, and not misleading; the four voluntary SDR labels (Focus, Improvers, Impact, Mixed Goals) have been available since 31 July 2024 and govern fund names and marketing. They do not certify bonds.

    Failure modes, quantified

    Weak linked targets. Climate Bonds’ sustainability-linked database work found only 14 percent of SLBs (17 percent by amount) aligned with its climate methodology; coupon step-ups appeared in 58 percent of SLBs with an average of 24.8 basis points per target, and several targets had already been met at issuance. By 30 June 2026, $309.0 billion of cumulative SLB volume was classified not aligned, against $65.4 billion fully aligned. The SLBP’s “commensurate and meaningful” is a standard without a number; the market’s average is the number — and it is small.

    Opinion shopping as structure, not scandal. No regulator order located for this guide charges an issuer with commissioning successive second-party opinions until one said yes. The risk is structural rather than documented: the issuer chooses and pays, opinions assess alignment rather than outcomes, and for ordinary green bonds the pre-issuance review is recommended, not required. The EuGB regime is the regulatory answer for its label only — mandatory positive pre-issuance opinion, mandatory post-allocation review, reviewers ESMA registers and can fine. It governs nothing outside the designation.

    Reporting that never arrives. Climate Bonds’ February 2025 transparency study of the GSS market found 35 percent of sampled issuers failed to report within 365 days of issuance on at least one deal, about 30 percent of reporting issuers missed at least one pre-issuance commitment (reporting within a year, obtaining a review, disclosing the refinancing share), and average allocation stood at 91 percent of proceeds. Almost two-thirds obtained some post-issuance review, but only 5 of 29 assurance engagements covered both allocations and impacts, and 76 percent were limited assurance. The framework documents promise annual reporting until full allocation; the study is what the promise is worth unenforced.

    The label-screen gap. Of $8.1 trillion in labeled GSS+ volume tracked cumulatively to end-2025, $6.8 trillion was aligned. The remainder was issued with a sustainability label and failed the screen. That gap — not any single scandal — is the quantitative case for reading the framework, the reviewer, and the first allocation report before pricing the label.

    Tool Suite Overview

    Compare Green Finance Diligence Tools & Bot Systems

    Choose the right level of operational depth for your capital markets desk: rapid field reference, printable working checklists, or interactive bot-driven debt audits.

    Field Summary

    Claim-Test Card

    2-page field reference summarizing the four testing grounds for green finance labels.

    • Use-of-proceeds vs sustainability-linked architecture
    • ICMA GBP 4 components & SLBP 5 components
    • Climate Bonds Standard v4.3 sector thresholds
    • EuGB Title II Articles 4 & 5 core statutory mandates
    • SEC, EU consumer directive & UK FCA enforcement

    FREE

    Download Claim-Test Card (PDF)

    Instant direct download • No email gate

    Static Working Pack

    Claim-Test Pack

    6-page printable & fillable audit system with complete tables, formulas, and checklists.

    • Architecture sorter: money allocation vs KPI targets
    • GBP 4-component checklist & refinancing look-back log
    • SLB 5-component tracker & 24.8 bps step-up math
    • LMA loan log: mandatory “shall” & private disclosure
    • EuGB Title II compliance sheet: Art. 4 & 15% pocket
    • ESMA 7-reviewer register & reporting red flag log

    $7.00

    Get Working Pack ($7) →

    Instant delivery • Square checkout

    AI Intensive
    Book for Bots

    Label Interrogator for Bots

    Structured text document feeding 5 executable AI routines directly to ChatGPT or Claude to audit frameworks, SPOs, and prospectuses.

    • [ROUTINE-1]: GBP Alignment & Rollover Auditor
    • [ROUTINE-2]: SLB Credibility & Step-Up Diagnostic
    • [ROUTINE-3]: EuGB Statutory Title II Interrogator
    • [ROUTINE-4]: Transition Label Router & Lock-In Check
    • [ROUTINE-5]: Reviewer-Type Decoder (SPO vs CBI v4.3)
    • [ROUTER]: Embedded Executive Output Memo Router

    $17.00

    Get Interrogator for Bots ($17) →

    Software made of words • Instant delivery

    Frequently asked questions

    Does ICMA require a second-party opinion for a green bond?

    No. Under the Green Bond Principles (June 2025), external review is a key recommendation; the alignment test is the four core components. Under the Sustainability-Linked Bond Principles the position reverses after issuance: the pre-issuance opinion is recommended, but post-issuance verification of target performance is a necessary component. Under the EuGB regulation, both a positive pre-issuance review and a post-allocation review are mandatory, from an ESMA-registered reviewer.

    Is the EuGB’s 15 percent pocket free of the taxonomy?

    No. Article 5 permits up to 15 percent of proceeds in activities that meet the taxonomy requirements except the technical screening criteria, only where no criteria have entered into force for the activity or for specified international-support activities. The balance must be fully allocated in accordance with the taxonomy requirements under Article 4.

    What is the difference between an SPO and Climate Bonds certification?

    An SPO opines on a framework’s alignment with the principles; it applies no pass/fail scientific threshold and certifies nothing. Climate Bonds certification (Standard v4.3) tests an individual instrument against sector criteria through an approved verifier, with the certification decision made by the Climate Bonds Secretariat — and it speaks only to conformity at the time of certification, not to whether targets are later achieved.

    Is there a US green bond standard?

    No federal standard exists. A US green claim is disciplined by securities antifraud law, by the Names Rule’s 80 percent policy for funds with green or ESG names, and by whatever voluntary framework the issuer adopts. The SEC’s 2024 climate disclosure rules remain stayed and proposed for rescission; they are not in force.

    The cluster this guide anchors

    Green finance on this site is a cluster, and this guide is its map. The instrument mechanics are carried in depth by Green Bonds and Sustainability-Linked Instruments; the eligibility substrate by the EU Taxonomy guide; the market’s regulatory turn by Green Bond Market 2026; and the measurement discipline for capital allocated on purpose by Impact Investing: Measurement Frameworks and GIIN Standards. Read together, they make one argument: in this market the label is the beginning of the diligence, never the end of it.
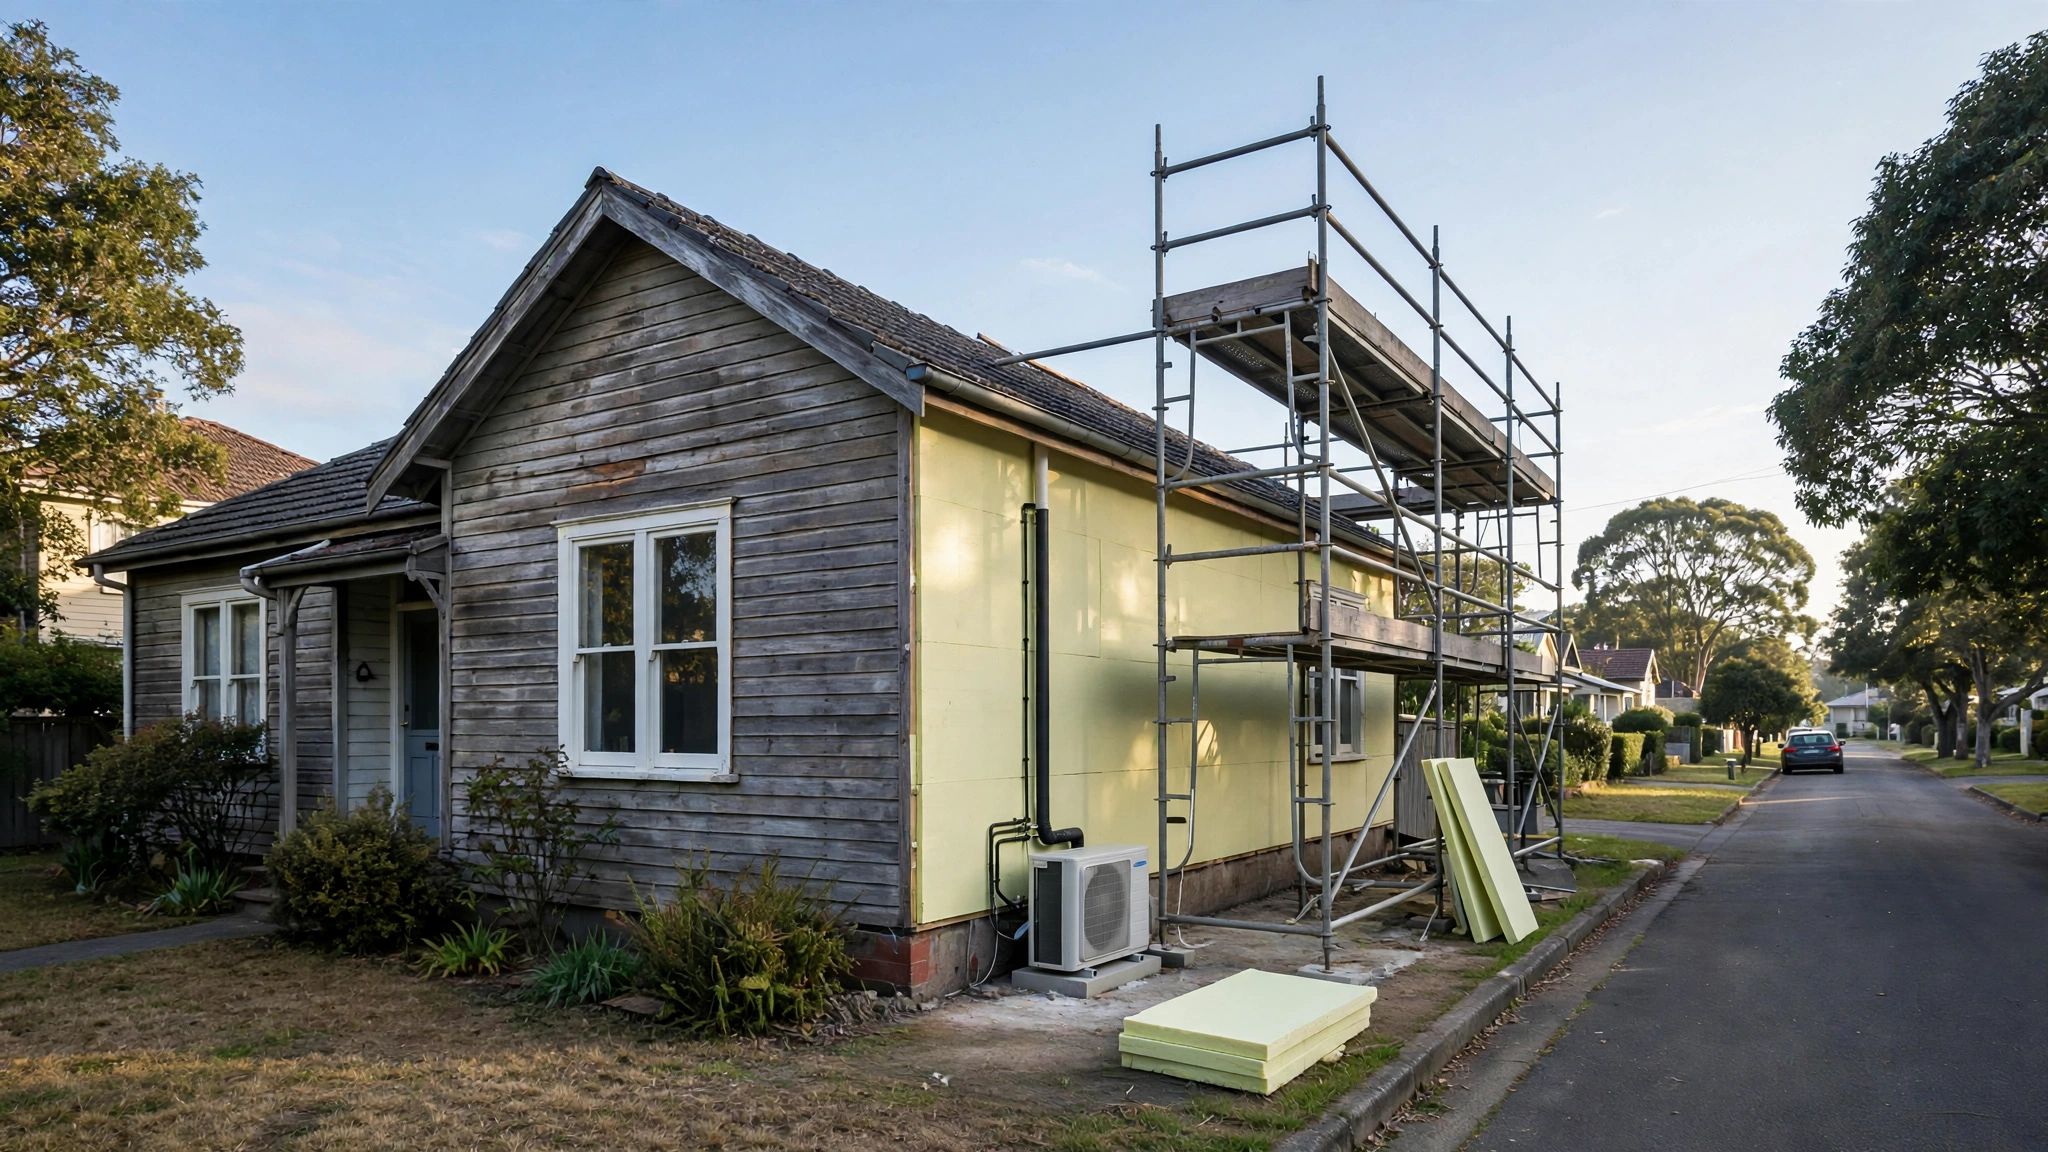
  • Green Bonds and Sustainability-Linked Instruments: ICMA Principles, Pricing, and Market Growth

    Green Bonds and Sustainability-Linked Instruments: ICMA Principles, Pricing, and Market Growth

    Green bonds are debt instruments whose proceeds are earmarked for environmental projects — renewable energy, clean transport, green buildings. They are the largest corner of the sustainable bond market, governed by the ICMA Green Bond Principles and, in Europe, the EU Green Bond Standard. This guide covers how they work, what the standards require, and how they differ from their cousins.

    What green bonds are

    A green bond is a standard bond with one defining feature: the issuer commits to using the proceeds exclusively for eligible green projects. The credit profile is the same as the issuer’s conventional bonds — investors are not taking project risk. What differs is transparency: allocation reporting, project selection criteria, and external review.

    Eligible project categories under market standards include renewable energy, energy efficiency, pollution prevention, sustainable water management, clean transportation, green buildings, and biodiversity conservation. Refinancing existing green assets is allowed, with look-back periods typically disclosed.

    The ICMA Green Bond Principles

    The Green Bond Principles (GBP), administered by ICMA, are the voluntary market standard most issuers follow. They rest on four pillars:

    • Use of proceeds — clear designation of eligible green project categories, with environmental objectives described.
    • Process for project evaluation and selection — how the issuer decides what counts as green, and who decides.
    • Management of proceeds — proceeds tracked in a sub-account or portfolio, with unallocated balances disclosed.
    • Reporting — annual allocation reporting (where the money went) and impact reporting (what it achieved) until full allocation.

    ICMA also publishes guidelines for external review: second-party opinions (pre-issuance), verification, certification, and scoring. A second-party opinion from a recognized provider remains the market norm for benchmark-sized deals.

    The EU Green Bond Standard (EuGB)

    The European Green Bond Standard (Regulation 2023/2631), applying since December 2024, is the regulatory gold standard — voluntary to use, but binding once chosen. Key requirements:

    • Proceeds must fund activities aligned with the EU Taxonomy’s technical screening criteria (with limited flexibility).
    • Issuers need an EU Green Bond factsheet, annual allocation reports, and impact reports.
    • External reviewers must be ESMA-registered — a regulated reviewer market, unlike the voluntary second-party opinion market.
    • Grandfathering provisions protect taxonomy-alignment if criteria change within a set window.

    The EuGB sits above the ICMA GBP in stringency. Issuers targeting EU institutional demand increasingly weigh the two labels side by side.

    Sustainability-linked bonds: the cousin

    Sustainability-linked bonds (SLBs) differ fundamentally: proceeds are for general corporate purposes, but the bond’s financial terms change based on whether the issuer hits predefined sustainability performance targets (SPTs) tied to key performance indicators (KPIs). Miss the target, pay a higher coupon (the “step-up”).

    SLBs suit issuers without large green asset pipelines — but they demand credible, ambitious, externally verifiable targets. Weak SPTs (targets the issuer would hit anyway) are the SLB market’s chronic greenwashing risk, and investors have grown markedly more skeptical of unambitious structures.

    Greenium: does green pricing exist?

    The “greenium” — a pricing advantage for green-labeled bonds versus conventional equivalents — exists but is inconsistent. It tends to appear in oversubscribed benchmark deals and in currencies with deep ESG-mandated investor bases (notably EUR), and to vanish in volatile markets. Treat any greenium as a sometimes-bonus, never as the investment thesis.

    Assurance and second-party opinions

    Market practice layers multiple checks:

    • Pre-issuance — second-party opinion on framework alignment with GBP (voluntary market) or ESMA-registered review (EuGB).
    • Post-issuance — annual allocation assurance; impact reporting assurance is less universal but growing.
    • Certification — the Climate Bonds Standard offers pre- and post-issuance certification against sector criteria, a step beyond opinion-based review.

    Greenwashing risks

    • Weak eligibility criteria — frameworks that stretch “green” to cover business-as-usual capex.
    • Allocation opacity — proceeds commingled without credible tracking.
    • Impact inflation — claimed emissions savings without baselines or methodology.
    • SLB target softness — SPTs set below business-as-usual trajectories.

    Regulators are watching: the EU’s greenwashing directives, the FCA’s UK regime, and the SEC’s climate disclosure framework all raise the cost of loose labeling.

    What issuers should do in 2026

    • Decide the label deliberately: ICMA-aligned, EuGB, or both — and say why.
    • Build the allocation tracking before the deal, not after.
    • Get the external review early — reviewer timelines are the most common cause of delayed launches.
    • Write the impact methodology into the framework; investors discount impact claims without it.

    The green finance cornerstone

    Instrument mechanics sit inside a wider market architecture — instruments, standards, verification, and enforcement. Green Finance: The Complete Professional Guide maps that architecture: the ICMA principles family, the EU Green Bond Standard, second-party opinions and certification, and the greenwashing cases that now discipline the label.

  • EU Taxonomy for Sustainable Activities: Technical Screening Criteria and 2026 Updates

    EU Taxonomy for Sustainable Activities: Technical Screening Criteria and 2026 Updates

    EU Taxonomy for Sustainable Activities: Technical Screening Criteria and 2026 Updates

    Updated October 6, 2026.

    If EU Taxonomy alignment is in your CSRD or investor reporting scope, this guide explains technical screening criteria, DNSH, and minimum safeguards as of October 2026.

    Definition: The EU Taxonomy is a classification system that defines which economic activities qualify as environmentally sustainable under European Union regulations, based on technical screening criteria aligned with climate and environmental objectives. The 2026 updates introduced materiality thresholds and enhanced screening criteria for economic sectors transitioning to sustainability.

    Overview of the EU Taxonomy Regulation

    The EU Taxonomy Regulation (Regulation 2020/852), which took effect in January 2022, is a cornerstone of European ESG policy. It establishes a standardized framework for assessing and communicating the sustainability of economic activities, enabling investors, companies, and policymakers to identify and allocate capital toward genuinely sustainable investments. As of January 2026, the Taxonomy has been substantially updated with new materiality thresholds and refined technical screening criteria.

    Purpose and Scope

    The Taxonomy serves multiple objectives:

    • Prevent greenwashing by establishing objective, science-based criteria for sustainability claims
    • Redirect capital flows toward sustainable economic activities
    • Support the EU’s climate and environmental commitments under the European Green Deal
    • Harmonize ESG terminology across member states and facilitate investor decision-making

    The Six Environmental Objectives

    The EU Taxonomy organizes sustainable activities around six core environmental objectives:

    1. Climate Change Mitigation

    Activities that contribute to stabilizing greenhouse gas concentrations. Examples include renewable energy generation, energy efficiency retrofits, sustainable transport, and circular economy solutions.

    2. Climate Change Adaptation

    Activities that reduce vulnerability to adverse climate impacts. Examples include flood defense infrastructure, drought-resistant agriculture, and climate-resilient building design.

    3. Water and Marine Resources Protection

    Activities that protect and restore water ecosystems and marine biodiversity. Examples include wastewater treatment, sustainable fisheries management, and coastal zone restoration.

    4. Circular Economy Transition

    Activities promoting waste reduction, recycling, and resource efficiency. Examples include waste-to-energy facilities, product design for circularity, and recycling infrastructure.

    5. Pollution Prevention and Control

    Activities that reduce air, water, or soil pollution and protect human health. Examples include emissions control systems, contaminated site remediation, and hazardous substance phase-out.

    6. Biodiversity and Ecosystem Protection

    Activities that restore ecosystems and protect biodiversity. Examples include sustainable forestry, habitat restoration, and sustainable agriculture practices.

    Technical Screening Criteria: 2026 Updates

    Materiality Thresholds

    The January 2026 update introduced materiality thresholds, requiring that economic activities demonstrate material contribution to their primary environmental objective. This prevents minor or marginal activities from being classified as sustainable. Materiality is assessed based on:

    • Quantitative metrics (e.g., GHG emissions reductions, waste diversion rates)
    • Comparative performance standards (e.g., best-in-class benchmarks)
    • Sector-specific technical specifications

    Sector-Specific Criteria Updates

    Sector Key 2026 Updates
    Renewable Energy Expanded criteria for battery storage, enhanced lifecycle assessment requirements, increased capacity thresholds for grid stability
    Energy Efficiency Strengthened building renovation standards aligned with NZEB (Nearly Zero Energy Building) definitions, enhanced baseline calibration
    Sustainable Transport Electric vehicle manufacturing requirements, zero-emission battery criteria, lifecycle GHG intensity thresholds
    Circular Economy Extended Producer Responsibility (EPR) alignment, recycling content targets, design-for-disassembly requirements
    Agriculture and Forestry Soil health metrics, biodiversity preservation standards, carbon sequestration quantification

    Do No Significant Harm (DNSH) Framework

    Beyond contributing to their primary environmental objective, activities must also satisfy “Do No Significant Harm” (DNSH) criteria across other objectives. This ensures that sustainability improvements in one area do not create environmental degradation elsewhere.

    DNSH Assessments by Objective

    For each activity, issuers and investors must document how the activity avoids significant harm across all six objectives. For example:

    • A renewable energy project must demonstrate it does not harm biodiversity (objective 6)
    • A waste management facility must show it does not increase water pollution (objective 3)
    • An energy efficiency retrofit must confirm it does not use hazardous substances (objective 5)

    Minimum Safeguards

    In addition to environmental criteria, the Taxonomy requires alignment with minimum social and governance safeguards, including:

    • Compliance with UN Guiding Principles on Business and Human Rights
    • OECD Due Diligence Guidance for Responsible Business Conduct
    • ILO Conventions on fundamental labor rights
    • Prevention of child labor and forced labor

    Corporate Disclosure Obligations

    Large companies (>500 employees) must disclose their Taxonomy alignment under the Corporate Sustainability Reporting Directive (CSRD), effective January 2026 for certain companies. Disclosure requirements include:

    KPIs and Reporting Metrics

    • Revenue alignment: Percentage of revenue from Taxonomy-aligned activities
    • Capital expenditure (CapEx) alignment: Percentage of investment directed to Taxonomy-aligned activities
    • Operating expenditure (OpEx) alignment: Percentage of operating costs related to Taxonomy-aligned activities
    • Eligibility vs. alignment: Disclosure of both eligible activities and truly aligned activities

    Investment Application and Portfolio Alignment

    ESG Fund Classification

    Asset managers use Taxonomy alignment as a basis for marketing sustainability-focused funds. SFDR (Sustainable Finance Disclosure Regulation) Article 8 and 9 funds must demonstrate Taxonomy alignment to support claims of sustainable investment objectives.

    Portfolio Construction Considerations

    • Identify companies and projects with high Taxonomy alignment percentages
    • Assess DNSH compliance to ensure holistic sustainability
    • Monitor transition activities (economically necessary but currently high-emitting) for credible decarbonization pathways
    • Evaluate management quality based on sustainability governance and safeguard compliance

    Challenges and Critiques

    Sectoral Gaps

    Some sectors remain underrepresented in detailed Taxonomy criteria. For example, software, healthcare, and financial services have limited specific guidance, creating interpretation challenges for companies in these industries.

    Transition Activity Definition

    The Taxonomy permits “transitional activities” for sectors essential to the economy but currently high-emitting, such as natural gas infrastructure. Defining appropriate transition pathways and timelines remains contentious, with stakeholders debating how ambitious criteria should be.

    Regional and Jurisdictional Differences

    As the Taxonomy is EU-specific, companies with global operations face complexity in reconciling Taxonomy compliance with other frameworks (ISSB standards, SEC rules, etc.), though convergence efforts are underway.

    Integration with Other Frameworks

    Alignment with ISSB and Global Standards

    The EU Taxonomy is increasingly converging with the ISSB (International Sustainability Standards Board) standards, particularly around climate disclosure and environmental materiality. This alignment reduces reporting burden and improves comparability across jurisdictions.

    Green Bond Integration

    Green bonds increasingly align project eligibility with Taxonomy criteria, enhancing investor confidence and regulatory compliance. Bond issuers reference Taxonomy alignment in prospectuses to substantiate environmental claims.

    Compliance Roadmap for Companies

    • Phase 1: Assessment – Identify which Taxonomy objectives are relevant to your business model and value chain
    • Phase 2: Screening – Map activities against technical screening criteria; separate eligible, aligned, and misaligned activities
    • Phase 3: Documentation – Gather quantitative data to substantiate alignment claims; document DNSH assessments
    • Phase 4: Disclosure – Report alignment percentages for revenue, CapEx, and OpEx in annual sustainability reports or CSRD filings
    • Phase 5: Improvement – Set targets to increase alignment; invest in transition activities with credible decarbonization pathways

    Frequently Asked Questions

    What is the difference between Taxonomy eligibility and Taxonomy alignment?
    An activity is eligible if it falls within the scope of defined Taxonomy activities; alignment is a stricter criterion requiring that the activity make a material contribution to an environmental objective and satisfy DNSH criteria. Not all eligible activities are aligned; some may require improvements or investments to achieve full alignment.

    How does the 2026 update affect companies currently reporting Taxonomy metrics?
    The 2026 update introduces more stringent materiality thresholds and refined technical screening criteria. Companies may see their alignment percentages decrease as they apply updated standards. This requires reassessment of activity classifications and potential investment in upgrades to maintain or improve alignment.

    Are non-EU companies required to use the EU Taxonomy?
    The EU Taxonomy is mandatory for EU companies and financial institutions, and for non-EU companies with significant EU operations. However, non-EU companies may voluntarily adopt Taxonomy criteria to attract EU investors or demonstrate ESG commitment. As standards converge globally, Taxonomy alignment becomes increasingly relevant.

    How should investors assess DNSH claims?
    Investors should demand detailed DNSH documentation from portfolio companies, including quantitative metrics (emissions, water consumption, biodiversity impact) and third-party verification. Independent assurance of DNSH assessments adds credibility and reduces greenwashing risk.

    What is the relationship between Taxonomy alignment and climate science?
    Taxonomy criteria are grounded in climate science and aligned with the Paris Agreement’s 1.5°C warming limit. Technical screening criteria are based on peer-reviewed research and regularly updated as climate science evolves. However, alignment with the Taxonomy does not automatically mean an activity meets all climate scenarios or decarbonization targets.

    Related Resources

    Learn more about related topics:

BC ESG

ESG Strategy, Sustainability Intelligence, and Business Continuity for Forward-Thinking Organizations

© 2026 BC ESG — Business Continuity, ESG & Sustainability Intelligence