Category: ESG Metrics

ESG metric selection, data collection, KPI benchmarking, and performance measurement across environmental, social, and governance dimensions.

  • Is Scope 2 Splitting Into Two Market-Based Methods? What Changes for Purchased-Electricity Claims

    Is Scope 2 Splitting Into Two Market-Based Methods? What Changes for Purchased-Electricity Claims

    Short answer: Not yet — and not by itself. In September 2026 the GHG Protocol’s Independent Standards Board (ISB) set a direction of travel for the Scope 2 revision: two market-based methods, running side by side for a transition period. Method 2 is the current 2015 method, unchanged. Method 1 is a stricter method built on hourly matching, deliverability and incrementality. Method 1 would be the recommended method during the transition, companies would have to disclose which method they used, and after a cutoff date that has not been set, Method 1 would become the required method wherever data meeting the quality criteria is available. None of this is in force. The 2015 Scope 2 Guidance remains the operative standard, and nothing you report today changes because of this decision.

    That distinction — direction set, rules not changed — is the whole story for anyone buying renewable energy certificates (RECs) or signing power purchase agreements (PPAs) against a Scope 2 claim this year: it tells you where certificate buying is heading, and it does not change what counts in your current inventory.

    Status at a glance

    • In force now: the GHG Protocol Scope 2 Guidance (2015), including dual reporting. No revision has been adopted.
    • Decided: nothing final. The ISB recorded majority support in July 2026 for developing two market-based methods, and set a direction of travel in September 2026 for the working group to refine.
    • Still open: the transition cutoff date; whether market-based reporting will be a “shall”, a “should” or a “may”; Method 2’s reporting unit; the incrementality window; any exemption threshold for smaller consumers.
    • Next milestones: a consolidated public consultation (Scopes 1, 2, 3 and market instruments), planned Q2 2027; the joint GHG Protocol–ISO Corporate Standard, planned for publication in Q4 2028.
    • Planning assumption, not a decision: working-group materials have used 2030 as an assumed effective date for a revised standard. Treat it as a placeholder.

    The rules you are actually reporting under: the 2015 Guidance in brief

    Scope 2 covers the emissions from generating the electricity, steam, heat and cooling a company buys. (New to the scopes? Our plain-English explainer, Scope 1, 2 and 3: The One Rule That Sorts Them, sets out how they divide.) The Scope 2 Guidance, published in 2015 as an amendment to the Corporate Standard, asks companies in markets that offer contractual instruments to report Scope 2 two ways:

    • Location-based: your consumption multiplied by the average emissions intensity of the grid where it happens. It answers: what does the grid I physically draw from look like?
    • Market-based: your consumption priced through the contractual instruments you have actually bought — energy attribute certificates, direct contracts, supplier-specific emission rates — with anything not covered taking the residual mix, the factor for electricity left in the market after everyone else’s claims are removed. It answers: what did I choose to buy?

    Market-based instruments only count if they meet the Guidance’s eight Scope 2 Quality Criteria. The ones that bite in practice: the instrument must convey the emission rate of the electricity generated; be the only instrument carrying that claim; be tracked and retired or cancelled by you or on your behalf; be issued and redeemed as close as possible to the period when you consumed the electricity; and come from the same market as your consuming operations. Note what those criteria do not require: matching within the year is enough, the market boundary is broad, and the age of the generating plant is irrelevant. A certificate from a decades-old hydro plant three states away can satisfy the 2015 criteria today. That gap — between what the accounting rewards and what physically supplies a building — is what the revision is about. (Our corporate carbon footprint calculator produces the location-based figure and states plainly that market-based accounting is outside its scope.)

    How the revision got to two methods

    The Scope 2 Technical Working Group began work in September 2024. Its proposed revisions went to public consultation from 20 October 2025 to 31 January 2026, drawing nearly 1,100 responses from 56 countries. The consultation draft proposed a single, stricter market-based method: certificates would count only if matched to consumption hour by hour and generated in a grid region that can actually deliver power to the consumer. The location-based method would also have been tightened, toward the most precise grid factor freely available — location precision first, then time.

    Feedback split into two camps — two theories of change, in the GHG Protocol’s own October 2026 update. One argues that clean power matched by the hour, delivered on the same grid, and generated by recently built plants pushes demand toward new clean generation where and when it is scarcest. The other argues that annual matching and wide boundaries keep the certificate market large, liquid and easy to join. Neither camp won. In April 2026 the ISB decided it would set the direction and the working group would resolve the open questions; the Secretariat’s proposal — one method per theory of change — became Method 1 and Method 2.

    The two methods, side by side

    Method 1 is the strict track. Three requirements define it:

    • Hourly matching. Certificates count against consumption in the hour they were generated, not across a year. A megawatt-hour of solar generated at noon in July does not offset a megawatt-hour consumed at 7 p.m. in January.
    • Deliverability. The generation must sit in a grid region that can deliver power to your operations — market boundaries aligned with the physical grid, not with a national certificate market.
    • Incrementality. Eligible generation would be limited by plant age, so claims rest on relatively new capacity. The window has not been set.

    Method 2 is the 2015 method carried forward: annual (or monthly) matching within existing market boundaries, the current Quality Criteria, legacy procurement strategies left intact. Under the September 2026 direction, companies could report under Method 2 until the cutoff date, should use Method 1 in the meantime, and must disclose which of the two a figure rests on. After the cutoff, a market-based figure would have to be a Method 1 figure where quality data is available. One level up, whether reporting a market-based figure at all will be required, recommended or optional — the “shall / should / may” wording — is explicitly unresolved.

    There is also a side door worth knowing about. The parallel Actions and Market Instruments workstream is developing a multi-statement framework in which procurement that does not meet market-based requirements can still be reported — in a GHG Impact Statement, or as non-GHG indicators such as the share of consumption matched with clean power. The direction is not “buy differently or claim nothing”; it is “claim it in the statement that matches what you actually did.” The ISO working group drafting the joint standard has reportedly taken a different line on some elements, including monthly rather than hourly matching as a floor.

    What hourly matching would actually demand

    Method 1 is as much a data requirement as a procurement rule. Claiming under it would take:

    • Interval consumption data. You cannot match hourly if your meter history is a monthly bill total. Hourly or sub-hourly meter data — utility, submeter, or building management system — becomes the evidentiary base of the claim.
    • Time-stamped certificates. Certificates would need generation timestamps granular enough to match, and a registry trail that preserves them.
    • A paper trail per instrument. Plant location and grid region, generation dates and hours, megawatt-hours, vintage, and retirement proof in the reporter’s name — the records that let an assurance provider test deliverability and matching rather than take them on faith.
    • Procurement shaped to a load profile. A flat annual REC purchase stops being a complete strategy. Matching a building that peaks on winter evenings points toward wind, storage-backed products or firmed hourly-matched PPAs — and toward knowing your hourly load shape before you shop.

    For a property manager, the translation is blunt: the buildings that will struggle under Method 1 are not the ones buying the wrong certificates. They are the ones that cannot say, hour by hour, what they consumed.

    What to do now, and what to wait on

    Do now:

    • Keep reporting both Scope 2 figures under the 2015 Guidance. Dual reporting is the current requirement, and regulators are building on it as it stands — California’s Air Resources Board staff proposal for 2027 SB 253 reports asks for both numbers under the current Guidance.
    • Ask your utilities and metering providers, in writing, whether hourly or interval data is available for each site, and keep the answer. It is the cheapest future-proofing available.
    • Tighten certificate records to the standard Method 1 would test: plant, location, vintage, megawatt-hours, retirement confirmation.
    • When a PPA or green tariff comes up for renewal, ask the hourly question — what share of our consumption would this product match hour by hour, in our grid region? — and file the answer, even if you buy on 2015 terms this cycle.
    • Brief whoever assures your inventory on which method each figure uses. Method disclosure is the one element of the September direction stated as a “shall” — expect it to survive into the final text.

    Wait on:

    • Do not restate past inventories, and do not describe any current figure as “Method 1” — the method does not exist yet as a standard, and claiming early compliance with an unfinished rule is a greenwashing exposure, not a head start.
    • Do not pay a premium for hourly-matched products solely for accounting reasons until the cutoff date, the incrementality window and the data-quality criteria are set. There may be energy or risk reasons to buy them; the accounting reason is not yet bankable.
    • Do not let a vendor sell you the revision as a 2027 compliance deadline. The next milestone is a consultation in Q2 2027 — a chance to comment, not a filing date.

    What stays unchanged

    The location-based figure is not going anywhere; both methods in the proposed split are versions of the market-based method, and the two-number structure of Scope 2 reporting survives the direction set so far. The physical point underneath the accounting also survives: certificates allocate claims, they do not reroute electrons. What the September 2026 direction changes is the long-run terms on which the contractual story will be believed. The wider standards landscape is tracked in our Environmental ESG complete professional guide, and we will update this page when the consolidated consultation draft is published.

    This article is general information about a standards revision in progress, based on the GHG Protocol’s published update of 16 October 2026 and the ISO–GHG Protocol partnership announcements. It is not accounting advice. The GHG Protocol Scope 2 Guidance (2015) remains the operative standard until a revised standard is published and takes effect; consult your assurance provider on your own inventory.
  • Scope 1, 2 and 3: The One Rule That Sorts Them

    Scope 1, 2 and 3: The One Rule That Sorts Them

    The same diesel truck can be Scope 1 for one company and Scope 3 for another, and neither company is wrong. Nothing about the truck changed. What changed is the relationship between the reporting company and the source of the emissions.

    That is the one rule underneath the GHG Protocol’s three scopes, and it is the rule most summaries leave out. The GHG Protocol classifies emissions according to the reporting organisation’s boundaries and its relationship to the source. It does not classify them simply by whether an activity happens inside or outside the organisation’s premises. A source can sit in your yard and still not be yours to report as Scope 1; a source inside a supplier’s factory on another continent can still belong in your inventory, as Scope 3.

    Sort by postcode instead of by relationship, and the inventory will misfile sources and miss whole categories.

    What the GHG Protocol is

    The GHG Protocol is the widely used international framework for measuring and reporting greenhouse gas emissions, developed by the World Resources Institute (WRI) and the World Business Council for Sustainable Development (WBCSD). Its Corporate Accounting and Reporting Standard — the Corporate Standard — defines the three scopes for a company-level inventory; a separate Corporate Value Chain (Scope 3) Standard sets out the Scope 3 categories in full, and separate Scope 2 guidance covers purchased energy.

    The framework’s job is attribution, and the GHG Protocol’s own summary is compact: Scope 1 emissions are direct emissions from owned or controlled sources; Scope 2 emissions are indirect emissions from the generation of purchased energy; Scope 3 emissions are all indirect emissions not included in Scope 2 that occur in the value chain of the reporting company, upstream and downstream.

    The same truck, walked through all three scopes

    Take one delivery truck making one delivery to your facility, in three arrangements.

    Your truck, your diesel. Your company owns and operates the truck, and it burns diesel your company bought. The combustion happens in a source you own or control, so those emissions are your Scope 1 — direct emissions.

    Their truck, your delivery. Now a third-party logistics provider makes the same delivery in its own truck, burning its own diesel, and you pay for the transportation service. For the provider, that diesel is its Scope 1, for exactly the reason above. For you, the same physical emissions are Scope 3 — specifically upstream transportation and distribution, Category 4 of the Scope 3 Standard, because you purchased the transport service. Same truck, same fuel, same road. The scope moved because your relationship to the source moved: owner-operator in the first case, customer in the second.

    Your truck, bought electricity. Finally, replace the diesel truck with an electric one your company owns and charges at your depot on purchased grid electricity. The truck produces no exhaust, but the electricity was generated somewhere by someone else, and you bought and consumed it. The emissions from generating that purchased electricity are your Scope 2. The charging did not become Scope 1 because the depot is your premises, and it did not become Scope 3 merely because the power station is off-site. Purchased energy consumed by the reporting company has its own scope.

    Three arrangements, three scopes, one vehicle — and the premises determined none of them.

    The three scopes, defined cleanly

    Scope 1: direct emissions from sources you own or control

    Scope 1 covers direct greenhouse gas emissions from sources within your organisational boundary — sources the reporting company owns or controls. In practice these come from stationary combustion (boilers, furnaces, generators), mobile combustion (company vehicles), process emissions from reactions in your own operations, and fugitive emissions such as refrigerant leaking from equipment you operate. The test is the boundary, not the building: if the source is yours under your chosen consolidation approach, its direct emissions are Scope 1 wherever it happens to be.

    Scope 2: indirect emissions from energy you buy and consume

    Scope 2 covers the emissions from generating the electricity, steam, heating and cooling your organisation purchases or acquires and consumes. The emissions physically occur at the generator’s facility; they are attributed to you because the energy was produced for your consumption. Scope 2 is reported two ways where the guidance applies: location-based, using the average emissions intensity of the grid where consumption occurs, and market-based, reflecting the contractual instruments — supplier contracts, power purchase agreements, energy attribute certificates — the company has actually bought. Our corporate carbon footprint calculator works through a location-based estimate so readers can see the mechanics on their own numbers.

    Scope 3: all other indirect emissions in your value chain

    Scope 3 covers every other indirect emission in the reporting company’s value chain, upstream and downstream, that is not already in Scope 2. You do not need to own the supplier’s factory, operate the carrier’s trucks, or control how a customer uses your product for the associated emissions to fall in your Scope 3 inventory. The Scope 3 Standard organises them into 15 categories: eight upstream, from purchased goods and services through employee commuting and upstream leased assets, and seven downstream, from downstream transportation through use and end-of-life treatment of sold products to investments. Not every category is material to every company; the work is deciding which are relevant and saying why the rest are not. For the hardest part — getting real data out of suppliers rather than spend-based proxies — see our field guide to Scope 3 supplier data.

    Why the premises mistake happens, and what it breaks

    The premises version is seductive because it is easy to draw: everything inside the fence is “ours,” everything outside it is “theirs.” For a single-site company with no leased assets or outsourced logistics, it can even produce a roughly right answer by accident. Then reality arrives — a leased warehouse, an outsourced delivery contract, a tenant in a building you own — and each separates location from control. Three kinds of damage follow:

    • Misclassification. Sources the company controls off-site get missed or pushed into Scope 3, and on-site sources belonging to tenants or contractors get pulled into Scope 1. The totals can look plausible while the attribution underneath is wrong.
    • Missed Scope 3 categories. If “not our premises” means “not our inventory,” the value chain disappears. Purchased goods, third-party freight, business travel, commuting, and the use of sold products are exactly what a premises test discards — and they are categories disclosure regimes increasingly ask about, as our guide to CSRD double materiality works through for real estate portfolios.
    • Double counting inside the inventory. A source filed twice — once by location and once by contract, when landlord and tenant both report the same boiler as Scope 1 — inflates one company’s inventory. That differs from the overlap the Protocol expects between companies: the provider’s Scope 1 and its customer’s Scope 3 legitimately describe the same physical emissions from two positions in one chain, which is why inventories should not be added together as if every reported tonne were separate. Overlap across inventories is by design; duplication within one is an error.

    The facility-level consequences — base building against tenant, landlord against occupier — are worked through in our carbon accounting guide for commercial facilities.

    Organisational boundaries: the choice that sits underneath

    Before any source can be sorted, the company has to say where the organisation ends. Under the equity share approach, a company accounts for emissions from an operation according to its share of economic interest in it. Under the control approaches, it accounts for all emissions from operations it controls — control defined in financial or operational terms — and none from operations it does not control, whatever its stake.

    Two consequences matter. First, the same joint venture can legitimately land in different places in two companies’ inventories, because each drew its boundary by its own stated approach. Second, leased assets are the standing edge case: whether a leased building’s or vehicle’s emissions fall in Scope 1 and 2 or in Scope 3 depends on the approach chosen and the lease structure — which is why the boundary decision must be documented and applied consistently, not improvised source by source.

    A three-question sorting checklist

    For any source in front of you, ask in this order:

    1. Do we own or control the source itself? If yes, its direct emissions are Scope 1 — the boiler’s gas, the truck’s diesel, the refrigerant that leaked from your chiller. If no, move on; do not stop here just because the source is on your site.
    2. Did we buy the energy it produced? If the emission came from generating electricity, steam, heating or cooling your organisation purchased and consumed, it is Scope 2 — however far away the generator sits.
    3. Is it in our value chain because of something we bought, sold, leased, invested in, travelled for, or disposed of? If yes, it is Scope 3. Find the category — purchased goods, upstream transport, waste, use of sold products — and file it there, not in a residual “other” line.

    If a source fails all three, it is not in your inventory, and you should be able to say why in one sentence. If it passes more than one, the order is the tiebreak: control first, purchased energy second, value chain last.

    Sorting is the start, not the finish

    The scopes are a filing system, not a result. A correctly sorted inventory still has to be measured, evidenced, and turned into targets a board can govern — where indicator design earns its keep, as our framework for KPI design for ESG performance sets out, and where the count itself should not be confused with the instruments traded against it, a distinction our explainer on carbon credits and the GHG Protocol keeps in view.

    None of that later work survives a wrong sort at the start. Draw the boundary, state the approach, and ask whose source it is before you ask where it sits. The truck will tell you the rest.

  • Designed Below the Limit, Built Above It: How Procurement Moves a Building’s Carbon Number

    Designed Below the Limit, Built Above It: How Procurement Moves a Building’s Carbon Number

    The short answer

    Yes — a building calculated below its embodied-carbon limit at design can finish above that limit once it is built. A 2026 Finnish study from VTT and Aalto University found that choosing high-carbon product alternatives over average ones, inside the same product groups the design already specified, may raise a building’s production-stage (A1–A3) emissions by 20 to 30%. The design did not change. The structure did not change. What changed was which supplier’s version of the same board, bar, and beam actually arrived on site.

    That is the gap this research measures for the first time: the distance between the building as calculated and the building as procured.

    Where the swing lives

    The researchers took a reference apartment building — five storeys, 1,370 m² in Helsinki, modelled in hybrid, timber, and concrete versions — and re-ran its product-stage emissions using real environmental product declarations (EPDs) for the highest- and lowest-carbon products inside each category. An average of five EPDs per category, all to the EN 15804+A2 standard.

    The spreads inside a single product group are wide:

    • Steel rebar: the high-carbon EPD runs +90% against the average; the low-carbon option runs −29%.
    • Stone wool insulation: +100% at the top of the range, −83% at the bottom.
    • Gypsum board: +53% / −56%.
    • Sawn timber: +60% / −27%.
    • Concrete: Finland’s low-carbon classification cuts C30/37 from 255 to 178.5 kgCO2e per cubic metre, and C35/45 from 315 to 220.5.

    Rolled up to the whole building, high-carbon choices inside the specified groups added 20% (hybrid), 30% (timber), and 24% (concrete) to A1–A3 emissions versus average products. Low-carbon choices cut 17 to 23%. In other words, procurement holds a swing of roughly half the production-stage footprint, in both directions, without touching the design.

    And that understates it. Building services — the single largest contributor in the reference building, at 30 to 40% of A1–A4 emissions — had to be left out of the variation entirely, because too few EPDs with genuinely lower-carbon alternatives exist yet for equipment like elevators and air handling units. When those declarations mature, the procurement swing gets bigger, not smaller.

    The second front: transport and the site itself

    Modules A4 and A5 — getting materials to site and running the site — swung wider still. Across transport, construction machinery, and site energy use, the study’s low-carbon scenario came in 58% below the average scenario, and its high-carbon scenario 152% above it.

    The widest single lever was the electricity the site runs on: hydro power versus the standard Finnish production mix differed by a factor of 21, and a grey residual mix ran another factor of five above the average. Transport told the same story in miniature — electric trucks at 6 tonnes of CO2e for the reference project, biodiesel at 29, diesel at 59. None of these are design decisions. All of them are made by whoever plans logistics and site operations, usually after the carbon calculation is already filed.

    Why Finland’s rule makes this a compliance problem, not a curiosity

    The Finnish Building Act does something most regimes do not: it mandates the embodied-carbon calculation, and tests it against the legal limit value, only after construction, on the building as built. The European EPBD, by contrast, asks for the whole-life carbon assessment during design.

    Under an as-built test, the sequence inverts. The design team calculates a compliant building. Procurement then makes the final product choices — in Finnish practice, routinely, inside the design framework — and the emissions are realized on site. If those choices drift high, the building crosses its limit at exactly the moment nothing can be redesigned. The failure is discovered when it is permanent.

    Any jurisdiction moving toward limit values inherits some version of this exposure. The specific trigger differs — an as-built assessment, a tightening limit at a later permit stage, an EPD-based specification audited at completion — but the mechanism is identical: the number is not final when the design is. It is final when the last substitution is approved.

    The two moves the study recommends

    The authors’ recommendations are plain, and both are cheaper than the failure they prevent.

    Design with a safety margin. If product choice alone can move A1–A3 by up to 30%, a design that lands at 97% of the limit has not complied — it has gambled. The margin belongs in the calculation from the start, sized to the spread of the products the specification actually allows.

    Steer the footprint while it can still be steered. The study calls for better data collection and visibility during construction, plus a post-construction evaluation calculation. In practice that means treating substitution as a compliance act: a specified product swapped for an “equivalent” is checked against its EPD and the running total before it is approved, not discovered after it is installed. The carbon ledger stays open and visible for as long as the building is still changeable — which is precisely the procurement window.

    Read the numbers the way the authors ask you to

    This is one Finnish reference building, EPD samples are small, the site-operation figures were transplanted from two Norwegian cases, and the authors say plainly that their results are indicative rather than exact. What travels is not the third decimal place. What travels is the mechanism: inside every product group your specification already names, there is a high-carbon version and a low-carbon version, and the difference between them is large enough to decide whether a compliant design becomes a compliant building.

    The design sets the ceiling. Procurement decides whether the building stays under it.

    Source: Vainio-Kaila, T., van den Brink, R., Ala-Kotila, P., Lavikka, R., Nyqvist, R. “The effect of procurement and construction site decisions on the embodied carbon emissions of buildings: a Finnish perspective.” IOP Conference Series: Earth and Environmental Science 1672 (2026) 012051. VTT Technical Research Centre of Finland and Aalto University. Open access (CC BY 4.0).

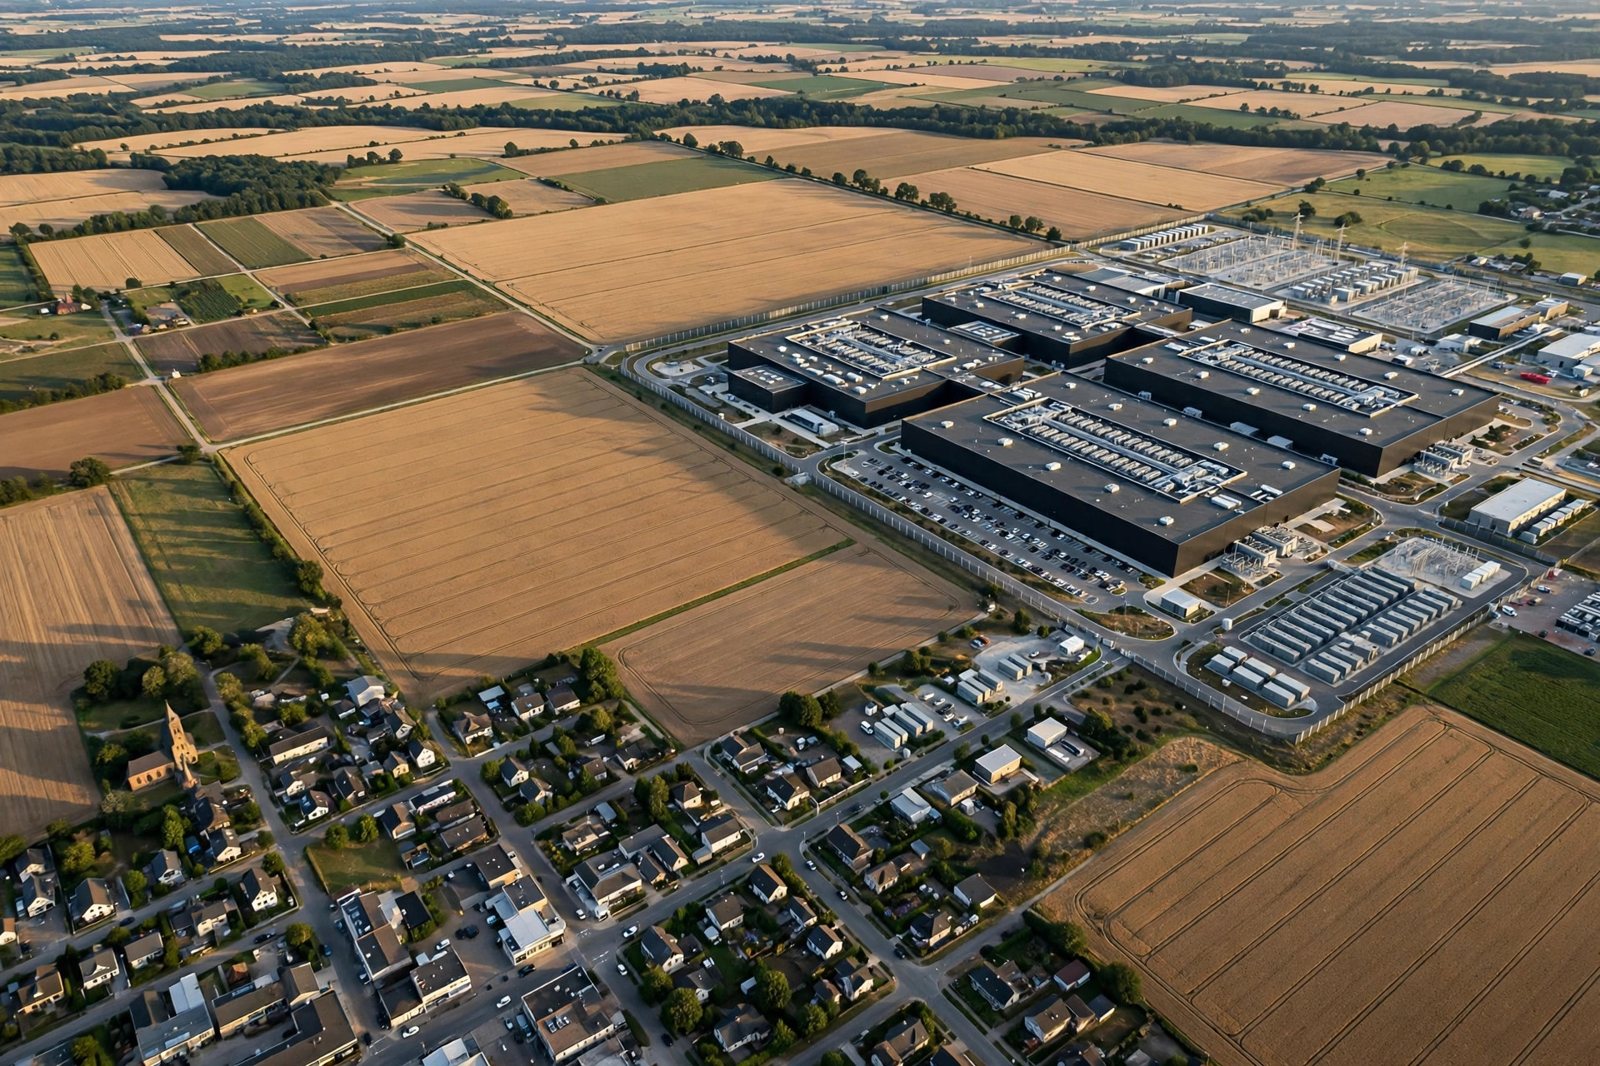
  • The Data Center Oversight Act: What Operators Would Have to Put in Public

    The Data Center Oversight Act: What Operators Would Have to Put in Public

    A data center deal usually arrives in a community the same way: a codename, a closed session, and a nondisclosure agreement. A new federal bill proposes to reverse that order. The Data Center Oversight Act, introduced in the House on October 29, 2026 by Rep. Eugene Vindman of Virginia, would make the Energy Information Administration collect — and publicly report — a standard set of facts about every existing and proposed data center in the country. For developers and host communities alike, the practical question is simple: exactly what becomes public? Here is the checklist, as written.

    What is being proposed

    The Act would require the Energy Information Administration (EIA), within the Department of Energy, to collect and publicly report comprehensive information on both existing data centers and proposed developments. Operators submit the information; EIA publishes it.

    Status: this is an introduced bill, not law. It was introduced October 29, 2026, and has the long committee road in front of it. But disclosure bills like this one also move the market before they move Congress — the checklist below is already a fair preview of what host communities, journalists, and competitors will ask for in 2027 whether or not the bill passes.

    The disclosure checklist

    Under the Act, operators would have to report:

    • Ownership — who actually owns the facility.
    • Energy usage — expected or actual electricity consumption.
    • Water usage — expected or actual water consumption.
    • Ratepayer costs — the costs of serving the facility that may be passed on to utility ratepayers.
    • Nondisclosure agreements — whether the facility’s owners have signed NDAs with government officials.
    • Union labor — whether union labor was used in construction.
    • Sensitive proximity — whether the facility sits within 1,000 feet of a school, a national park, a hospital, or a home.

    Read the list as a community would. Energy and water are the resource questions every county hearing now runs on. The ratepayer-cost item goes at the subsidy argument directly: not what the facility pays, but what its presence costs everyone else on the grid. And the proximity item converts the most emotional local question — how close is this thing to where people live, learn, and recover — into a yes/no federal data point.

    The NDA item is the sharp edge

    Most of the checklist asks for numbers. The nondisclosure item asks for a fact about secrecy itself: not the contents of any agreement — the Act does not reach those — but whether one exists between the developer and government officials.

    That single yes/no changes local politics. Today, a resident who asks why a project was negotiated in private can be told nothing at all. Under the Act, the existence of the NDA is itself a disclosed, federally reported fact. Developers who treat confidentiality as the default opening move would be making that choice in public.

    What does getting it wrong cost?

    Entities that fail to report, submit incomplete information, or provide misleading information face penalties of up to $1 million per day.

    The structure matters as much as the number. The penalty covers three distinct failures — silence, incompleteness, and inaccuracy — and it runs per day, which means a disclosure problem is not a fine you budget for; it is a clock that runs until the filing is right. At that scale, disclosure stops being a communications task and becomes a compliance function with records, owners, and review — the same treatment environmental and financial reporting already get.

    This bill does not arrive alone

    The Oversight Act is Vindman’s third data-center measure of 2026. In October he introduced the Make Data Centers Pay Act, aimed at shielding households and small businesses from electricity costs driven by data-center demand. In August, the Smart Data Center Policy Act took up development near neighborhoods, schools, and parks. Read together, the three bills mark the shape of the federal argument: who pays, where it goes, and — with this Act — who has to say so, in public, in advance.

    The state and local layer is moving the same direction. Water and energy disclosure fights now attach to individual projects, and the physical-risk questions communities ask — water scarcity chief among them — have become standard diligence, not activism.

    What a developer or a host community should do now

    You do not need the bill to pass to use the checklist. For a developer, it is a pre-announcement inventory: for any live or proposed site, could you answer all seven items today, accurately, from records? Ownership structures, utility-service cost allocations, and construction-labor facts are easy to state early and hard to reconstruct under a per-day clock. For a host community, the checklist is the term sheet for your own questions — ask for these seven items in the first public session, while the answers are still cheap.

    The industry’s growth is not the controversy anymore. The controversy is whether the facts arrive before the concrete does. This bill’s answer is a form, filed with the EIA, where anyone can read it.

    Informational only — this article summarizes the Data Center Oversight Act as introduced on October 29, 2026, per the sponsor’s published summary and contemporary reporting; it is not legal advice, and a bill’s text and prospects can change. Sources: Office of Rep. Eugene Vindman (Oct 29, 2026); Nextgov/FCW, “Tech bills of the week” (Oct 30, 2026).

  • Board Oversight & ESG-Linked Executive Compensation: Aligning C-Suite Pay with 2026 Performance Targets

    Board Oversight & ESG-Linked Executive Compensation: Aligning C-Suite Pay with 2026 Performance Targets

    A board governance blueprint for compensation committees, chief sustainability officers, and legal counsel.

    Connecting executive compensation to ESG performance has moved from a qualitative signalling exercise into a standing governance question for global enterprises: not whether sustainability belongs anywhere near the pay plan, but how a committee structures the link so it survives investor scrutiny, proxy-advisor methodology, and its own disclosure. This blueprint sets out the architecture — what the advisors actually test, what disclosure law requires, how to weight and safeguard the metrics, and the sequence a board runs for the 2026 performance cycle. It sits above the sector verticals in this series — pharmaceutical companies’ ESG executive compensation and beauty companies’ executive pay and sustainability targets — and draws its metric mechanics from the fleet’s KPI design framework for ESG performance.

    Board Governance Toolkits

    2026 ESG-Linked Pay Toolkits: Quick Card, Committee Pack & Board Pay Bot Book

    Printable allocation models, 50/100/150 gates worksheets, proxy-advisor disclosure checklists, and machine-executable AI audit routines built directly from our board governance blueprint.

    Field Reference
    FREE

    ESG-Linked Pay Quick Card

    2-page field summary: the STI (10–15%) and LTI (15–25%) weight bands, 50/100/150% gates grid, 4-metric reference table, and ISS/Glass Lewis disclosure test on one card.

    Download Free PDF

    Direct download • No email gate

    Working Pack
    $7

    2026 Committee Pack

    7-sheet printable/fillable pack: STI/LTI variable pay allocation worksheet, 50/100/150% gates grid, 4-metric data lineage log (>80% Tier-1, CSRD/IFRS S1/S2, 6.5% Scope 1+2, zero LL97 $268/ton fines), ISS/Glass Lewis checklist, CSRD GOV-3 & SB 253/261 checklist, verification worksheet, clawback contract clauses, and sector benchmark table.

    Get Committee Pack ($7) →

    Instant checkout • Square verified

    AI Intensive
    Book for Bots
    $17

    Board Pay Bot Book

    Feed to ChatGPT or Claude: 5 interactive AI routines (Proxy-Advisor Disclosure Stress-Test, Regulatory Disclosure Floor Mapper, STI/LTI Architect, Safeguard & Clawback Integrator, Q1-Q4 Board Roadmap Runner) + embedded command router.

    Get Bot Book ($17) →

    Software made of words • Instant delivery

    What ISS and Glass Lewis actually do — and do not — require

    The load-bearing fact first, because it is widely overstated: neither ISS nor Glass Lewis requires a company to tie variable executive pay to sustainability metrics. Their 2026 guidelines discipline two things — pay-for-performance alignment and the quality of disclosure. They test whether incentive structures are rigorous, whether performance goals are objective and measurable, whether the committee discloses weights, targets, and outcomes, and whether payouts follow the disclosed design. Where a board chooses ESG metrics, the advisors apply the same tests they apply to financial metrics: a stated weight, a quantified target, an outcome the shareholder can recompute. An ESG metric that is vague, discretionary, or paid out regardless of result draws exactly the criticism a soft financial metric would.

    The same discipline comes from the large institutional asset managers — BlackRock, Vanguard, and State Street among them — whose stewardship teams ask, in engagement and in published voting guidance, for a disclosed rationale connecting incentive design to strategy and long-term value. None of this mandates an ESG pay metric. All of it raises the cost of a badly built one. A compensation committee that adopts sustainability metrics should therefore build them to the standard the advisors will grade: transparent, quantifiable, and verified before they pay.

    The disclosure floor underneath the design

    Three regulatory regimes convert sustainability performance into standing disclosure obligations that a pay plan then samples from:

    • EU CSRD & ESRS. In-scope companies report under the European Sustainability Reporting Standards, including a double materiality assessment and governance disclosures. ESRS 2 (GOV-3) requires a company to disclose whether and how sustainability performance is taken into account in its incentive schemes — the pay link itself is reportable, whether the answer is a detailed structure or none at all.
    • California’s climate statutes (SB 253 & SB 261). Enterprise-wide Scope 1, 2, and 3 greenhouse gas reporting and climate-related financial risk disclosure, on hard regulatory submission dates, for companies doing business in California above the revenue thresholds.
    • Municipal building performance standards. Frameworks such as New York City’s Local Law 97 impose carbon intensity limits on large buildings backed by penalties of $268 per metric ton of CO2e over the limit — a recurring operating cost that lands directly in asset valuations and, through them, in executive scorecards for real-estate-exposed businesses.

    Designing the incentive structure

    A resilient architecture balances the annual plan against the long-term plan, and leading indicators against lagging ones.

    Short-term incentives (annual cash bonus) typically carry 10% to 15% of the total bonus pool for sustainability components, focused on near-term execution: data pipeline readiness, supplier onboarding, compliance milestones. Long-term incentives (performance share units) typically carry 15% to 25% of the multi-year grant, focused on cumulative decarbonization, portfolio transformation, and capital deployment over three-to-five-year cycles. Setting the overall sustainability allocation between 10% and 25% of variable pay gives the goals genuine weight without creating single-metric distortion.

    Indicator category Focus area & metric Practical target benchmark Incentive vehicle Verification standard
    Leading Vendor data integration & supply-chain mapping Onboard >80% of Tier-1 suppliers into the enterprise vendor carbon reporting system STI (annual bonus: 5–10% weight) ISO 14064-3 data audit & vendor portal system logs
    Leading Audit readiness & reporting frameworks Complete the CSRD double materiality matrix; align baseline disclosures with IFRS S1 and S2 STI (annual bonus: 5% weight) Independent legal & external auditor attestation
    Lagging Operational GHG emissions reduction Achieve a certified 6.5% annual reduction in combined Scope 1 and 2 emissions (1.5°C SBTi alignment) LTI (3-year PSU: 10–15% weight) Third-party limited / reasonable assurance (ISAE 3000)
    Lagging Real-estate energy intensity & fine avoidance Zero statutory fine exposure across holdings under NYC Local Law 97 ($268/ton penalty) LTI (3-year PSU: 5–10% weight) Certified Energy Star & engineering energy audit reports

    Executive Pay Design Worksheets & Bot Routines

    Align 2026 Executive Pay to Disclosure Floors & Proxy Rigor

    When proxy advisors grade your 2026 proxy statement, subjective or unearned sustainability payouts draw immediate Say-on-Pay scrutiny. Our printable 7-sheet Committee Pack provides the exact allocation models (10–15% STI / 15–25% LTI), formulaic 50/100/150% gates, and model clawback clauses required by compensation committees — or feed our $17 Bot Book to ChatGPT or Claude to stress-test your metrics for ISS/Glass Lewis recomputability, map CSRD GOV-3 and California SB 253/261 disclosure floors, and draft your CD&A proxy section automatically.

    ☑

    What’s In The Toolkit:

    • Allocation Worksheet: 10–15% STI / 15–25% LTI.
    • Gates Architecture: 50% / 100% / 150% formulaic cap.
    • 4-Metric Reference: Lineage logs & verification.
    • ISS / Glass Lewis Test: Recomputable outcome audit.
    • Regulatory Floor Map: CSRD GOV-3 & SB 253/261.
    • Clawback Clauses: ISAE 3000 assurance & restatement.
    • AI Bot Book ($17): 5 prompt routines + router.
    Instant download after checkout • Printable PDF & Bot-ready text

    Committee responsibilities and anti-greenwashing safeguards

    Clear governance boundaries keep the design honest. The Compensation Committee holds primary jurisdiction over incentive plan design, weightings, threshold approvals, metric calculation formulas, clawback enforcement, and final payouts. The Sustainability & Governance Committee oversees materiality determinations, evaluates carbon accounting methodologies, recommends metrics aligned to the corporate risk register, and monitors regulatory developments.

    Three structural safeguards protect the board from enforcement and litigation exposure:

    1. Mandatory third-party verification before payout. No variable pay linked to ESG performance vests or pays out without prior independent assurance (ISAE 3000 or ISO 14064-3) from a certified external auditor.
    2. Clawback and malus provisions. Agreements carry explicit recovery triggers: vested payouts can be clawed back and unvested grants cancelled if carbon accounting data is restated, found fraudulent, or if regulatory non-compliance penalties arise from executive oversight failures.
    3. An auditable data trail. Reporting systems maintain verifiable lineage from primary operational data — utility bills, facility meters, supplier disclosures — directly to the executive scorecard metrics.

    Sector benchmarks

    Incentive metrics must reflect each sector’s operational reality. Commercial real estate: portfolio energy use intensity reductions, Energy Star certification targets, GRESB standing, and eliminating municipal penalty exposure such as Local Law 97 fines. Enterprise and technology: renewable power purchase agreement execution, Scope 3 supply-chain decarbonization, data-center power usage effectiveness, and ISSB IFRS S1/S2 disclosure readiness. Consumer brands and retail: sustainable packaging adoption, circular design metrics, and supplier carbon auditing, structured through the pay-alignment frameworks the beauty sector vertical in this series documents in detail.

    Compare 2026 ESG Executive Compensation Toolkits

    Choose the quick reference card, printable committee working pack, or machine-executable AI playbook that fits your board governance cycle:

    Free Field Summary

    ESG-Linked Pay Quick Card

    2-page field reference: condensed summary of STI/LTI weight bands, 50/100/150% gates, 4-metric benchmark table, and ISS/Glass Lewis disclosure criteria.

    FREE
    direct download
    • STI (10–15%) & LTI (15–25%) Allocation Bands
    • 10–25% Total Variable Pay Governance Floor
    • 50% Threshold / 100% Target / 150% Stretch Cap Grid
    • 4-Metric Reference Table (Leading vs Lagging)
    • ISS & Glass Lewis 4-Pillar Disclosure Audit Test
    • CSRD GOV-3, SB 253/261 & Local Law 97 Overview
    • Five-Step 2026 Board Governance Roadmap Timeline

    Download Free PDF

    Working Pack

    2026 Committee Pack

    Printable, fillable 7-sheet working pack with allocation models, performance gates grids, proxy checklists, and contract clawback clauses.

    $7.00
    one-time
    • Sheet 1: Executive Variable Pay Allocation Worksheet
    • Sheet 2: Formulaic 50 / 100 / 150 Payout Gates Grid
    • Sheet 3: 4-Metric Benchmark Reference & Lineage Log
    • Sheet 4: ISS & Glass Lewis Disclosure Defense Checklist
    • Sheet 5: Regulatory Disclosure Floor Checklist (CSRD/SB)
    • Sheet 6: Pre-Payout Verification & Clawback Clauses
    • Sheet 7: Sector Benchmark Table & 2026 Board Checklist

    Buy Committee Pack ($7) →

    AI Intensive
    Book for Bots

    Board Pay Bot Book

    Structured 7-page AI playbook for ChatGPT, Claude, and Gemini: 5 machine-executable governance routines + embedded command router.

    $17.00
    one-time
    • Routine 1: Proxy-Advisor Stress-Test (/audit-metrics)
    • Routine 2: Disclosure Floor Mapper (/map-floors)
    • Routine 3: STI/LTI Scorecard Architect (/architect-pay)
    • Routine 4: Clawback & Safeguard Integrator (/safeguard)
    • Routine 5: Q1-Q4 Board Roadmap Runner (/run-roadmap)
    • Embedded Command Router & Session Diagnostics
    • Full Governance Dossier & CD&A Proxy Text Generator

    Buy Bot Book ($17) →

    The 2026 board roadmap: five steps

    1. Materiality audit & baseline (Q1). Run the double materiality review, identify the core ESG risks, and establish audited base-year data for every target metric — data integrity before target-setting.
    2. Framework & weighting design (Q2). Set the STI/LTI allocation (10–15% short-term, 15–25% long-term), and define threshold (50% payout), target (100%), and stretch (150% cap) gates for each metric.
    3. Safeguards & clawback integration (Q3). Draft clawback, malus, and data-restatement clauses into the compensation agreements; require third-party verification (ISAE 3000) before any bonus authorization.
    4. Proxy disclosure & investor engagement (Q4). Draft the Compensation Discussion and Analysis for the annual proxy statement (DEF 14A) and engage major institutional investors and proxy advisory teams on the metric selection logic — before the vote, not after.
    5. Post-cycle verification & certification (year-end). Receive the assurance reports, have the Compensation Committee certify achievement against the disclosed design, apply any documented discretion, and authorize vesting.

    Built this way, an ESG-linked pay plan is defensible on the only ground that ultimately matters: the metrics were stated in advance, measured independently, and paid exactly as disclosed.

    Updated Nov 1, 2026 — added the free ESG-linked pay quick card, ESG-linked pay committee pack, and board pay bot book downloads to this guide.

  • CSRD Double Materiality for Real Estate: A Portfolio Implementation Guide

    CSRD Double Materiality for Real Estate: A Portfolio Implementation Guide

    Updated Nov 1, 2026 — added the free double materiality quick card, CSRD portfolio pack, and double materiality copilot downloads to this guide.

    Double materiality is where CSRD stops being a reporting exercise and becomes an underwriting input — and nowhere is that truer than in real estate. A building portfolio feels both lenses physically: impact materiality (inside-out) runs through emissions, construction waste, tenant health and the communities around each asset; financial materiality (outside-in) runs through net operating income, valuations, insurance and the cost of debt. Our CSRD compliance roadmap maps the directive’s scope and timelines after the 2026 Omnibus. This guide is the sector build that sits under it: how an asset manager actually runs the double-materiality assessment across a portfolio, maps the ESRS topical standards to property operations, solves the tenant-data problem, and arrives at disclosures that survive limited assurance.

    Instant Portfolio Implementation Downloads

    Operationalize CSRD Double Materiality Across Your Portfolio

    Field quick-reference cards, fillable calibration packs, and AI-run interrogation routines built directly from this guide to set defensible thresholds, solve tenant data gaps, and survive limited assurance.

    Field Quick Card
    FREE

    Double Materiality Quick Card

    2-page field card: The two lenses applied to buildings (inside-out impact vs. outside-in financial) plus the 5-point threshold calibration test and ESRS real estate map condensed onto one card.

    Download Free PDF

    Direct download • No email gate

    Working Field Pack
    $7

    CSRD Portfolio Pack

    Printable/fillable 7-page kit: 5-point threshold calibration sheet, ESRS topical matrix with Working metrics, physical transmission checklist, transition regulatory map, tenant 4-tier tracker, CapEx memo template, and 12-month runway planner.

    Get Portfolio Pack ($7) →

    Instant checkout • Square verified

    AI Intensive
    Book for Bots
    $17

    Double Materiality Copilot

    Feed to ChatGPT or Claude: 7-page executable prompt playbook running 5 AI routines (Threshold Setter, ESRS Portfolio Mapper, Tenant Data Auditor, Stranding & Valuation Underwriter, Assurance Lineage Tester) + embedded router.

    Get Copilot Book ($17) →

    Software made of words • Instant delivery

    The two lenses, applied to buildings

    Impact materiality asks what the portfolio does to people and the environment, across acquisition, development, management and tenant operations. Under ESRS 1, a negative impact is scored on severity — scale, scope and irremediable character — and, for potential impacts, likelihood, across short (1 year), medium (2–5 year) and long (up to 30 years for property) horizons.

    Financial materiality asks what sustainability developments do to the asset manager: the plausible variance in NOI, property valuations and NAV, required CapEx, insurance premiums and borrowing margins, weighted by probability over the same horizons. In real estate the two lenses share evidence — the same flood model that scores an impact scores a valuation haircut — which is why the assessment belongs in the investment process rather than beside it.

    Thresholds are yours to set and defend. ESRS prescribes the method, not a numeric cut-off. Many managers calibrate on a 5-point scale and treat topics scoring high on either lens as material; whatever boundary you choose, document it, apply it consistently, and expect the assurance provider to test topics that fell just below it.

    The ESRS map for a property portfolio

    Standard Impact focus (inside-out) Financial focus (outside-in) Working metrics
    E1 Climate Scope 1–2 emissions; Scope 3 from tenant energy and embodied carbon in construction Stranding under decarbonisation pathways (CRREM); physical-event depreciation; retrofit CapEx tCO₂e/m²/yr; CRREM stranding year per asset
    E2 Pollution Construction/maintenance runoff; VOCs and indoor air quality Remediation liabilities; fines; tenant-retention effects of poor IAQ Hazardous-material area (m²); PM2.5 / VOC monitoring
    E3 Water Consumption intensity; cooling-tower loss; stormwater discharge Utility cost escalation; drought restrictions on cooling m³/m²/yr; % water recycled
    E4 Biodiversity Greenfield land take; habitat disruption; urban heat island Permitting delay; offset obligations; constrained land pipeline % of portfolio in biodiversity-sensitive zones
    E5 Circular economy Construction and fit-out waste to landfill; low component reuse Material price volatility; disposal costs; end-of-life value loss Waste diversion rate; % certified reusable/low-carbon materials
    S1 Own workforce Property-management health & safety; fair pay Compensation liabilities; delay costs from incidents and labour shortage Lost-time injury frequency; pay-gap reporting
    S2 Value-chain workers Construction and contracted-services labour practices Contractor litigation; supply-chain disruption Tier-1 contractor audit compliance; grievance cases
    S3 Affected communities Displacement pressure; construction disruption Planning objections and consenting delays Consultations held; objection counts
    S4 End-users (tenants) Indoor air quality, thermal comfort, accessibility, building safety Vacancy, default risk, renewal pricing pressure Tenant satisfaction; indoor environmental quality indices
    G1 Governance Anti-bribery in permitting; transparent tenant billing; ethical procurement Enforcement actions; capital-raising reputation Anti-corruption training coverage; substantiated whistleblowing cases

    Where the money moves

    Physical risk transmits in a straight line: acute hazards (flood, storm, wildfire) and chronic stressors (heat, sea-level rise, water scarcity) damage the asset and interrupt operations; insurance reprices or withdraws; NOI falls while defensive CapEx rises; the capitalisation of a smaller, riskier income stream is a lower valuation. At the end of that line sit the two terminal states this site’s stranded-assets analysis works through in detail — assets whose protective CapEx exceeds their discounted cash flow, and assets the insurance market will no longer carry at any economic price.

    Transition risk is increasingly statutory. The recast Energy Performance of Buildings Directive (EU) 2024/1275 requires member states to renovate the worst-performing slice of the non-residential stock — 16% by 2030 and 26% by 2033 — with residential trajectories alongside; how leasing consequences attach is set nationally. Outside Europe the same logic arrives as direct carbon penalties: New York’s LL97 charges $268 per tonne over a building’s limit, with a good-faith mitigation path for owners who can document progress — the mechanics are in our fines calculator and DC BEPS pathways pieces. California’s SB 253/261 regime adds the disclosure layer for large operators — see the compliance playbook. A portfolio materiality assessment that ignores the regulatory map of each asset’s jurisdiction is scoring the wrong future.

    The tenant data problem

    For most portfolios, Scope 3 is the footprint — tenant energy use and embodied carbon in construction and fit-outs are commonly cited in the 70–90% range of the total — and it is the data the landlord does not meter, does not buy and often has no contractual right to see. Working portfolios climb a four-level hierarchy:

    1. Direct automated data — smart meters and automated utility feeds for whole-building consumption.
    2. Tenant aggregated data — consolidated monthly consumption shared at building level, privacy preserved.
    3. Green-lease protocols — lease clauses that make utility disclosure a standing obligation, paired with shared reduction targets and cost-recovery terms agreed before anyone is in breach.
    4. Benchmark estimation — engineering proxies (CRREM pathways, CIBSE benchmarks) filling the gaps, flagged as estimates in the lineage, and retired asset by asset as metering arrives.

    The hierarchy is also the assurance strategy: an auditor can accept a disclosed estimate with a documented method far more readily than a precise number with no provenance.

    Portfolio DMA & Scope 3 Toolkit

    Solve the Tenant Scope 3 Data Problem and Defend Limited Assurance

    Tenant energy consumption represents 70–90% of a property portfolio’s carbon footprint. Auditors do not demand immediate 100% smart-meter coverage — they demand a documented 4-level data hierarchy, defensible benchmark estimations, and auditable lineage. Whether you need printable hierarchy trackers and CapEx underwriting memo inserts, or an AI copilot to audit your lease clauses and map meter-to-XBRL provenance, equip your team with field-ready tools.

    ⚙

    What’s In The Portfolio Kit:

    • 5-Point Threshold Sheet: 1yr/2-5yr/30yr calibration.
    • ESRS Topical Matrix: E1-E5, S1-S4, G1 property metrics.
    • Transmission Chain: Hazard > Insurance > NOI > Valuation.
    • Jurisdiction Map: EPBD (16%/26%), LL97 ($268/t), BEPS.
    • Tenant Hierarchy: Automated > Aggregated > Lease > CRREM.
    • CapEx Memo Insert: Stranding year & funded plans.
    • Lineage Log & Runway: Months 1–12 XBRL roadmap.
    • Bot Copilot: 5 AI-run routines with embedded router ($17).
    Secure 1-Click Square Checkout

    Governance, lineage and assurance

    Wire the assessment into capital allocation, or it decorates a report nobody prices. The working pattern at serious platforms: every acquisition, disposition and major CapEx memo carries the asset’s double-materiality read — projected CRREM stranding year, required decarbonisation CapEx, physical-risk exposure — and assets scored high on transition risk arrive with a funded decarbonisation plan inside the underwriting, not as an appendix to it. Executive variable pay tied to verified portfolio emissions and energy-intensity outcomes (the mechanics our CRE program guide sets out) closes the loop between the assessment and behaviour.

    Assurance is a data-lineage test. CSRD reporting is subject to limited assurance, and what the assurance provider actually examines is provenance: raw meter readings and utility bills, through ingestion and validation, emission-factor application and pathway modelling, to the tagged disclosure — with version control, unit conversions and deviation sign-offs visible at each step. Reports are published in machine-readable form with Inline XBRL tagging of material metrics. Build the lineage as you collect, and the assurance engagement is a review; build it afterwards, and it is an excavation.

    A realistic 12-month runway: months 1–3, run the double-materiality assessment and secure investment-committee sign-off on thresholds; months 4–6, build the data architecture — automated ingestion, green-lease rollout, estimation models for the gaps; months 7–9, test controls with a mock assurance engagement and fix what it finds; months 10–12, produce the tagged report and take it through external limited assurance.

    Portfolio Product Comparison

    Compare Double Materiality Implementation Tiers

    Choose the operational tier that matches your portfolio’s reporting timeline and assurance readiness: quick reference card, printable working worksheets for asset managers, or an AI copilot to interrogate underwritings and trace data lineage.

    Field Summary

    Double Materiality Quick Card

    2-page field card condensing the two lenses, the 5-point threshold scale, and the real estate ESRS map onto one reference card.

    • Two-lens definition (Inside-Out Impact vs. Outside-In Financial)
    • 5-point threshold scale (severity, scope, irremediable, likelihood)
    • Real estate time horizons (1-yr, 2–5 yr, up to 30-yr property)
    • ESRS E1–E5, S1–S4, G1 core building metrics summary
    • Tenant Scope 3 4-level data hierarchy quick glance
    • Limited assurance test criteria for just-below topics

    FREE

    Download Quick Card (PDF)

    Instant direct download • No email gate

    Static Working Pack

    CSRD Portfolio Pack

    7-page printable & fillable operational toolkit for asset managers, investment committees, and ESG controllers.

    • 5-point threshold calibration sheet (scale, scope, irremediable)
    • ESRS E1–E5, S1–S4, G1 matrix with Working metrics
    • Physical transmission checklist (hazard > insurance > NOI > haircut)
    • Transition jurisdiction worksheet (EPBD, LL97, BEPS, SB 253/261)
    • Tenant-data 4-level hierarchy tracker & estimation flags
    • CapEx memo insert & funded decarbonisation plan template
    • Limited-assurance lineage log & 12-month runway planner
    • Signoff block for investment committee approval

    $7.00

    Get Portfolio Pack ($7) →

    Instant checkout • Square verified • Instant delivery

    AI Intensive
    Book for Bots

    Double Materiality Copilot

    7-page executable AI workbook: feed directly into ChatGPT or Claude to run interactive portfolio double materiality audits and disclosures.

    • Threshold Setter Interview (/threshold-setter): 5-point calibration
    • ESRS Portfolio Mapper (/esrs-mapper): E1–G1 topical mapping & flags
    • Tenant Hierarchy Auditor (/tenant-hierarchy): Leases, clauses & proxy retirement
    • Stranding & Valuation Underwriter (/stranding-underwriter): CRREM & terminal states
    • Assurance Lineage Tester (/assurance-tester): Meter-to-XBRL provenance check
    • Embedded Output Router: “Software made of words” runtime engine

    $17.00

    Get AI Copilot Book ($17) →

    Instant checkout • Square verified • Instant delivery

    Frequently asked questions

    After the Omnibus, is a mid-size asset manager even in CSRD scope?

    Possibly not directly — Omnibus I narrowed direct scope substantially, and our roadmap piece tracks the current thresholds and waves. But double materiality reaches most serious managers anyway: through in-scope funds and parent groups, through lender and investor diligence, and through the EPBD and national building regimes that apply asset by asset regardless of the manager’s reporting status. The methodology is the durable asset; scope is a moving boundary.

    Is CRREM mandatory under ESRS?

    No. ESRS E1 requires a transition plan and emissions disclosure; it does not name a pathway tool. CRREM is the sector’s standard decarbonisation-pathway framework — the stranding-year analysis assurance providers and lenders most readily recognise — which makes it the pragmatic default rather than a legal requirement.

    Do tenant emissions really belong in the landlord’s report?

    Yes, where material: energy used by tenants in leased space sits in the landlord’s Scope 3 (downstream leased assets), and for most portfolios it is the largest single block. Estimation is permitted — what is not defensible is omitting the category because metering is incomplete. Disclose the hierarchy level each asset’s data comes from.

    Limited or reasonable assurance — which should we prepare for?

    Limited assurance is the operative standard, and as amended by Omnibus I the regime stays there — the earlier planned escalation to reasonable assurance was removed. Prepare for limited assurance done properly: tested controls, traceable lineage, documented judgements. That preparation also happens to be most of what reasonable assurance would have demanded.


    Sources: ESRS 1 (General Requirements) double-materiality method; Directive (EU) 2024/1275 (EPBD recast) — non-residential minimum performance trajectories (16% of worst-performing stock by 2030, 26% by 2033); CRREM decarbonisation pathways for real estate; NYC Local Law 97 / 1 RCNY 103-14 ($268/tCO₂e); CSRD as amended by Omnibus I (Directive (EU) 2026/470) — limited assurance retained, reasonable-assurance escalation removed. Companion pieces: BC ESG’s CSRD compliance roadmap, CRE ESG program guide, DC BEPS pathways, LL97 fines calculator and California SB 253/261 playbook.

  • Social Licence to Operate: FPIC, Grievance Systems and the Real Cost of Losing a Community

    Social Licence to Operate: FPIC, Grievance Systems and the Real Cost of Losing a Community

    Updated Nov 1, 2026 — added the free SLO quick card, social licence keeper pack, and SLO operating system downloads to this guide.

    No regulator issues a social licence, and no regulator can restore one — which is exactly why it behaves like the hardest permit in the portfolio. A social licence to operate (SLO) is the standing a project holds with the people who live with it: landowners, municipalities, Indigenous nations, local businesses. It is granted continuously or withdrawn suddenly, and its withdrawal has a measured price. The canonical study of company–community conflict in the extractive sector (Davis & Franks, 2014) found that a major mining project in the US$3–5 billion capital class loses roughly US$20 million per week of delayed production in net-present-value terms when community conflict stops work — and recorded one company attributing more than US$6 billion over two years to non-technical risks. This guide sets out the operating system serious projects now run to keep the licence: live stakeholder mapping, FPIC done as a lifecycle rather than an event, grievance mechanisms built to the UN’s effectiveness criteria, environmental-justice integration, and metrics a board can audit.

    Instant Governance & Community Toolkit

    Master FPIC Protocols, Grievance Escalation & SLO Governance

    Field-tested stakeholder maps, UNGP Principle 31 effectiveness scorecards, 4-tier escalation clock logs, benefit-sharing calculators, and bot-ready AI operating systems built directly from this guide.

    Quick Reference
    FREE

    SLO Quick Card

    2-page field card: The five stakeholder groups with risk vectors, the model 4-tier grievance escalation ladder with target clocks (48–72h to ~14d), and the operator licence KPI matrix condensed onto one reference card.

    Download Free PDF

    Direct download • No email gate

    Working Pack
    $7

    Social Licence Keeper Pack

    Printable/fillable 7-page working pack: Stakeholder map with dynamic re-score log, FPIC 5-phase lifecycle checklist & validity tests sheet, UNGP Principle 31 8-criteria effectiveness scorecard, 4-tier grievance ladder with clock log, SLO KPI tracker, and 90-day start checklist.

    Get Keeper Pack ($7) →

    Instant checkout • Square verified

    AI Intensive
    Book for Bots
    $17

    SLO Operating System for AI

    Feed to ChatGPT or Claude: 8-page executable prompt playbook with 6 interactive AI routines (Stakeholder Mapper & Early-Warning Audit, FPIC Lifecycle Interview, Grievance Doctor, EJ & Benefit-Sharing Builder, Board Dashboard Generator, 90-Day Planner) plus embedded router.

    Get AI Operating System ($17) →

    Software made of words • Instant delivery

    Why the licence hardened

    Finance made it a covenant. Under the Equator Principles (EP4, followed by more than 120 financial institutions), project finance is assessed against the IFC Performance Standards — including Performance Standard 7’s requirement of Free, Prior and Informed Consent (FPIC) in defined circumstances affecting Indigenous Peoples. No FPIC process, no disbursement. IFC’s own Sustainability Framework is under review through roughly 2028, which means the expectations underneath those covenants are being rewritten in public — watch that process, not the rumour mill.

    Due-diligence law is coming — later, and narrower, than the headlines said. The EU’s CSDDD, as amended by Omnibus I (Directive (EU) 2026/470), now covers only very large companies (over 5,000 employees and €1.5 billion in net worldwide turnover) and applies from July 26, 2029. The harmonised EU civil-liability regime was removed. But the near-term force on projects is real anyway: in-scope buyers, lenders and public tenders are already flowing due-diligence and grievance-handling expectations down through contracts to operators well outside the directive’s direct scope.

    Disclosure pulls the rest. Under IFRS S1, social friction that is material — land-access disputes, stoppages, consent failures — belongs in investor-grade disclosure with the same discipline as any other enterprise risk. A licence problem that reaches the financial statements has, by definition, been visible on the ground for months. The gap between those two moments is what an SLO system exists to close.

    Map stakeholders like they move — because they do

    A static stakeholder register is obsolete the month it is printed. Working systems classify stakeholders by risk vector, influence and vulnerability, and re-score as the project and the community change:

    Stakeholder Primary risk vectors Influence Vulnerability Engagement mechanism
    Indigenous & tribal leadership Land rights, cultural heritage, water High High Formal FPIC protocols; binding benefit-sharing agreements
    Directly impacted landowners Devaluation, eminent domain, displacement Medium-high High Bilateral negotiation; independent valuation; compensation panels
    Local community & municipalities Traffic, dust, noise, service strain Medium Medium Town halls; liaison committees; local hiring commitments
    Regional environmental NGOs Biodiversity, cumulative impacts High Low-medium Technical workshops; open-data monitoring portals; third-party audits
    Local businesses & contractors Economic exclusion, wage inflation Low-medium Medium Procurement forums; vendor training; local-content commitments

    Sentiment tracking turns the map into an early-warning system. Mature operators combine three feeds: automated monitoring of hyper-local channels (community forums, municipal minutes, local media) rolled into a periodic sentiment index; structured field logs from community liaison officers, GIS-tagged so micro-grievances are visible before they organise; and threshold alerts that route a spiking topic — water quality, haul-road safety — to operations while it is still a topic and not yet a blockade. Treat any sentiment index as an internal instrument: its value is in the trend and the methodology’s consistency, not in the absolute number.

    FPIC is a lifecycle, not a signature

    Free, Prior and Informed Consent — anchored in UNDRIP (notably Article 32, on projects affecting Indigenous lands and resources) and operationalised for financed projects through IFC PS7 — runs in five phases:

    1. Initiation & trust-building — engagement before permit applications, on the community’s timetable.
    2. Participatory impact & heritage scoping — joint baseline studies that admit Indigenous knowledge as evidence, not colour.
    3. Deliberation & autonomous decision-making — the community’s own governance decides, uncoerced, including the right to say no or to set conditions.
    4. Binding agreement — an enforceable Impact-Benefit Agreement recording what was consented to, and what was not.
    5. Lifecycle monitoring & joint governance — co-management oversight and periodic re-validation; consent for a changed project is a new question.

    The validity tests are in the name: free (no coercion, intimidation or engineered division), prior (before authorisation, with real time for internal decision processes), informed (complete, independent, culturally appropriate disclosure in the community’s language), and consent (a collective decision through the people’s own mechanisms — including withholding it).

    Grievance mechanisms: the early-warning system with UN criteria

    An operational-level grievance mechanism (OGM) earns its keep when it resolves a dust complaint in 48 hours instead of letting it become the affidavit in an injunction. The benchmark is Principle 31 of the UN Guiding Principles on Business and Human Rights — eight effectiveness criteria: legitimate, accessible, predictable, equitable, transparent, rights-compatible, a source of continuous learning, and based on engagement and dialogue. A mechanism missing any one fails predictably: inaccessible mechanisms learn about grievances from journalists; unpredictable ones teach people that escalation works better than filing.

    A model escalation ladder, with target clocks an operator sets and then reports against:

    Tier Trigger Target clock Owner Tool
    1 — Operational Nuisance: dust, noise, traffic, minor damage 48–72 hours Community liaison officer Field remediation; direct compensation
    2 — Systemic Baseline deviation; water-access concern; contracting dispute ~14 business days Operations director + social performance lead Joint investigation; facilitated mediation
    3 — Strategic Land ownership; cultural-site impact; systemic health concern 30–45 days Executive steering committee + independent ombudsman Arbitration; third-party review; agreement renegotiation
    4 — External Unresolved fundamental-rights claims External mandate Board committee + counsel Judicial or international forum

    Operational Social Licence Toolkit

    Resolve Community Friction Before It Becomes a US$20M/Week Production Stoppage

    Major capital projects lose roughly US$20 million per week when community conflict halts operations (Davis & Franks, 2014). Equator Principle covenants (IFRS S1, EP4 / IFC PS7) make Free, Prior and Informed Consent non-negotiable. Whether you need printable grievance intake registers and UNGP 31 scorecards for site liaison officers, or an autonomous AI operating system that audits dispute escalations and drafts benefit-sharing term sheets, equip your team with field-proven operating tools.

    ⚙

    What’s In The Field Toolkit:

    • 5 Stakeholder Maps: Risk vectors & re-scoring.
    • FPIC 5-Phase Lifecycle: Free/Prior/Informed audit.
    • UNGP 31 Scorecard: 8 effectiveness tests.
    • 4-Tier Escalation Ladder: 48–72h to ~14d SLA clocks.
    • SLO KPI Register: Velocity ≥95%, 0 stoppage days.
    • Benefit-Sharing Term Sheets: 5–15% equity, 25–40% spend.
    Secure 1-Click Square Checkout

    Environmental justice and benefit-sharing

    Environmental justice asks who carries the burden, cumulatively. A cumulative impact assessment stacks the project’s effects on top of the background a community already lives with — prior industry, health disparities, infrastructure deficits — using tools such as the US EPA’s EJScreen and community mapping, so mitigation lands where the burden is: filtration where water is the issue, health services where exposure is the issue, scrubbers where air is the issue.

    Benefit-sharing converts neighbours into stakeholders. Observed practice in negotiated agreements includes community or Indigenous-trust equity stakes in the project vehicle (often in the 5–15% range), local and Indigenous procurement commitments (commonly 25–40% of addressable spend), and legacy development funds taking a small share of revenue (commonly 0.5–2%) into independent community trusts that outlive the project. These are practice ranges from real agreements, not standards — but the direction is unambiguous: value that stays local is the strongest known predictor of a licence that survives contact with a bad quarter.

    Measure the licence like an operator

    KPI Type Method Example target
    Grievance resolution velocity Leading Resolved within SLA ÷ total received (OGM logs) ≥ 95% in SLA
    Unplanned community stoppage days Lagging Hours of disruption from protest, blockade or injunction Zero
    Local procurement retention Leading Certified local vendor spend ÷ tier-1 procurement spend ≥ 30%
    FPIC re-validation Leading Periodic audit of consent verification with Indigenous councils Full compliance
    Community sentiment trend Leading Consistent-methodology index over local channels Stable or improving trend
    Cumulative EJ exposure Leading GIS overlay of air/water/noise exposure on vulnerable zones No severe disparities unmitigated

    Targets are the operator’s own — set them, publish performance against them internally, and let the trend do the talking. The one non-negotiable is the lagging indicator: stoppage days are the licence rendered as a number, and they belong in the same enterprise risk dashboard as safety and downtime.

    Two patterns from the field

    The cases below are composites drawn from recurring project patterns; the structures are real practice, the specifics are illustrative.

    Water and consent in minerals. A critical-minerals project adjacent to Indigenous land in a water-stressed basin opened with top-down permitting that bypassed traditional councils — and met organised opposition centred on groundwater drawdown and a culturally significant landscape. The recovery pattern: pause the drilling programme, stand up a co-designed water and cultural heritage board with equal Indigenous representation, commit to high-recycling extraction technology verified by independent sensors on a public dashboard, and close an Impact-Benefit Agreement with a royalty stream to a tribal trust and substantial local-employment commitments. Consent was re-established through the community’s own process — on the order of a year, not a news cycle — and the project proceeded without stoppages.

    Easements without eminent domain. A long-distance transmission line crossing a dozen agricultural counties faced coordinated landowner resistance framed as a corporate land grab. The recovery pattern: replace one-time eminent-domain payments with voluntary landowner partnerships — annual compensation linked to the line’s use — re-route segments using landowner feedback to avoid sensitive parcels, and fund a county-level community investment vehicle for the services lines actually strain (emergency response, road maintenance). Easements were secured overwhelmingly voluntarily, and the model has since been reused for linear grid projects in the region.

    A 90-day start

    Days 1–30 — baseline. Audit the current social footprint and spatial EJ exposure; stand up a UNGP-criteria grievance mechanism at every operating site; instrument sentiment and liaison logging. Days 31–60 — governance. Formalise FPIC protocols for high-risk assets; agree benefit-sharing templates with counsel before a negotiation forces improvisation; charter a cross-functional social performance committee. Days 61–90 — integration. Feed the SLO KPIs into enterprise risk reporting; publish open-data environmental monitoring for host communities; train site leadership on the escalation ladder until the first real grievance arrives — because it will, and the response to grievance number one sets the community’s prior for every grievance after it.

    Social Licence Product Comparison

    Compare Social Licence Tools & AI Systems

    Choose the operational tier that matches your project’s phase and stakeholder risk profile: quick field reference card, printable working pack for field liaisons, or an AI operating system that audits mechanisms, runs FPIC interviews, and generates board disclosures.

    Field Summary

    SLO Quick Card

    2-page field card condensing the stakeholder archetypes, grievance ladder, and operator KPIs onto one reference sheet.

    • The 5 core stakeholder groups & primary risk vectors
    • 3-feed sentiment tracking & early-warning architecture
    • 4-tier grievance escalation ladder & target clocks
    • The 6 operator-grade licence KPIs & targets
    • FPIC 5-phase lifecycle & the 4 validity tests
    • Benefit-sharing observed practice ranges

    FREE

    Download Quick Card (PDF)

    Instant direct download • No email gate

    Static Working Pack

    Social Licence Keeper Pack

    7-page printable & fillable operational toolkit for community liaison leads, social performance directors, and site managers.

    • Stakeholder map worksheet with dynamic re-score log
    • FPIC 5-phase lifecycle checklist (UNDRIP Art 32 / IFC PS7)
    • Free, Prior, Informed, Consent validity audit matrix
    • UNGP Principle 31 8-criteria grievance scorecard
    • 4-tier grievance intake register with SLA clock tracking
    • Enterprise SLO KPI tracker (velocity ≥95%, stoppage days zero)
    • Benefit-sharing register (5–15% equity, 25–40% spend)
    • 90-day implementation action checklist & signoff block

    $7.00

    Get Keeper Pack ($7) →

    Instant checkout • Square verified • Instant delivery

    AI Intensive
    Book for Bots

    SLO Operating System for AI

    8-page executable AI workbook: feed directly into ChatGPT or Claude to run interactive social performance and grievance management routines.

    • Stakeholder Mapper & Early-Warning (/stakeholder): Archetype triage
    • FPIC Lifecycle Interview (/fpic-interview): 5-phase validity audit
    • Grievance Doctor (/grievance-doctor): UNGP 31 audit & tier triage
    • EJ & Benefit-Sharing Builder (/ej-benefit): Cumulative overlay & term sheets
    • Board-Ready SLO Dashboard (/slo-dashboard): Stoppage NPV & IFRS S1
    • 90-Day Implementation Planner (/90day-plan): Gantt milestone schedule
    • Embedded Output Router: “Software made of words” runtime engine

    $17.00

    Get AI Operating System ($17) →

    Instant checkout • Square verified • Instant delivery

    Frequently asked questions

    Is a social licence a legal requirement?

    Not under that name — no statute issues one. Its components increasingly are legal: FPIC duties bind financed projects through the Equator Principles and IFC PS7 and bind states under UNDRIP-derived frameworks; due-diligence and disclosure regimes (CSDDD from 2029, IFRS S1 materiality today) reach the same conduct from other directions. The licence is the practical precondition that lenders, insurers and boards now price.

    What does losing community support actually cost?

    The best-measured figure remains Davis & Franks (2014): roughly US$20 million per week of delayed production, in NPV terms, for a world-class mining project in the US$3–5 billion capital class — before security, legal, financing and write-down costs. Their interviewees added the cost companies most often overlook: senior management time, up to and including the CEO’s, diverted to conflict management.

    Can consent be withdrawn after it is given?

    In practice, yes — that is the point of the lifecycle model. Consent attaches to a defined project, scope and set of conditions; material changes reopen the question, and joint-governance structures with periodic re-validation exist precisely so withdrawal is a governed conversation rather than a blockade. Agreements that pretend consent is a one-time, perpetual signature tend to discover otherwise.

    What makes a grievance mechanism credible to a community?

    The UN Guiding Principles’ eight tests (Principle 31): it is legitimate, accessible, predictable, equitable, transparent, rights-compatible, a source of continuous learning, and designed through engagement with the people expected to use it. Publishing aggregate outcomes — volumes, categories, resolution times — is the transparency step most mechanisms skip and communities notice most.


    Sources: Davis, R. & Franks, D.M. (2014), “Costs of Company-Community Conflict in the Extractive Sector,” PNAS / Harvard Kennedy School CSR Initiative (US$20M per week, US$3–5B capital class; >US$6B two-year non-technical-risk attribution); UN Guiding Principles on Business and Human Rights, Principle 31; UNDRIP Art 32; IFC Performance Standard 7 and the IFC Sustainability Framework review (2024–2028); Equator Principles EP4; Directive (EU) 2026/470 (Omnibus I) amending the CSDDD — scope >5,000 employees and >€1.5B turnover, application July 26, 2029; IFRS S1. Benefit-sharing percentages are observed practice ranges from negotiated agreements, not regulatory standards; the two field cases are composites.

  • Responsible AI Meets ESG Reporting: The AI Act’s Real Timeline, Audit Metrics and Compute Accounting

    Responsible AI Meets ESG Reporting: The AI Act’s Real Timeline, Audit Metrics and Compute Accounting

    Updated Nov 1, 2026 — added the free AI Act timeline quick card, responsible AI + ESG evidence pack, and audit & accounting playbook downloads to this guide.

    AI governance and ESG reporting have merged into a single evidence problem. The sustainability report now has to describe how models are governed; the AI governance file now has to carry environmental numbers — energy per workload, water per facility, emissions per training run. In Europe both halves run on law: the EU AI Act (Regulation (EU) 2024/1689) supplies the governance machinery, and CSRD/ESRS plus the ISSB baseline supply the disclosure frame. What the regimes jointly demand is not policy prose but records: logs, metrics, lineage, incident clocks. This guide lays out the timeline as it actually stands after the 2026 Digital Omnibus moved it, the audit metrics that generate defensible evidence, and the compute accounting that connects AI to the E in ESG.

    Instant Governance & ESG Downloads

    Master Responsible AI & EU AI Act Governance

    Field-tested statutory timeline cards, Article 50 transparency checklists, Article 27 FRIA worksheets, AIR 0.80 bias audit logs, green compute calculators, and bot-ready compliance playbooks built directly from this guide.

    Quick Reference
    FREE

    AI Act Timeline Quick Card

    2-page field card: The amended statutory timeline on one card — Feb 2 2025, Aug 2 2025, Aug 2 2026 (Art. 50 + GPAI enforcement), Dec 2 2027 (Annex III high-risk), Aug 2 2028 (Annex I) plus the Dec 2026 grace note, each with what it switches on.

    Download Free PDF

    Direct download • No email gate

    Working Pack
    $7

    Responsible AI + ESG Evidence Pack

    Printable/fillable 7-page working pack: Amended timeline card, Art. 50 C2PA machine-readable marking log, Art. 27 FRIA worksheet, AIR 0.80 freeze rule log, 6-month WORM logs, <0.85 escalation circuit, Art. 73 incident clock drill sheet, and compute carbon worksheet.

    Get Evidence Pack ($7) →

    Instant checkout • Square verified

    AI Intensive
    Book for Bots
    $17

    AI Audit & Accounting Playbook

    Feed to ChatGPT or Claude: 8-page executable playbook with 6 interactive AI routines (Model Inventory Interview, Art. 50 Transparency Auditor, FRIA Scoping, Bias & Logging Audit, Incident Clock Drill, Compute Accounting Generator) plus embedded router.

    Get AI Playbook ($17) →

    Software made of words • Instant delivery

    The timeline, as amended

    Date What applies
    Feb 2, 2025 Prohibited practices banned; AI literacy duties live
    Aug 2, 2025 General-purpose AI (GPAI) model obligations apply
    Aug 2, 2026 Article 50 transparency applies — users told they are interacting with AI; synthetic content marked machine-readably. The Commission’s GPAI enforcement and fining powers also begin
    Dec 2, 2027 Annex III high-risk obligations — deferred 16 months by the Digital Omnibus on AI (Regulation (EU) 2026/1744, in force July 27, 2026)
    Aug 2, 2028 Annex I high-risk (AI inside regulated products) — also deferred by the Omnibus

    The Omnibus lesson generalises: dates move; substance doesn’t. The high-risk duties arriving in December 2027 are the same duties that were due in August 2026 — risk management (Art 9), data governance (Art 10), record-keeping (Art 12), human oversight (Art 14), post-market monitoring (Art 72). Organisations that read the deferral as a holiday will rebuild in a panic; organisations that read it as schedule relief will arrive with evidence that has already run in production. Note what did not move: Article 50 transparency is live now, and systems already on the market before August 2026 have only a short grace — to December 2026 — to bring content-marking into line.

    The governance skeleton

    Accountability. A cross-functional AI governance body (sustainability, AI engineering, security, legal) over a three-lines model: system owners in the first line log risk and lineage as they build; risk and compliance in the second line validate independently, set bias thresholds and own the model risk taxonomy; internal audit in the third line tests whether the controls work. A RACI per deployed model — production, fine-tuned and API-integrated alike — is the artefact that makes accountability inspectable rather than asserted.

    Risk classification and impact assessment. Every system is tiered against the Act’s categories (prohibited / high-risk / transparency / minimal). Fundamental Rights Impact Assessments (Art 27) are mandatory for specified deployer classes — public bodies and deployers of certain Annex III systems such as credit scoring and insurance pricing — and are sound practice well beyond that set. Threat modelling for AI-specific attacks (prompt injection, data poisoning, membership inference) belongs in the same file.

    Data governance. Lineage manifests that record origin, licence, consent attributes and transformations for training, fine-tuning and RAG corpora; automated scanning for personal data, copyrighted material and known bias patterns; and validation that synthetic data has not amplified the skew it was meant to dilute.

    Transparency. Article 50 executed technically, not rhetorically: machine-readable marking of synthetic outputs (C2PA content credentials are the working standard), interaction disclosure at the point of use, and model cards that state architecture, intended use, boundaries and known limitations.

    Human oversight. Human-in-the-loop approval for high-consequence decisions (credit, hiring screens, medical triage, tenancy decisions); human-on-the-loop monitoring with real override capability elsewhere; and — the part programmes skip — operator training and rotation designed against automation bias and fatigue, because an overseer who rubber-stamps is a control that exists only on paper.

    Post-market monitoring and the incident clock. Runtime telemetry on output distributions, drift and guardrail triggers; re-validation on defined drift thresholds; and an incident pipeline wired to Article 73’s tiered deadlines: report immediately once a causal link is established, and in any event within 15 days — 10 days where a death may have been caused, 2 days for widespread infringements or serious disruption of critical infrastructure. Those clocks ride with the high-risk regime, and they are days, not the 72 hours GDPR trained everyone to expect.

    Audit metrics: evidence, quantified

    Fairness metrics — with their anchors stated honestly. The Adverse Impact Ratio (selection rate of a protected subgroup ÷ selection rate of the benchmark group) carries the one genuinely regulatory threshold in this field: below 0.80 breaches the four-fifths rule from US employment practice and should freeze the workflow pending investigation. The other common metrics — equalized odds difference (working target ≤ 0.05), demographic parity difference (≤ 0.10), toxicity classifiers (a < 1% flag rate as an internal clean baseline) — are practitioner thresholds: defensible, widely used, and chosen by the operator rather than imposed by a regulator. An audit file that distinguishes the two kinds reads as credible; one that dresses internal targets as law does not.

    Logging — the substrate everything else stands on. For high-risk systems the Act’s record-keeping (Art 12, with deployer duties in Art 26) expects automatic event logs retained at least six months. A working log record carries: timestamp, model ID and exact version, prompt and response hashes, confidence scores, and guardrail flags. Retention on write-once storage is an implementation choice that earns its cost the first time a supervisor asks for an unaltered history.

    Escalation circuits. Low-confidence or guardrail-tripped outputs route to a human reviewer, and the review itself is logged — reviewer ID, decision, rationale code, response time. An illustrative trigger bound is a confidence score under 0.85; the number matters less than the property that the circuit is automatic, recorded and tested.

    Responsible AI + ESG Toolkit

    Bridge the Gap Between Responsible AI Governance and ESG Assurance

    AI compliance under the EU AI Act and corporate ESG assurance under CSRD ESRS E1/S1/G1 have merged into a single evidence problem. Regulators and external certifiers demand immutable WORM logs, verified C2PA provenance manifests, quantitative AIR 0.80 bias tests, and defensible Scope 2/3 compute accounting. Equip your compliance and risk teams with structured working sheets, incident response clocks, and bot-ready audit routines that calculate exact fine exposures and assurance-grade disclosures.

    ⚙

    What’s In The Evidence Toolkit:

    • Amended AI Act Timeline: Feb 2025 to Aug 2028.
    • Art. 50 Transparency & C2PA: Provenance marking log.
    • Art. 27 FRIA Scoping: Mandatory cases vs good practice.
    • AIR 0.80 Freeze Rule: Four-fifths bias threshold log.
    • 6-Month WORM Audit Logs: <0.85 escalation circuit.
    • Art. 73 Incident Drill: 15/10/2-day reporting clocks.
    • Green Compute Ledger: Operational & embodied carbon.
    Secure 1-Click Square Checkout

    The E pillar: compute accounting

    AI’s environmental ledger has two entries — the carbon embodied in hardware, and the carbon emitted running it — and ESG reporting increasingly wants both, at workload granularity.

    • Operational carbon = energy consumed (kWh) × grid emission factor (gCO₂e/kWh) × PUE. Location-based and market-based figures both belong in the file; they answer different questions.
    • Embodied carbon = the hardware’s manufacturing footprint amortised over the share of its lifespan a workload consumes — (production emissions) × (allocated compute hours ÷ total hardware life). GPUs, HBM and accelerators make this entry material for training-heavy estates.
    • Efficiency units make the numbers governable: energy per training run, and for inference, kWh per 1M tokens (or per 1,000 queries). Efficient frontier systems operate in the region of 0.15 kWh per 1M tokens and below; treat that as a frontier marker for procurement conversations, not an industry average.
    • Facility multipliers: PUE at or below 1.2 is best-in-class hyperscale performance (industry averages sit nearer 1.5); WUE carries the water side — our data-center water guide sets out that method in full.

    Under CSRD this lands in ESRS E1 (energy and emissions) with water in ESRS E3; under the ISSB baseline it enters through S1/S2 materiality. Either way, the telemetry pipeline is the same one the AI Act’s monitoring duties require — build it once, report it twice. And the emissions accounting discipline is the same one our Scope 3 guide applies to vendors: AI compute bought from cloud providers is a purchased service, and its data quality will be graded like everyone else’s.

    One programme, three frameworks

    Dimension EU AI Act ISO/IEC 42001:2023 NIST AI RMF Evidence
    Governance & policy Arts 9, 50 Clauses 5–6; Annex A.2–A.3 Govern Board minutes; AI policy; RACI
    Risk & impact Arts 9, 27 (FRIA) Clause 6.1; Annex A.5 Map, Measure FRIAs; threat models; risk register
    Data & bias Art 10 Annex A.7 Map, Measure Lineage manifests; AIR reports; consent logs
    Transparency Art 50 Annex A.8 Manage C2PA marking logs; model cards; disclosure UX
    Logging & monitoring Arts 12, 72 Clause 9; Annex A.9 Measure, Manage ≥6-month logs; drift telemetry; HITL records
    Compute & ESG ESRS E1/E3 alignment Clause 8; Annex A.6 Govern, Measure Emissions logs; WUE/PUE reporting

    The roadmap to December 2027

    Now — scope and classify. Inventory every model: in-house, fine-tuned, vendor API, embedded feature. Tier each against the Act; register the Article 50 population (already live); gap-analyse against ISO 42001 and the NIST framework. Through 2027 — build the evidence machinery. WORM-retained logging, continuous bias evaluation, HITL circuits, and the compute telemetry feed into sustainability reporting. Before December 2, 2027 — high-risk readiness. Technical documentation suites, FRIAs, quality management, and a mock conformity assessment with an external body while mistakes are still cheap. The Omnibus bought sixteen months; the programmes that use them as build time will experience the deadline as a filing exercise. The ones that don’t will experience it as an incident.

    Responsible AI & ESG Product Comparison

    Compare Governance Tools & AI Audit Systems

    Choose the operational tier that matches your organization’s regulatory readiness and audit posture: quick statutory timeline reference, printable/fillable evidence logs, or an autonomous AI playbook that runs interviews, tests thresholds, and generates audit dossiers.

    Field Summary

    AI Act Timeline Quick Card

    2-page field card condensing the amended EU AI Act statutory calendar onto one reference sheet.

    • Feb 2, 2025: Art. 5 prohibited AI bans & Art. 4 literacy
    • Aug 2, 2025: GPAI governance rules & codes of practice
    • Aug 2, 2026: Art. 50 transparency & GPAI enforcement
    • Dec 2, 2027: Annex III standalone high-risk systems
    • Aug 2, 2028: Annex I harmonized product safety systems
    • Dec 2026 GPAI transition grace period note

    FREE

    Download Quick Card (PDF)

    Instant direct download • No email gate

    Static Working Pack

    Responsible AI + ESG Evidence Pack

    7-page printable & fillable operational toolkit for compliance directors, risk leads, and ESG assurance controllers.

    • Amended AI Act timeline card with statutory milestones
    • Art. 50 transparency checklist & C2PA machine-marking log
    • Art. 27 FRIA scoping worksheet (credit, insurance, public bodies)
    • Bias & logging evidence log (AIR 0.80 freeze rule)
    • Equalized odds ≤0.05 & demographic parity ≤0.10 logs
    • 6-month WORM audit log fields & <0.85 escalation circuit
    • Art. 73 incident clock drill sheet (15/10/2-day clocks)
    • Compute carbon accounting worksheet (ESRS E1/E3 mapping)

    $7.00

    Get Working Pack ($7) →

    Instant checkout • Square verified • Instant delivery

    AI Intensive
    Book for Bots

    AI Audit & Accounting Playbook

    8-page executable AI workbook: feed directly into ChatGPT or Claude to run interactive AI governance and ESG assurance workflows.

    • Model Inventory & Tiering Interview (/inventory): Art. 5, Annex III/I
    • Art. 50 Transparency Auditor (/transparency): C2PA & watermarking
    • FRIA Scoping Walkthrough (/fria): Art. 27 mandatory test suite
    • Bias & Logging Audit (/bias-audit): AIR 0.80, EqOdds, WORM trails
    • Incident Clock Drill (/incident-drill): Art. 73 tabletop clocks
    • Compute Accounting Generator (/compute-esg): ESRS E1/E3 ledger
    • Embedded Command Router: Instant execution switches for your bot

    $17.00

    Get AI Playbook ($17) →

    Software made of words • Instant delivery

    Frequently asked questions

    Did the Digital Omnibus cancel the AI Act’s high-risk duties?

    No — it moved them. Regulation (EU) 2026/1744 deferred Annex III standalone high-risk obligations to December 2, 2027 and Annex I embedded systems to August 2, 2028. The substantive obligations are unchanged, Article 50 transparency was not deferred, and GPAI duties have applied since August 2025.

    How fast must a serious AI incident be reported?

    Under Article 73: immediately once a causal link (or its reasonable likelihood) is established, and no later than 15 days after awareness — 10 days where a death may have been caused, and 2 days for widespread infringements or serious, irreversible disruption of critical infrastructure. An incomplete initial report is permitted, with supplements to follow.

    Is a Fundamental Rights Impact Assessment required for every model?

    No. Article 27 mandates FRIAs for specified deployers — public-law bodies and deployers of particular Annex III systems (notably creditworthiness evaluation and life/health insurance pricing). Running them more broadly is good practice; claiming the Act requires them universally is not accurate.

    Do we have to disclose the energy our AI uses?

    If you are in CSRD scope, energy and emissions data — including material compute — belongs in ESRS E1 reporting; ISSB reporters reach the same place through materiality. Even out of scope, the procurement direction is clear: enterprise customers increasingly demand per-workload energy and emissions figures from AI vendors, and the vendors who can produce them win the diligence round.


    Sources: Regulation (EU) 2024/1689 (EU AI Act), Arts 9, 10, 12, 14, 26, 27, 50, 55, 72, 73; Regulation (EU) 2026/1744 (Digital Omnibus on AI), OJ July 24, 2026 — Annex III to Dec 2, 2027, Annex I to Aug 2, 2028; European Commission draft guidance on serious-incident reporting (Sep 2025) and law-firm analyses (Latham & Watkins; Paul Weiss); ISO/IEC 42001:2023; NIST AI RMF 1.0 and NIST AI 600-1 (GenAI Profile); EEOC Uniform Guidelines four-fifths rule; ESRS E1 and E3. Thresholds identified as practitioner targets are operator-chosen benchmarks, not regulatory requirements.

  • Physical Climate Risk for Manufacturing Assets: Hazard Mapping, Expected-Loss Valuation and Tier-N Supply Chains

    Physical Climate Risk for Manufacturing Assets: Hazard Mapping, Expected-Loss Valuation and Tier-N Supply Chains

    Updated Nov 1, 2026 — added the free physical risk quick card, manufacturing audit pack, and climate risk operator downloads to this guide.

    Physical climate risk work has moved from coloured maps to auditable numbers. Screening a portfolio in broad regional bands no longer satisfies IFRS S2, ESRS E1 or California’s SB 261 — nor a lender, an insurer or an acquirer doing diligence. What replaced it is an asset-level method: hyper-local hazard data at the facility’s coordinates, vulnerability assessed against the specific processes inside the fence, and the results carried into valuation as expected losses rather than as narrative. This guide sets out that method for manufacturing portfolios — the hazard taxonomy, the expected-annual-loss architecture, the business-interruption arithmetic, and the tier-N supply-chain mapping where most of the real exposure hides. (Two companions: physical risk for data centers, and the insurance-to-write-down pathway in our stranded-assets guide.)

    Instant Manufacturing Risk Downloads

    Physical Climate Risk for Manufacturing: Quick Card, Audit Pack & AI Operator

    Auditable 0.05° hazard screening grids, catastrophe-modeling EAL DCF worksheets, WACC no-double-count protocols, and machine-executable AI bot playbooks built directly from published asset-level engineering standards.

    Quick Reference
    FREE

    Physical Risk Quick Card

    2-page field card: acute vs chronic hazard taxonomy, return-period damage mechanisms, and quick-reference threshold values (0.5m / 1.5m flood, low-30s°C Tw + 35°C limit, BWS >40% / >80%, 0.5–0.7%/°C turbine derate, 40°C dry-bulb) on one card.

    Download Free PDF

    Direct download • No email gate

    Working Pack
    $7

    Manufacturing Physical Risk Audit Pack

    5-sheet printable working pack: SSP horizon planner (2026–2060), 0.05° asset check, acute/chronic hazard register, EAL DCF valuation worksheet, WACC no-double-count audit, BI downtime calculator, and Tier-N cascade mapper.

    Get Audit Pack ($7) →

    Instant checkout • Square verified

    AI Intensive
    Book for Bots
    $17

    Manufacturing Climate Risk Operator

    Feed to ChatGPT or Claude: 8 AI-run routines (/horizon, /hazard, /chronic, /eal, /wacc-audit, /bi-calc, /insurance, /tier-n, /all) with embedded output router to screen coordinates, build EAL curves, test impairment, and trace supplier bottlenecks.

    Get Operator ($17) →

    Software made of words • Instant delivery

    The frame: scenarios and horizons

    Run the assessment on CMIP6 projections under three Shared Socioeconomic Pathways — SSP1-2.6, SSP2-4.5 and SSP5-8.5 — because each planning decision lives on a different clock:

    Horizon Window Decisions it informs
    Near term 2026–2030 Operating budgets, insurance placement, immediate supply-chain resilience
    Medium term 2031–2040 Mid-life plant upgrades, CapEx sequencing, supplier consolidation
    Long term 2041–2060 Useful-life and depreciation policy, greenfield siting, terminal value

    Hazard data must resolve to the asset — grid scales around 0.05° (≈5 km) are the working standard — because micro-geography decides outcomes: two plants in the same river basin can sit metres apart in elevation and categories apart in risk.

    The hazard taxonomy

    Acute hazards arrive as events; chronic stresses arrive as drift. Both belong in the same register.

    Acute. Pluvial and fluvial flooding — evaluated at 100- and 500-year return periods against depth thresholds that map to damage mechanisms (as working heuristics, ~0.5 m reaches electrical infrastructure; ~1.5 m begins displacing heavy equipment). Tropical cyclones and storm surge — Category 4/5 wind fields plus surge height against roof, cladding and outdoor-storage tolerances. Wildfire and smoke — WUI proximity for direct exposure, and particulate episodes for the indirect one: extreme smoke events force filtration and cleanroom responses well beyond the fire perimeter.

    Chronic. Wet-bulb heat — the combined heat-humidity measure that governs both human labour and evaporative cooling. Labour productivity falls steeply as wet-bulb temperatures climb through the low 30s °C; occupational work/rest regimes are specified in WBGT standards rather than wet-bulb directly, and 35°C wet-bulb stands as the physiological survivability limit for sustained exposure. Baseline water stress — the WRI Aqueduct ratio of withdrawals to renewable supply: High above 40%, Extremely High above 80%, with allocation caps and tariff escalation following the classification. Thermal efficiency degradation — the quiet tax: gas turbines lose roughly 0.5–0.7% of output per °C above their 15°C ISO rating, and chillers, cooling towers and steam systems derate on the same physics.

    Hazard Working metric Assets most exposed Mechanism
    Pluvial/fluvial flood Peak depth at 100-yr return Fabs, automotive assembly Sub-fab equipment inundation; cleanroom loss; short circuits
    Wet-bulb heat Consecutive days in low-30s °C Tw Heavy industry, textiles, outdoor refining Labour capacity loss; cooling-tower derating; electronics trips
    Water stress Aqueduct BWS (>80% = extreme) Pharma, wafer processing, beverages Intake rationing; recycling CapEx; output constraints
    Storm surge Surge height above MSL Coastal chemicals, port terminals Corrosion; tank displacement; logistics shutdown
    Thermal shift Days above 40°C dry-bulb Precision machinery, plastics Cooling energy surge; material warping; grid trips

    From hazard to value: expected annual loss

    The valuation bridge is the catastrophe-modelling identity: Expected Annual Loss = Σ over hazards of ∫ probability(h) × vulnerability(h) × exposed value. Probability comes from the hazard curves; vulnerability is the damage function for this asset type at that intensity (a cleanroom’s curve looks nothing like a warehouse’s); exposed value is replacement cost plus the gross margin the asset carries. EAL then enters the DCF where it belongs — as a deduction inside free cash flow, alongside the adaptation CapEx the risk justifies — and into terminal assumptions through shortened useful lives.

    One discipline separates credible practice from decoration: do not charge for the same risk twice. A common practitioner shortcut adds a blanket “climate premium” to WACC on top of EAL-adjusted cash flows. If expected losses already sit in the cash flows, a general discount-rate premium double-counts them; a premium is defensible only for the residual that cannot be modelled — and it should be argued as such, in the open, rather than applied as a band. Auditors probe this seam, and they are right to.

    Impairment follows the same evidence. Under IAS 36 and ASC 360, physical hazards are impairment indicators: chronic stress shortens useful lives (accelerating depreciation), recurring events can strand a facility outright where retrofit cost exceeds remaining discounted cash flows, and the recoverable-amount test prices what is left. The mechanics are in the companion guide; the manufacturing-specific point is that the inputs — EAL curves, derating schedules, water rationing scenarios — are engineering artefacts, and the audit file should contain them, not summaries of them.

    EHS, Finance & Valuation Tools

    Model Asset-Level Expected Losses & Defend Your WACC Against Audit Scrutiny

    The catastrophe-modelling identity (EAL = Σ ∫ probability × vulnerability × exposed value) bridges asset-level hazard curves directly into free cash flows and IAS 36 / ASC 360 impairment tests. But applying a blanket “climate premium” to WACC on top of EAL cash-flow deductions double-counts the same risk — a primary red flag for external auditors and valuation committees. Use our printable 5-sheet working pack to model asset-level EAL curves and document residual-only discount rate adjustments, or deploy the AI Climate Risk Operator to automate hyper-local coordinate screening, DCF cash-flow integration, and audit-file generation.

    ☑

    What’s In The Toolkit:

    • 0.05° Grid Screener: Hyper-local asset coordinates.
    • EAL Valuation Table: Prob × vuln × exposed value into DCF.
    • WACC Double-Count Audit: Cash flow vs residual discount.
    • IAS 36 / ASC 360 Sheet: Impairment & useful-life triggers.
    • BI Arithmetic Sheet: Downtime days & spot surge costs.
    • 3-Layer Insurance Sizer: Parametric, property & tail reserve.
    • AI Bot Book ($17): 8 AI routines + prompt router.
    Secure 1-Click Square Checkout

    Business interruption: the larger number

    Structural damage is usually the smaller loss; downtime is the larger. Working form: BI exposure = (downtime days × daily fixed costs) + (lost units × unit margin) + surge costs. Surge costs are where inexperienced models fail: spot electricity during scarcity events can multiply several-fold (ERCOT-style pricing makes the arithmetic vivid), emergency water arrives by tanker at punitive rates, and air-freight premiums replace every weather-broken shipping leg at once. A facility can be physically untouched by a regional event and still post its worst quarter of the decade through this line alone.

    Insurance layering for what remains

    As carriers reprice or exit (the retraction mechanics are detailed in the stranded-assets guide), industrial portfolios increasingly carry risk in three layers. Parametric cover takes the fast-liquidity slice — payouts on objective triggers, typically within weeks, no adjustment process. Traditional property/BI programmes carry the insurable core, at repriced terms. The residual — risks no market will write — goes to an enterprise self-insurance reserve, sized off tail loss (a common formulation: the high-percentile expected tail loss minus maximum commercial payouts). That reserve is real capital standing idle against weather, which is why it belongs in the valuation conversation and not only the insurance one: it is a cash drag with a climate cause, and Phase-gated adaptation spending is how it shrinks.

    Tier-N: where the cascade starts

    Owned-asset analysis is the smaller half of manufacturing exposure. The 2011 Chao Phraya floods remain the canonical lesson: Thai industrial estates inundated, the global hard-drive industry — concentrated there — short for quarters, and OEMs on other continents stopped by a component they did not know was geographic. Map the tiers with the same hazard screen as owned assets:

    Node Hazard Bottleneck Mitigation
    Wafer fabrication (tier 2/3) Water stress, heat Continuous ultra-pure water demand — millions of gallons a day for a large fab; intake cuts force throttling fast Closed-loop recycling; dual-region supplier qualification
    Specialty polymers (tier 1) Gulf Coast hurricanes Single-source precursor and resin capacity — the 2021 Texas freeze idled resin production for months Safety stock (~60 days on critical grades); alternate synthesis agreements
    Barge freight Low river water Rhine/Mississippi draft limits — low water at critical gauges can halve barge loads or worse Dynamic modal-shift contracts; secondary-hub inventory
    Port terminals Storm surge, wind Cranes suspend operations well below hurricane-force winds; multi-day closures queue vessels for weeks Port diversification; pre-negotiated off-dock storage

    The recurring structure: concentration that was purchased as efficiency reprices as fragility. Dual-sourcing, buffer stock and modal-shift contracts all cost money in ordinary years — the EAL framework is what lets a company show, in numbers a CFO accepts, what those costs buy.

    Choose Your Manufacturing Climate Risk Toolkit

    Select the asset-level assessment, valuation, and supply-chain resource that matches your facility diligence, insurance placement, or financial reporting needs:

    Free Field Summary

    Physical Risk Quick Card

    2-page field card: the article’s acute vs chronic hazard taxonomy, return-period damage mechanisms, and quick-reference threshold values condensed onto one reference card.

    FREE
    direct download
    • Acute Hazard Register (100/500-yr flood, Cat 4/5 cyclone/surge, WUI/smoke)
    • Chronic Stress Drift (Wet-bulb Tw, Aqueduct BWS, thermal derate)
    • Inundation Damage Heuristics: ~0.5 m electrical, ~1.5 m heavy equipment
    • Wet-Bulb Thresholds: low-30s °C labour loss & 35 °C survivability limit
    • Water Scarcity Caps: WRI Aqueduct BWS >40% (High) & >80% (Extreme)
    • Thermal Efficiency Derating: 0.5–0.7% output loss per °C above 15 °C ISO

    Download Free PDF

    Working Pack

    Manufacturing Physical Risk Audit Pack

    Printable, fillable 5-sheet working pack with SSP scenario planners, 0.05° grid check sheets, EAL DCF valuation models, WACC logs, and Tier-N cascade matrices.

    $7.00
    one-time
    • SSP Horizon Planner (2026–2030, 2031–2040, 2041–2060 Windows)
    • 0.05° (≈5 km) Grid Resolution & Micro-Geography Elevation Check
    • Complete Acute vs Chronic Hazard Register with Working Metrics
    • EAL Valuation Model: ∫ P(h) × V(h) × Exposure + DCF Integrator
    • No-Double-Count WACC Audit Protocol & Residual-Only Premium Log
    • IAS 36 & ASC 360 Impairment Indicator & Useful-Life Review Sheet
    • Business Interruption Formula Sheet with Spot Energy & Water Surge Costs
    • 3-Layer Insurance Sizing Model (Parametric, Property/BI, Tail Reserve)
    • Tier-N Supplier Cascade Matrix (Wafer fabs, polymers, barges, ports)

    Buy Audit Pack ($7) →

    AI Intensive
    Book for Bots

    Manufacturing Climate Risk Operator

    Structured 8-page AI playbook for ChatGPT and Claude: 8 autonomous routines, EAL valuation engines, WACC double-count auditors, and Tier-N cascade mappers.

    $17.00
    one-time
    • Routine 1: SSP Horizon & Scenario Setter (/horizon)
    • Routine 2: Hyper-Local Hazard & 0.05° Coordinate Screener (/hazard)
    • Routine 3: Chronic Stress & Thermal Derating Rater (/chronic)
    • Routine 4: EAL Valuation Builder & DCF Deduction Engine (/eal)
    • Routine 5: WACC Double-Count & IAS 36 Impairment Auditor (/wacc-audit)
    • Routine 6: Business Interruption & Spot Surge Pricing Calculator (/bi-calc)
    • Routine 7: 3-Layer Insurance & Tail Reserve Designer (/insurance)
    • Routine 8: Tier-N Bottleneck & Supply-Chain Cascade Mapper (/tier-n)
    • Multi-Turn Prompt Router & Comprehensive Facility Audit (/all)

    Buy Operator ($17) →

    All payments securely processed by Square • Apple Pay, Google Pay & Corporate Cards Accepted

    Frequently asked questions

    What is Expected Annual Loss, in one sentence?

    The probability-weighted average of what physical hazards will cost an asset per year — hazard probability times asset vulnerability times exposed value, summed across hazards — used as a cash-flow deduction in valuation and as the sizing basis for insurance and reserves.

    Should we add a climate premium to WACC as well?

    Not on top of EAL-adjusted cash flows for the same risks — that double-counts. A discount-rate premium is defensible only for identified risks that cannot be modelled into cash flows, and the file should say which risks those are.

    How is wet-bulb temperature different from the heat index we use for worker safety?

    Worker-safety regimes are generally specified in WBGT (wet-bulb globe temperature), which adds solar load to the wet-bulb reading. Wet-bulb temperature itself governs evaporative cooling performance and marks the physiological limit — sustained exposure near 35°C wet-bulb is not survivable. The two metrics are related, not interchangeable, and conflating them produces wrong thresholds in both directions.

    Our plants are fine — why map suppliers the same way?

    Because the cascade does not respect your fence line. The 2011 Thailand floods stopped production on other continents through tier-2 and tier-3 concentration. Supplier nodes get the same hazard screen, the same scenario set, and mitigation priced through the same expected-loss logic.


    Sources: CMIP6 / SSP scenario framework; WRI Aqueduct 4.0 baseline water stress; catastrophe-model EAL architecture (hazard × vulnerability × exposure) as standard practice in insurance and climate-valuation literature; IAS 36 / ASC 360 impairment frameworks; Sherwood & Huber on the 35°C wet-bulb physiological limit; case record: 2011 Thailand (Chao Phraya) floods and hard-drive supply shock, February 2021 Texas freeze petrochemical/resin outages, Rhine low-water episodes 2018/2022. Thresholds identified in the text as working heuristics are engineering rules of thumb, not standards; asset-level conclusions require asset-level engineering data.

  • Data Centers in Dry Places: A Physical-Risk and Water-Scarcity Assessment Method

    Data Centers in Dry Places: A Physical-Risk and Water-Scarcity Assessment Method

    Updated Nov 1, 2026 — added the free dry-site risk quick card, data center water risk pack, and dry-site assessor bot book downloads to this guide.

    The AI build-out changed what a data center risks. Rack densities have climbed from a historical 10–15 kW to 40–100+ kW for GPU clusters, and every one of those kilowatts arrives as heat that has to leave the building — historically, by evaporating water. At the same time, sites chosen for cheap power, land and tax treatment cluster in exactly the basins where water is contested: the US Sun Belt, southern Europe, northern India, parts of East Asia. The result is a portfolio of facilities whose core input — cooling — depends on a resource their hosts may not be able to supply through a drought year. This guide sets out the assessment method operators and their ESG teams are converging on: screen the hazards geospatially, stress the thermal design honestly, measure water stress rather than water volume, and extend the analysis upstream to the fabs the whole industry depends on.

    Instant Engineering & ESG Downloads

    Data Centers in Dry Places: Quick Card, Assessment Pack & Bot Book

    Downscaled CMIP6 projection tools, 28–32°C wet-bulb thermal crossover models, N+1/N+2 water buffer scorecards, and machine-executable bot routines built directly from the physical-risk and water-scarcity assessment method.

    Quick Reference
    FREE

    Dry-Site Risk Quick Card

    2-page field card: the article’s 4 hazard pathways, 3-pass assessment method, and water stress toolkit (WUE vs PUE, Aqueduct 40–80% / >80%, ISO 14046 / AWARE lifecycle footprints, and upstream fab exposure), condensed onto one card.

    Download Free PDF

    Direct download • No email gate

    Working Pack
    $7

    Data Centers in Dry Places Pack

    6-sheet printable working pack: Hazard-to-cashflow reference sheet, Pass 1 geospatial exposure worksheet (CMIP6 SSP2-4.5/5-8.5), Pass 2 thermal crossover worksheet (28–32°C wet-bulb band), Pass 3 redundancy scorecard (N+1/N+2, 48–72h fuel & water buffer), Water-stress-not-volume quick reference, and Phase 1–4 execution tracker.

    Get Assessment Pack ($7) →

    Instant checkout • Square verified

    AI Intensive
    Book for Bots
    $17

    Dry-Site Assessor Bot Book

    Feed to ChatGPT or Claude: 7 AI-run routines (/pass-one, /wet-bulb, /redundancy, /basin-truth, /permit-audit, /disclosure-upstream, /exec-memo) with embedded output router to map CMIP6 site hazards, stress-test 28–32°C wet-bulb crossover, audit municipal drought curtailment hierarchies, and draft ESRS/IFRS/TNFD disclosures.

    Get Bot Book ($17) →

    Software made of words • Instant delivery

    The hazard set

    Hazard Driver Impact pathway Financial expression
    Extreme heat Rising ambient temperatures; urban heat islands Evaporative cooling efficiency falls with wet-bulb temperature; mechanical chillers carry the load PUE deteriorates; energy costs spike; thermal throttling in the tail
    Water scarcity & drought Precipitation shifts; aquifer depletion Municipal curtailment; industrial water prices rise Forced reduction in cooling withdrawal; dry-cooling retrofits; tanker logistics in extremis
    Flood & inundation Extreme rainfall; riverine and coastal surge Substations flood; fuel deliveries for backup generators are cut Long outages; asset damage; insurance repricing (see our stranded-assets guide)
    Grid stress & wildfire Peak demand colliding with heat; transmission fire risk Load shedding; public-safety shutoffs Generator hours accumulate — Scope 1 diesel, fuel-supply exposure, permit pressure

    The assessment method, in three passes

    Pass one — geospatial exposure mapping. Plot every facility against downscaled climate projections (CMIP6 under SSP2-4.5 and SSP5-8.5 are the working pair) at 2030, 2040 and 2050 horizons: temperature and wet-bulb trajectories, flood designations, basin-level water stress. The output is a risk taxonomy — low / medium / high / critical — per asset, not per portfolio. Portfolio averages conceal the only thing that matters, which is which specific buildings sit in which specific basins.

    Pass two — thermal and electrical sensitivity. Stress the cooling design against the projected wet-bulb tail (the 28–32°C wet-bulb band is where evaporative systems begin failing to hold ASHRAE environmental envelopes unaided) and calculate the crossover: at what ambient condition does the facility need full mechanical support, what does that do to PUE and power draw, and does the utility contract — and the grid behind it — carry that load on the same afternoon every other customer peaks?

    Pass three — redundancy and vulnerability scoring. Grade what the site can survive: N+1 / N+2 depth, on-site fuel autonomy (48–72 hours is the common design band), dual utility feeds, flood barriers and elevation, and — routinely underweighted — the water redundancy: second source, storage volume, reclaimed-water optionality.

    Engineering & Siting Tools

    Stress-Test Your High-Density Compute Siting Before the Next Drought Declaration

    Siting 40–100+ kW GPU clusters in the US Sun Belt, southern Europe, India, or East Asia creates direct balance sheet exposure when municipal water authorities face summer drought. Evaporative cooling fails to hold ASHRAE envelopes unaided in the 28–32°C wet-bulb band, triggering chiller spikes on the exact afternoons regional grids face peak load-shedding risk. Use our printable 6-sheet assessment pack to model asset-level CMIP6 SSP2-4.5/5-8.5 trajectories, calculate mechanical crossover points, and audit 48–72hr fuel and water redundancy buffers — or deploy the AI Bot Book to automate geospatial screening, municipal drought curtailment audits, and board-ready capital allocation memoranda.

    ☑

    What’s In The Toolkit:

    • Hazard-to-Cashflow Matrix: Heat, drought, flood, wildfire.
    • Pass 1 CMIP6 Screening: 2030/2040/2050 4-band taxonomy.
    • Pass 2 Thermal Crossover: 28–32°C wet-bulb & PUE spike.
    • Pass 3 Redundancy Grid: N+1/N+2, 48–72h fuel & water buffer.
    • Water Stress & LCA: 0.2 L/kWh WUE & ISO 14046 / AWARE.
    • AI Bot Book ($17): 7 executable bot routines + router.
    Secure 1-Click Square Checkout

    Water: measure stress, not just volume

    A litre consumed in a wet basin and a litre consumed in a stressed basin are different facts, and volumetric reporting treats them as identical. The working toolkit corrects for that:

    • WUE (Water Usage Effectiveness) — annual water use ÷ IT equipment energy (L/kWh). The efficiency baseline. Evaporative fleets run well above 0.2 L/kWh; the design frontier — dry cooling, closed-loop and direct-to-chip liquid cooling — targets below 0.2 and approaches zero on site. Report WUE alongside PUE or not at all: the two trade against each other, and optimizing one in secret is how facilities end up efficient on paper and fragile in fact.
    • WRI Aqueduct (and the WWF Water Risk Filter) — basin context: baseline water stress (High at 40–80%, Extremely High above 80%), seasonal variability, groundwater decline, regulatory and reputational exposure. A facility in an Extremely High basin needs a mitigation plan regardless of its WUE.
    • ISO 14046 water footprinting — life-cycle assessment of direct and indirect water (including the water embedded in purchased electricity), scarcity-weighted with characterization factors such as AWARE. This is the step that catches the shell game: a “zero-water” site on a coal-heavy grid has moved its water, not eliminated it.
    • Source Water Vulnerability Assessment — the local audit: the municipal supplier’s own sustainability, recharge rates, drought allocation hierarchies (who gets cut first, by law), and competing agricultural and residential demand growth.

    Disclosure anchors

    ESRS E3 (Water and Marine Resources) requires in-scope companies to report water consumption — specifically in water-stressed areas — with watershed context, alongside ESRS E1 for the physical-risk scenario analysis itself. IFRS S2 requires the financial-effects version: what physical risk does to position and cash flows, and what adaptation capital is allocated against it. The TNFD’s LEAP approach (Locate, Evaluate, Assess, Prepare) gives the nature-dependency framing site selection teams increasingly use. And beneath the frameworks sits the layer that binds first in practice: municipal permitting. Local ordinances are progressively restricting potable-water extraction for industrial cooling and pushing facilities toward reclaimed and non-potable feeds — the permit, not the framework, is where water strategy becomes compulsory. (The framework map is in our compliance frameworks overview.)

    Upstream: the fab problem

    A data center’s water risk does not end at its fence line; its supply chain concentrates in the same hazard. Advanced semiconductor fabrication is ultra-pure-water intensive, and fab capacity concentrates in drought-exposed geographies — Taiwan (whose 2021 drought forced water trucking to fabs) and Arizona among them. A single-point failure there is a server-availability event everywhere. The same interdependency runs through power: the embedded water footprint of regional generation — hydro reliability in drought, thermal-plant cooling limits in heatwaves — is the data center’s availability risk wearing another name. A complete assessment maps the top upstream nodes (fabs, cold-plate and PDU manufacturing, grid regions) through the same hazard screen as the facilities themselves.

    Choose Your Data Center Physical-Risk & Water Assessment Toolkit

    Select the engineering and resilience resource that matches your site selection, facility audit, or ESG disclosure needs:

    Free Field Summary

    Dry-Site Risk Quick Card

    2-page field card: the article’s 4 hazard pathways, 3-pass assessment method, and water stress toolkit (WUE vs PUE, Aqueduct 40–80% / >80%, ISO 14046 / AWARE lifecycle footprints, and upstream fab exposure).

    FREE
    direct download
    • The 4-Hazard Screening Matrix & Financial Expressions
    • Pass 1 CMIP6 Downscaled Screening Protocol
    • Pass 2 Thermal Crossover & 28–32°C Wet-Bulb Band
    • Pass 3 Redundancy (N+1/N+2, 48–72h Fuel & Water Buffer)
    • WUE vs PUE Coupled Reporting Frontier (<0.2 L/kWh)
    • WRI Aqueduct High (40–80%) & Extremely High (>80%) Triggers

    Download Free PDF

    Working Pack

    Data Centers in Dry Places Pack

    Printable, fillable 6-sheet working pack with hazard-to-cashflow matrices, CMIP6 screening registers, thermal crossover calculators, and redundancy scorecards.

    $7.00
    one-time
    • Hazard-to-Cashflow Reference Sheet & Siting Risk Matrix
    • Pass 1 Geospatial Exposure Worksheet (CMIP6 SSP2-4.5/5-8.5)
    • Pass 2 Thermal Crossover Worksheet (28–32°C Wet-Bulb Band)
    • Pass 3 Redundancy Scorecard (N+1/N+2, 48–72h Fuel & Water)
    • Water-Stress-Not-Volume Quick Reference & Audit Checklist
    • Phase 1–4 Execution Tracker & Regulatory Disclosure Matrix

    Buy Assessment Pack ($7) →

    AI Intensive
    Book for Bots

    Dry-Site Assessor Bot Book

    Structured 8-page AI playbook for ChatGPT and Claude: 7 autonomous routines, wet-bulb failure band models, municipal permit audits, and upstream fab screens.

    $17.00
    one-time
    • Routine 1: Pass-One Geospatial Mapper (/pass-one)
    • Routine 2: Wet-Bulb Crossover Stress Test (/wet-bulb)
    • Routine 3: Redundancy & Water-Resilience Scorer (/redundancy)
    • Routine 4: WUE-vs-PUE & ISO 14046 Basin Truth (/basin-truth)
    • Routine 5: Source Water & Permit Auditor (/permit-audit)
    • Routine 6: Upstream Fabs & Disclosure Mapper (/disclosure-upstream)
    • Routine 7: Master Synthesis & Executive Memo (/exec-memo)

    Buy Bot Book ($17) →

    All payments securely processed by Square • Apple Pay, Google Pay & Corporate Cards Accepted

    The execution roadmap

    Phase 1 (months 1–3) — audit. Screen 100% of owned and leased locations through Aqueduct and the downscaled projections; classify every site into the four-band taxonomy; commission Source Water Vulnerability Assessments for the high and critical bands.

    Phase 2 (months 4–12) — cooling transition. In stressed basins, mandate the low-water architectures for new high-density deployments — dry cooling, direct-to-chip liquid, rear-door heat exchangers — and retrofit evaporative systems with adiabatic assist to cut peak-season draw. Design decisions made in this phase are 15-year commitments; the basin projections, not this year’s rainfall, are the design basis.

    Phase 3 (months 12–18) — circular sourcing. Exit potable municipal water for industrial cooling: reclaimed municipal wastewater, industrial greywater, on-site rainwater harvesting. This is also the phase where allocation politics get managed — a facility that does not compete with residents for drinking water holds a materially stronger position in a drought allocation fight.

    Phase 4 (ongoing) — replenishment and transparency. Watershed restoration in operating basins — wetland creation, aquifer recharge, invasive removal — against volumetric replenishment targets. The pledge benchmark is set by the largest operators: Microsoft’s commitment to be water positive by 2030, and Google’s target of replenishing 120% of its freshwater consumption. Pair the projects with public, near-real-time usage reporting; in stressed basins, secrecy about consumption reads as guilt about consumption.

    Frequently asked questions

    What’s the difference between WUE and PUE — and why report both?

    PUE measures energy overhead (total facility energy ÷ IT energy); WUE measures water overhead (annual water ÷ IT energy). Cooling choices trade one against the other: evaporative cooling improves PUE by spending water; dry cooling saves water by spending energy. Reporting only one invites optimizing the reported number at the expense of the hidden one.

    Does direct-to-chip liquid cooling eliminate water risk?

    It largely eliminates on-site evaporative demand — the loop is closed. It does not eliminate the water embedded in the electricity the facility buys (generation cooling and hydro dependence), nor the upstream fab water in its servers. ISO 14046 footprinting exists precisely to keep that distinction honest.

    What water-stress level should trigger a mitigation plan?

    On WRI Aqueduct’s baseline water stress scale, High (40–80%) warrants a documented mitigation plan; Extremely High (above 80%) warrants one before further capacity is added. The trigger is the basin classification, not the facility’s own consumption — a small consumer in a critical basin still faces curtailment politics and allocation hierarchies.

    Why do hyperscalers publish replenishment pledges — is that operations or PR?

    Both, and the operational part is real: replenishment projects (wetlands, recharge) raise the basin’s effective supply for every user including the operator, and the pledges — Microsoft water-positive by 2030, Google at 120% of consumption — are volumetric commitments that can be audited against reported consumption. The PR value collapses quickly if the underlying consumption data isn’t published with them.


    Sources: WRI Aqueduct 4.0 (baseline water stress bands); The Green Grid WUE metric definition; ISO 14046 water footprint standard and AWARE characterization factors; ASHRAE thermal environmental envelopes; CMIP6 scenario framework (SSP2-4.5, SSP5-8.5); ESRS E3 and E1; IFRS S2; TNFD LEAP approach; Microsoft (water positive by 2030) and Google (120% replenishment) public commitments. Site-level conclusions require site-level hydrological data; basin classifications are screening instruments, not engineering determinations.

  • Transition Risk in Heavy Industry: CBAM’s Ramp, Carbon Scenarios and the CapEx Decisions They Force

    Transition Risk in Heavy Industry: CBAM’s Ramp, Carbon Scenarios and the CapEx Decisions They Force

    Physical risk strands assets by breaking them or uninsuring them — our companion guide covers that pathway. Transition risk strands them by arithmetic: a carbon price lands on the cost base, margins compress, and plant designed for a 30-year life stops clearing its hurdle rate in year eight. The forcing event for the next decade is the EU’s Carbon Border Adjustment Mechanism, whose definitive regime began on January 1, 2026 — and whose actual shape is widely misreported. CBAM is not a cliff. It is a ramp with published steps, and planning against the ramp rather than the headline is the difference between an orderly CapEx programme and a disorderly write-down.

    CBAM: the ramp is the story

    In 2026, almost nothing is charged — and that is precisely the trap. Importers of iron and steel, aluminium, cement, fertilisers, hydrogen and electricity into the EU must be authorised declarants, must measure embedded emissions, and accrue obligations from January 1, 2026. But under the simplification regulation, no certificates are sold during 2026 at all. The verified calendar:

    Date What happens
    Jan 1, 2026 Definitive regime begins; obligations accrue; only 2.5% of embedded emissions are chargeable (the CBAM factor, mirroring 97.5% free ETS allocation)
    2026 prices Certificate price = EU ETS quarterly average: €75.36/t (Q1 2026), €75.28/t (Q2 2026)
    Feb 1, 2027 Certificate sales open on the common platform; declarants buy against 2026 imports
    Sep 30, 2027 First annual declaration and surrender, covering 2026 imports
    By 2030 CBAM factor rises to 48.5% chargeable
    Jan 1, 2034 Factor reaches 100%; free allocation for CBAM sectors is gone

    Two consequences follow. First, the 2026 bill is small enough to breed complacency — at the Q2 price and the 2.5% factor, a tonne of blast-furnace steel carries a charge measured in single euros, against a gross figure above €100 at full coverage. The exposure is the curve, not the first step. Second, the binding constraint in 2026 is not money but data: verified embedded-emissions figures from non-EU producers, because default values are deliberately unattractive and the first declaration lands in September 2027. (Our Scope 3 supplier data guide covers the collection mechanics.) The same tightening runs through the EU ETS itself — the cap shrinks annually under the linear reduction factor (4.3% a year through 2027, 4.4% from 2028) — and beyond Europe: China’s national ETS, long confined to power, is extending to steel, cement and aluminium. Carbon cost curves for heavy industry are being rewritten in every major market at once.

    What a carbon price does to a balance sheet

    The sequence is mechanical: compliance cost compresses margin; compressed margin shortens economic life; shortened life forces the accounting to follow. Depreciation schedules built on 30-to-40-year lives get revised toward regulatory horizons, raising the annual charge. Cash-generating units that no longer clear recoverability tests take impairment charges (the IAS 36 / ASC 360 mechanics are set out in the companion guide). Credit assessments absorb the same facts — rating agencies now model transition vulnerability explicitly — and refinancing arrives on worse terms for unhedged carbon intensity, in a market that increasingly prices the exposure even where no regulator compels it. None of this requires a carbon price of $300. It requires a carbon price that is real, rising on a published schedule, and applied to a cost base that cannot move. Exposure differs sharply by sector:

    Sector Assets most exposed Principal triggers Working horizon
    Oil & gas High-break-even reserves (oil sands, deepwater), unrefined midstream Demand peak, engine phase-outs, methane regulation, low-cost displacement 2026–2032
    Power & utilities Unabated coal; gas peakers without capture Clean-energy mandates, storage cost parity, intensity limits, merit-order displacement 2026–2030
    Steel & metals Blast furnace–BOF lines without capture CBAM, green-steel procurement by automakers, scrap-EAF and DRI competition 2027–2035
    Cement & materials Wet-process kilns, high-clinker lines without capture or SCMs Green public procurement, carbon costs in building codes, local caps 2028–2035
    Chemicals & refining Steam crackers, fuel-focused refineries Circular-economy mandates, heat electrification, falling fuel demand 2028–2035

    The horizons are planning judgments, not predictions — but they are the right shape: power and upstream oil face the earliest tests; cement and chemicals get a longer runway because their abatement options are harder, not because their exposure is smaller.

    Scenarios: use them as stress tests, not forecasts

    The NGFS scenario families — Net Zero 2050 (orderly), Delayed Transition (disorderly), Current Policies (hot house) — are the standard grammar, and their carbon prices are the most misused numbers in the field. Scenario prices are model outputs: they differ by model, region and vintage, and any single band quoted without those qualifiers is decoration. Used properly, the scenarios answer a narrower question: does this CapEx book survive each path? In the orderly path, carbon costs rise early and predictably — transition impairment is structured, and replacement technology enjoys cheap capital. In the delayed path, the same costs arrive after 2030 in compressed form — the write-downs concentrate. In the current-policies path, transition pressure fades and physical risk does the damage instead. A capital plan that only works in one of the three is not a plan; it is a bet, and the board should hear it described that way.

    The abatement menu, and how to order from it

    Capital allocation committees rank options on a marginal abatement cost curve (MACC): cost per tonne avoided against volume available. The main industrial pathways, with indicative cost ranges as commonly assessed in the literature — treat them as orientation, not quotes:

    Pathway Readiness Indicative abatement cost Reduction potential Binding prerequisite
    Green hydrogen (DRI steel, chemical feedstock) Demonstration–early commercial ~$120–220/tCO₂e 85–95% of process emissions Very cheap renewable power; electrolyser scale; H₂ transport
    CCUS Commercial for concentrated streams ~$70–140/t (concentrated); higher when dilute 80–90% of point-source emissions Storage geology; shared CO₂ networks; liability rules
    High-temperature electrification Pilot–early commercial ~$50–130/t Up to ~100% of process-heat emissions Grid capacity and reliability; electricity–gas price spread
    Biomass / alternative fuels Commercial ~$40–90/t 30–60% of thermal emissions Certified sustainable supply; burner modification

    Below the line sit the negative-cost quick wins — waste-heat recovery, combustion tuning, steam and compressed-air leak programmes, variable-frequency drives — which pay back in cash and should never wait for a strategy process. The deep conversions (BF-BOF to hydrogen-ready DRI, kiln retrofits with capture, electric crackers) are the decisions the ramp actually governs: each has a lead time of years, which is why the 2034 full-coverage date is a present CapEx fact, not a future one.

    Internal carbon pricing: the discipline that connects them

    A shadow carbon price inside the investment model is what stops a plant that fails at €75/t from being approved at €0. Two design rules matter more than the level. First, anchor the schedule to prices the company already faces: a shadow price set below the EU ETS level (about €75/t in 2026) that CBAM and the ETS already impose is decoration. An illustrative rising schedule — starting near today’s ETS price, stepping up through the late 2020s as the CBAM factor climbs toward 48.5%, and reaching the low hundreds by the mid-2030s at full coverage — mirrors the company’s actual regulatory curve; each business should build its own from its own exposure. Second, distinguish the instruments: a shadow price only steers evaluation (it appears in NPV and hurdle tests, no cash moves), while an internal fee actually charges business units and funds abatement. Most heavy-industry programmes need the shadow price everywhere first; the fee is a later, harder governance step. IFRS S2 already asks companies to disclose whether and how internal carbon pricing is used in decision-making — the practice is becoming reportable, not merely virtuous.

    Accounting and disclosure, briefly

    The impairment mechanics live in the companion guide; the transition-specific adjustments are three. In value-in-use models: cash inflows fall (volume and margin under carbon cost), cash outflows rise (compliance purchases along the CBAM/ETS ramp), and terminal growth compresses toward zero for exposed assets. One discipline deserves emphasis because it is the standard’s own: IAS 36 requires risk to be reflected in the cash flows or the discount rate — adjusting both for the same transition risk double-counts it, and auditors increasingly probe exactly that. Useful lives and residual values must track the same story (a kiln retired in 2033 is not depreciated to 2055), and CGU boundaries may need redrawing where decarbonisation infrastructure is shared. On disclosure: IFRS S2 requires the CapEx deployed toward climate response and the internal-carbon-price position; ESRS E1 requires the transition plan itself, Taxonomy-aligned CapEx shares, and an analysis of locked-in emissions — whether today’s CapEx commits the company to tomorrow’s carbon costs. California’s regime adds the US layer (see the compliance playbook).

    Ninety days, then ongoing

    Days 1–30 — stranding audit and shadow price. Screen the PP&E register against the CBAM ramp, ETS exposure and the sector horizons above; adopt a shadow-price policy at every capital gate; re-test depreciation lives on the exposed CGUs. Days 31–60 — MACC and feasibility. Build the asset-level abatement curve; commission engineering feasibility on the top pathways; launch the negative-cost quick wins immediately. Days 61–90 — rationalise and finance. Decide the divest/convert/close list while the assets still have buyers; structure transition finance (ring-fenced transition bonds, sustainability-linked facilities, blended structures for first-of-a-kind plant) against the programme. Ongoing — stress and audit. Re-run the scenario tests quarterly against actual ETS/CBAM prices, fold climate-adjusted impairment into the internal audit cycle, and publish Taxonomy CapEx alignment annually. The deliverable rhythm matters more than any single artefact: transition risk moves on a regulatory calendar, and the finance function has to move on the same one.

    Frequently asked questions

    When do we actually pay for CBAM certificates?

    Obligations accrue from January 1, 2026, but certificate sales open February 1, 2027, and the first surrender — with the first annual declaration — is due September 30, 2027, covering 2026 imports. Only 2.5% of embedded emissions are chargeable in 2026; the factor climbs to 48.5% by 2030 and 100% on January 1, 2034.

    Does CBAM apply to a US exporter directly?

    No. The authorised declarant — the EU importer — holds the obligation and buys the certificates. The cost and, more immediately, the verified-emissions data demands travel upstream to the producer. A US exporter experiences CBAM as its EU customers’ data requests and price negotiations.

    What carbon price should our investment models use?

    Not a forecast — a schedule. Anchor to prices already in force where you operate (the EU ETS has priced CBAM certificates at about €75/t through 2026), rise with the published CBAM factor steps, and stress the decision at higher levels under the delayed-transition scenario. A project that only survives at €0 carbon is the finding, whatever schedule you choose.

    Is our existing plant automatically impaired once CBAM applies?

    No. CBAM exposure is an impairment indicator prompting a test, as with the insurance shock in the companion guide. The outcome depends on the asset’s cash flows under the ramp — pass-through ability, abatement options and remaining life. Efficient producers inside a carbon-intensive sector can gain relative advantage as the factor rises.


    Sources: Regulation (EU) 2023/956 (CBAM) as amended by Regulation (EU) 2025/2083 — definitive regime from Jan 1, 2026; certificate sales from Feb 1, 2027; first declaration Sep 30, 2027; CBAM factor 2.5% (2026) → 48.5% (2030) → 100% (2034); European Commission CBAM certificate prices Q1 2026 €75.36/t, Q2 2026 €75.28/t; EU ETS linear reduction factor (Directive (EU) 2023/959); NGFS scenario framework; IAS 36 (incl. the cash-flow/discount-rate double-counting caution) and IFRS S2 / ESRS E1 disclosure requirements. Abatement cost ranges are indicative spans from the published literature, not project estimates.

  • When Insurance Disappears: Stranded Assets, Residual Pools and the Write-Down Mechanics

    When Insurance Disappears: Stranded Assets, Residual Pools and the Write-Down Mechanics

    Updated Nov 1, 2026 — added the free uninsurability quick card, uninsurability-to-write-down pack, and stranded-asset insurance bot book downloads to this guide.

    An asset does not have to flood or burn to lose value. It only has to lose its insurance. The transmission pathway runs in one direction: hazards intensify → primary carriers retreat (non-renewals, exclusions, sub-limits, percentage deductibles) → owners fall back on state residual pools, captives or self-insurance → premiums and retained risk crush net operating income while buyers widen capitalization rates → the asset fails an impairment test it would have passed the year before. Every step is documented in ordinary market and accounting practice; what is new is the speed and the geography. This guide walks the pathway with the real numbers where they exist — California’s FAIR Plan is the clearest gauge in the world right now — and then sets out the accounting mechanics (IAS 36 and ASC 360), the fallback risk-transfer stack, and the disclosure position as it actually stands in late 2026, including one regime that no longer exists.

    Stranded-Asset Toolkit Downloads

    Audit Uninsurability, Covenant Headroom & Impairment Exposure

    Field-ready quick cards, printable impairment & covenant audit worksheets, and AI-powered bot routines built directly from this guide to quantify insurance retreat before write-downs land.

    Field Summary
    FREE

    Uninsurability Quick Card

    2-page field card: The 4 retraction mechanics (sub-limiting, percentage deductibles, ZIP non-renewals, residual strain) plus the fallback stack (captives, parametrics, cat bonds) on one card.

    Download Free PDF

    Direct download • No email gate

    Working Pack
    $7

    Uninsurability to Write-Down Pack

    5-page printable working pack: Portfolio coverage audit checklist, uninsurability heatmap (FAIR Plan gauge reference), retraction spotter, fallback-stack builder, IAS 36 / ASC 360 impairment worksheet, and covenant headroom tracker.

    Get Working Pack ($7) →

    Instant checkout • Square verified

    AI Intensive
    Book for Bots
    $17

    Stranded-Asset Insurance Bot Book

    Feed to ChatGPT or Claude: 6 interactive governance routines (Coverage Fragility Interview, Impairment Test Runner, Covenant Forecaster under NGFS, Contagion Calculator, ART Stack Builder, Disclosure Drafter) with embedded output router.

    Get AI Bot Book ($17) →

    Software made of words • Instant delivery

    The retraction, measured

    California’s FAIR Plan — the state’s insurer of last resort, a pool backed by all admitted insurers — carried $768 billion of exposure and 696,562 policies in June 2026, up roughly 250% from about $220 billion in September 2022. The January 2025 Los Angeles fires alone cost the plan on the order of $3.5–4 billion and triggered a $1 billion assessment on its member insurers in February 2025 — which is the mechanism to understand: when the residual pool cannot pay, the shortfall is assessed back across the admitted market and recovered, in part, from ordinary policyholders. Uninsurability is therefore not only a problem for the properties inside the pool. It is a contingent cost for every insured asset in the state.

    The retraction mechanics repeat across catastrophe-exposed markets:

    • Sub-limiting. Carriers cap windstorm, flood or wildfire cover at a fraction of total replacement cost, forcing owners to layer excess capacity at escalating prices — or carry the gap.
    • Percentage deductibles. Flat deductibles give way to deductibles calculated as a percentage of total insured value, payable per event — a retention that can exceed the historic premium.
    • Non-renewal at scale. Whole ZIP-code clusters exit the admitted market in California, Florida, Texas, Louisiana and comparable exposures elsewhere, irrespective of individual asset quality.
    • Residual-pool strain. Florida’s Citizens grew into the state’s largest property insurer at its 2023 peak; a state depopulation programme has since been moving policies back to private carriers, but a major landfall still concentrates assessment exposure on the market that remains. Public-private structures abroad — France’s CCR, the UK’s Flood Re — face the same recalibration pressure as event frequency outruns the reserves the schemes were priced on.

    The fallback stack: what replaces a primary policy

    Mechanism How it works Balance-sheet reality Where it fits
    Primary P&C insurance Indemnity cover from admitted carriers Premium expense only; no capital committed Assets carriers still want — shrinking set in exposed zones
    Captive insurer A licensed subsidiary insures the parent’s risks Regulatory capital committed up front; risk stays in the group, underwriting margin too Large, diversified portfolios; funding high-frequency, lower-severity layers
    Parametric cover Pays a fixed amount when a measured trigger (wind speed, flood depth) is hit Fast liquidity, no adjustment process; basis risk — the trigger can miss your actual loss Liquidity-critical assets; layers indemnity markets won’t write
    Cat bonds / ILS Collateralized cover sold to capital markets via an SPV High setup cost; multi-year, fixed capacity Institutional-scale tail exposure, typically $100M+ programmes

    None of these is a like-for-like replacement at the old price. That gap — between historic underwriting cost and the new cost of the stack — is what flows into valuation.

    How uninsurability becomes a write-down

    Losing affordable cover is an impairment indicator, not an automatic loss — and the distinction is where the accounting discipline sits. IAS 36 (paragraph 12) lists significant adverse changes in the legal or business environment among the external indicators that require a test; ASC 360-10-35-21 carries the US equivalent. An insurance shock qualifies on its face: operating costs step up structurally, and in the hard cases lender covenants requiring specified coverage can put the debt itself in question. What follows is a test, run two different ways:

    • IAS 36 (IFRS) — one step. Impairment exists if carrying amount exceeds recoverable amount: the higher of fair value less costs of disposal and value in use. Value in use must reflect the new insurance economics — elevated premiums and retained risk inside the cash flows, and a discount rate that prices an asset buyers now see as partially uninsurable.
    • ASC 360 (US GAAP) — two steps. First, recoverability: are total undiscounted future cash flows from use and disposition below carrying value? Only if that test fails is the loss measured, as carrying value minus fair value (ASC 820).

    Fair value work (IFRS 13 / ASC 820) on an uninsurable asset is Level 3 work — unobservable inputs — and two adjustments do most of the damage: the discount rate widens for unmitigated tail risk, and the exit capitalization rate expands for illiquidity. An illustrative formulation used by valuation teams makes the channel explicit: fair value equals the stream of NOI minus an insurance deficit term (the excess of new premiums plus retained-loss expectation over historic underwriting cost), discounted at the risk-adjusted rate. The formula is a modelling choice, not a standard — but some version of that subtraction is now in every serious appraisal of an exposed asset.

    The covenant cascade fires before the write-down lands. Premium escalation cuts NOI (DSCR numerator) while revaluation cuts appraised value (LTV denominator):

    Ratio Definition Transmission Typical covenant zone
    DSCR NOI ÷ debt service Premium spikes reduce NOI directly Minimum ~1.20–1.25×
    LTV Debt ÷ appraised value Write-downs shrink the denominator; debt is static Maximum ~65–75%
    ROA Net income ÷ total assets Higher opex and impairment charges hit both sides Internal hurdle rates; rating-agency scrutiny

    A DSCR breach typically triggers cash sweeps and distribution lockups; an LTV breach can require an equity cure or principal paydown. These are lender conversations that happen on renewal dates, not accounting dates — which is why the audit below starts with policy expiries.

    Valuation & Impairment Suite

    Model Your Insurance Deficit Before Covenants Default

    Losing affordable cover is an impairment indicator under IAS 36 and ASC 360. Equip your treasury, risk, and accounting leads with fillable valuation worksheets that calculate the insurance deficit term, model DSCR/LTV headroom buffers, and run interactive AI prompts to audit policy files and stress-test NGFS transition paths.

    📊

    What’s In The Impairment Suite:

    • Portfolio Audit Checklist: TIV, sub-limits & covenants.
    • Heatmap & FAIR Plan Gauge: Low-to-critical rubric.
    • Stack Builder: Captive, parametric & cat bond layers.
    • Impairment Steps: IAS 36 VIU vs ASC 360 Level 3.
    • Bot Book ($17): 6 AI routines & embedded router.
    Secure 1-Click Square Checkout

    Disclosure: the position as it actually stands

    ISSB IFRS S2 is the live global baseline. Paragraphs 15–21 require disclosure of the climate risks that could affect an entity’s prospects, the quantified financial effects on position, performance and cash flows across short, medium and long horizons, and how the strategy responds. Insurance availability is not a named line item — but an asset whose cover has collapsed is squarely inside “risks that could reasonably be expected to affect cash flows and access to finance,” and the financial-effects disclosure is where the write-down story gets told.

    ESRS E1 (CSRD) adds the double-materiality side: undertakings disclose material physical risks, the assets exposed to them, and — under E1-9 — the anticipated financial effects of those risks. One practical recommendation, offered as practice rather than requirement: quantify the split of the portfolio between commercial cover, residual pools and self-insurance. No standard mandates that exact cut today; assurers and lenders increasingly ask for it anyway, and it is cheap to produce from the Phase 1 audit below.

    The United States federal rule is gone — plan accordingly. The SEC’s 2024 climate disclosure rules (the source of the often-cited Regulation S-K Items 1502/1503) were stayed before they ever applied to a filing; the Commission voted to end their defense in March 2025, and on May 29, 2026 it proposed rescinding them in their entirety. Any framework document that still lists the SEC rule as a live mandate is out of date. The operative US disclosure regime for climate risk is now California’s — SB 253 (emissions) and SB 261 (climate-risk reports) — covered end-to-end in our compliance playbook, layered on ordinary materiality principles. Our frameworks map places the regimes side by side.

    Scenario analysis is the stress frame. The NGFS scenario families — Net Zero 2050 (orderly: transition risk front-loaded, physical risk contained), Delayed Transition (disorderly: policy shock after 2030, repricing concentrated), and Current Policies (hot house: transition risk low, physical risk severe) — give boards a common grammar for the write-down question. For uninsurability specifically, the disorderly and hot-house paths matter most: one reprices the asset through policy, the other through the insurance market, and portfolios should be stress-tested against both.

    A twelve-month action plan

    Phase 1 (months 1–3) — coverage and exposure audit. Map every asset against hazard layers (flood, wildfire/WUI, storm surge) and against its own policy file: expiry dates, deductible structures, sub-limits, covenant insurance requirements. Deliverable: a portfolio uninsurability heatmap — low / moderate / high / critical — that ranks assets by coverage fragility, not just hazard.

    Phase 2 (months 4–6) — impairment and covenant stress test. Run the IAS 36 / ASC 360 tests on the critical set under premium-escalation and discount-rate-widening assumptions, and model DSCR/LTV headroom under the NGFS disorderly and hot-house paths. Deliverable: a board-level sensitivity report — potential write-down range, covenant breach points, and the dates they bite.

    Phase 3 (months 7–9) — resilience engineering that underwriters reward. Spend CapEx where it changes an underwriting decision: flood barriers, roof hardening, defensible space, power redundancy — documented to carrier mitigation criteria, not to a generic resilience checklist. Deliverable: an asset-hardening package submitted into renewal negotiations as evidence.

    Phase 4 (months 10–12) — restructure the stack. Capitalize the captive layer, place parametric cover for the untriggerable-by-indemnity risks, evaluate ILS for the tail, and wire the outputs into IFRS S2 / ESRS E1 disclosure. Deliverable: an operating alternative-risk-transfer framework with the audit trail the disclosure regimes expect.

    Role Owns Deliverable
    CFO Impairment testing, covenant compliance, ART capital Sensitivity analysis; captive capital plan
    CRO Exposure mapping, scenario testing, renewals Uninsurability heatmap; catastrophe limits
    ESG / Sustainability lead S2 and ESRS E1 disclosure integration Disclosure package; scenario reporting
    Head of Real Estate Retrofits and code compliance Hardening plans; condition assessments

    Operational Tool Comparison

    Compare Uninsurability Tools & AI Audit Systems

    Choose the analytical depth required for your assets: quick field summary, printable impairment and covenant working pack, or intensive AI bot book for your language models.

    Field Summary

    Uninsurability Quick Card

    2-page field card condensing the retraction pathway and the fallback risk-transfer stack.

    • Core transmission pathway: hazards → retreat → NOI drop → write-down
    • The 4 retraction levers: sub-limits, % deductibles, ZIP non-renewal, residual strain
    • California FAIR Plan benchmark: $768B exposure, 696k policies, $1B assessment
    • Fallback stack matrix: primary P&C, captives, parametrics, cat bonds
    • Valuation transmission & covenant cascade quick summary

    FREE

    Download Quick Card (PDF)

    Instant direct download • No email gate

    Static Working Pack

    Uninsurability to Write-Down Pack

    5-page printable & fillable audit system with full tables, checklists, and working logs.

    • Portfolio coverage & exposure audit checklist (hazards vs terms)
    • Uninsurability heatmap worksheet (Low/Mod/High/Critical ranking)
    • Retraction-mechanics spotter (evaluating renewal terms & E&S quotes)
    • Fallback-stack builder worksheet (cost/trigger slots for captives & parametrics)
    • Impairment worksheet: IAS 36 / ASC 360 recoverable-amount calculations
    • Covenant headroom tracker: DSCR/LTV slots & 12-month action plan

    $7.00

    Get Working Pack ($7) →

    Instant delivery • Square checkout

    AI Intensive
    Book for Bots

    Stranded-Asset Insurance Bot Book

    Structured text document feeding 6 executable AI routines to ChatGPT or Claude to audit policy files, model impairments, and draft disclosures.

    • /audit-fragility: Interrogates contracts to build low-to-critical heatmap
    • /test-impairment: Walks IAS 36 & ASC 360 models with insurance deficit
    • /forecast-covenants: Projects DSCR/LTV breach dates under NGFS paths
    • /check-contagion: Calculates FAIR Plan & Citizens assessment exposure
    • /build-art-stack: Generates captive, parametric & cat bond layering
    • /draft-disclosure: Drafts audit-ready IFRS S2, ESRS E1 & SB 261 text
    • Includes embedded output router and functional role assignments

    $17.00

    Get AI Bot Book ($17) →

    Software made of words • Instant delivery

    Frequently asked questions

    Is losing our insurance an automatic impairment?

    No. It is an impairment indicator — under IAS 36 and ASC 360 it obliges a test, and the test decides. Assets with strong cash flows can absorb the new insurance economics on paper; the write-down arrives when recoverable amount (IFRS) or the undiscounted cash-flow test followed by fair value (US GAAP) says the carrying value no longer holds.

    We’re not in the FAIR Plan. Why does its deficit matter to us?

    Because the plan is backed by the admitted market. When claims overwhelm it — $1 billion assessed on member insurers after the January 2025 fires — insurers recover through their own books, including surcharges on ordinary policies where regulators approve them. Residual-pool math is market-wide math.

    What is basis risk in a parametric policy?

    The payout follows a measured trigger (wind speed at a station, water depth at a gauge), not your loss. If the trigger fires and your damage is small, you are overpaid; if your damage is severe and the trigger narrowly misses, you are paid nothing. Parametric cover is liquidity insurance, priced and governed differently from indemnity cover — it complements the stack; it does not replace it.

    Do we still need to prepare SEC climate disclosures?

    No — the 2024 rules never took effect, the SEC stopped defending them in 2025, and rescission was proposed in May 2026. US climate disclosure obligations now run through California’s SB 253 and SB 261 for in-scope companies, plus ordinary materiality-based disclosure. Frameworks documents citing Items 1502/1503 as live requirements are stale.

    At what scale do catastrophe bonds make sense?

    Historically, programmes with limits in the hundreds of millions, where setup and legal costs amortize across multi-year collateralized capacity — sovereigns, utilities, large infrastructure and institutional portfolios. Below that scale, captives and parametric placements usually carry the same layers more cheaply.


    Sources: California FAIR Plan exposure and policy data as disclosed June 2026 (via CDI/KQED reporting) and February 2025 assessment reporting; IAS 36 (incl. ¶12 indicators), ASC 360-10-35 and ASC 820 / IFRS 13 fair value frameworks; ISSB IFRS S2 ¶¶15–21; ESRS E1 incl. E1-9; SEC climate disclosure rules — adoption (Mar 2024), stay (Apr 2024), end of defense (Mar 2025), rescission proposal (May 29, 2026, Rel. 33-11421 reporting); NGFS scenario framework (Net Zero 2050, Delayed Transition, Current Policies). Figures are as published at the time of writing; insurance-market conditions move quickly and asset-level conclusions require asset-level underwriting data.

BC ESG

ESG Strategy, Sustainability Intelligence, and Business Continuity for Forward-Thinking Organizations

© 2026 BC ESG — Business Continuity, ESG & Sustainability Intelligence