PARTIALISSB Sustainability & Climate Disclosure Standards (IFRS S1 & IFRS S2)
Deciding Instrument: IFRS S1 / IFRS S2 (2023) & Dec 2025 Targeted S2 Amendments | Date: 2025–2026 (Active in ~20 Jurisdictions; S2 Amendments Jan 2027)
Verdict & Proof: ISSB IFRS S1 and S2 are LIVE as mandatory domestic law in nearly 20 non-U.S. jurisdictions (including Australia, UK SRS, Singapore, Hong Kong, and Brazil), with targeted IFRS S2 Scope 3 relief amendments issued December 2025 taking effect January 2027. U.S. suppliers encounter ISSB via multinational prime buyers.
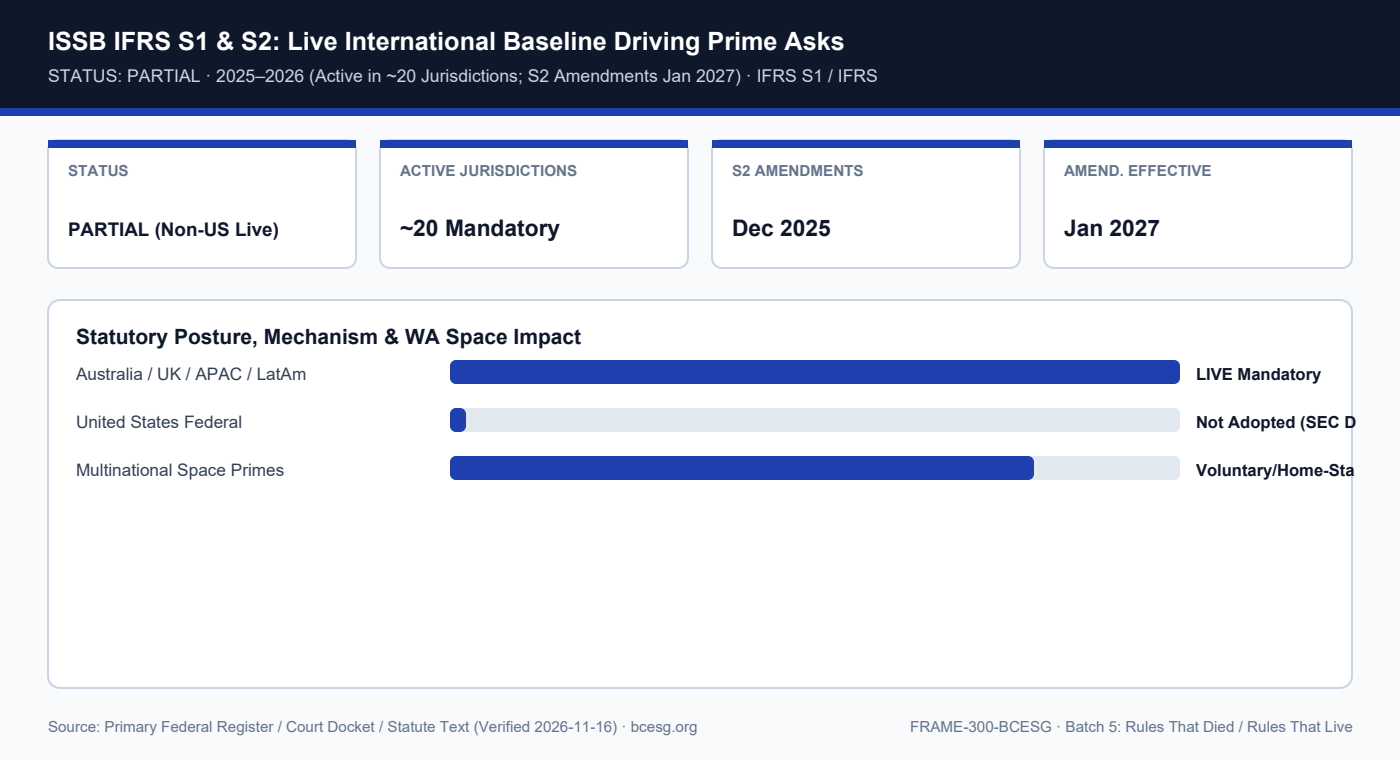
Where ISSB Lives vs. Where It Doesn't
Nearly 40 jurisdictions have moved to adopt or align with ISSB IFRS S1 and S2 by 2026, with mandatory reporting live in ~20 markets (Australia AASB S2, UK SRS, Singapore, Hong Kong, Brazil). In December 2025, the ISSB issued targeted amendments to IFRS S2 (effective January 2027) easing Scope 3 GHG bottlenecks.
In the United States, ISSB is not federal law. However, Washington space suppliers selling to UK, Australian, Japanese, or European aerospace primes still receive ISSB-formatted carbon and climate-risk data requests.
- Not U.S. federal law (SEC climate rule is dead).
- Mandatory for parent companies listed in UK, Australia, Singapore, Hong Kong, and Brazil.
- December 2025 IFRS S2 amendments ease Scope 3 Category 15/measurement friction starting Jan 2027.
| Jurisdiction | ISSB Alignment | Status (Nov 16, 2026) |
|---|---|---|
| United Kingdom / Australia / Singapore | UK SRS / AASB S2 / SGX | LIVE — Mandatory phased rollout |
| United States (Federal) | None (SEC 89 FR 21668 rescinded) | NOT ADOPTED |