LIVECalifornia SB 253 Scope 1 and Scope 2 Emissions Reporting (Cal. Health & Safety Code § 38532)
Deciding Instrument: Cal. Health & Safety Code § 38532 & 9th Cir. Injunction Denial (No. 25-5327) | Date: November 10, 2026 (Initial Scope 1+2 Deadline)
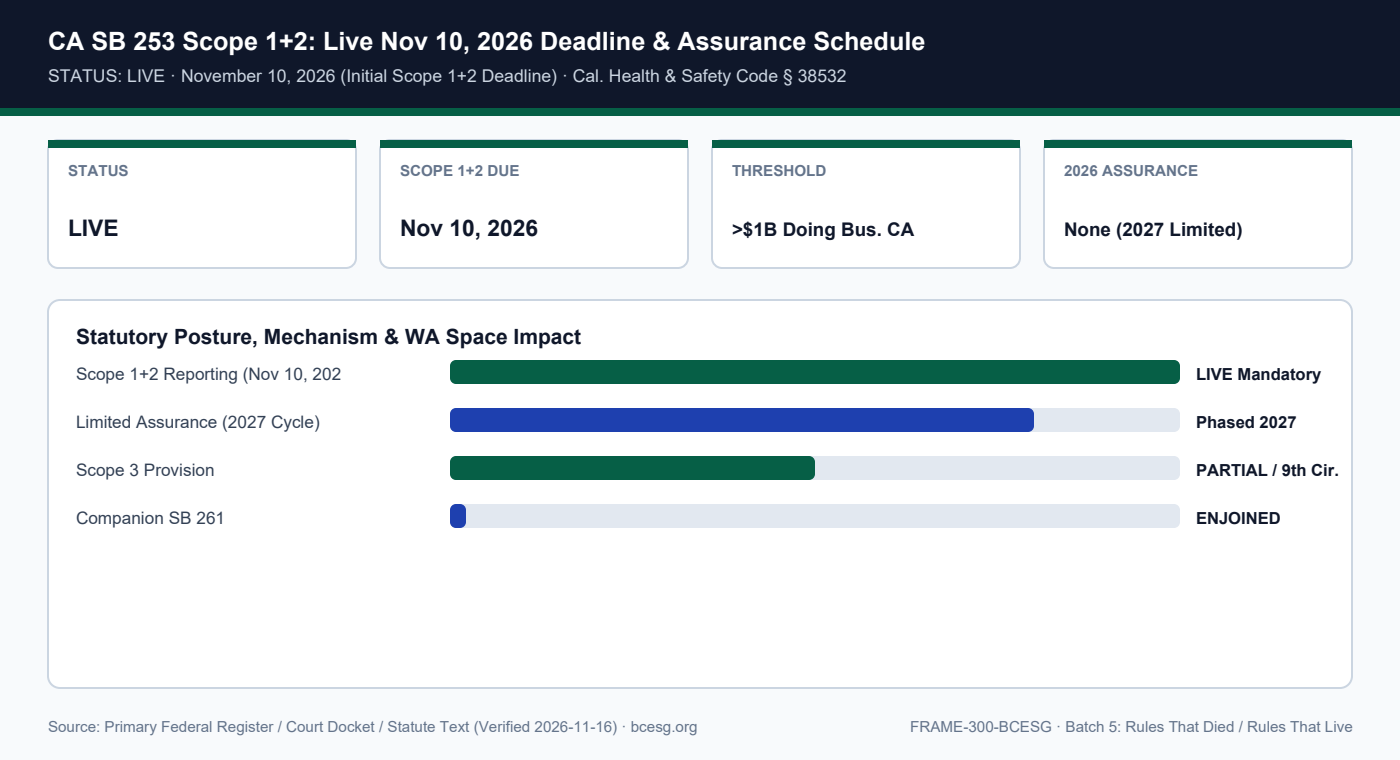
Verdict & Proof: CA SB 253 Scope 1+2 is LIVE. The Ninth Circuit declined to enjoin SB 253 (No. 25-5327), and CARB's adjusted initial Scope 1+2 reporting deadline fell on November 10, 2026 for US entities with >$1B annual revenue doing business in California (no assurance required in 2026; limited assurance starts 2027).
Who Owes What by When: >$1B CA-Nexus Entities & Nov 10, 2026
Unlike companion SB 261 (which the Ninth Circuit enjoined on November 18, 2025), SB 253 survived preliminary injunction review. CARB adjusted the original August 10, 2026 filing date to November 10, 2026 for initial prior-fiscal-year Scope 1 (direct) and Scope 2 (purchased electricity/heat) emissions.
Third-party assurance is not required for the 2026 initial cycle; limited assurance begins in 2027, escalating to reasonable assurance in 2030.
- Covered entities: US-formed corporations/partnerships with >$1B total annual revenue doing business in California.
- Initial Scope 1+2 deadline: November 10, 2026.
- Scope 3 remains contested in the Ninth Circuit and unfinalized for 2027.
| Cycle | Requirement | Deadline / Assurance |
|---|---|---|
| 2026 Initial Filing | Scope 1 + Scope 2 emissions | Nov 10, 2026 (no third-party assurance) |
| 2027 Cycle | Scope 1 + Scope 2 + Limited Assurance | 2027 (Scope 3 pending 9th Cir. & CARB) |
| 2030 Cycle | Reasonable Assurance on Scope 1+2 | Statutory target 2030 |
Impact on Washington Space Cluster Suppliers
While most mid-market Washington aerospace suppliers fall under the $1B revenue threshold, California-headquartered or CA-nexus primes (e.g., SpaceX, Northrop, Lockheed, Rocket Lab, K2 Space) are directly covered and increasingly request utility and energy intensity data from suppliers.