Updated: November 14, 2026 — Refreshed to reflect current statutory cycles, verification rules, and post-election regulatory posture.
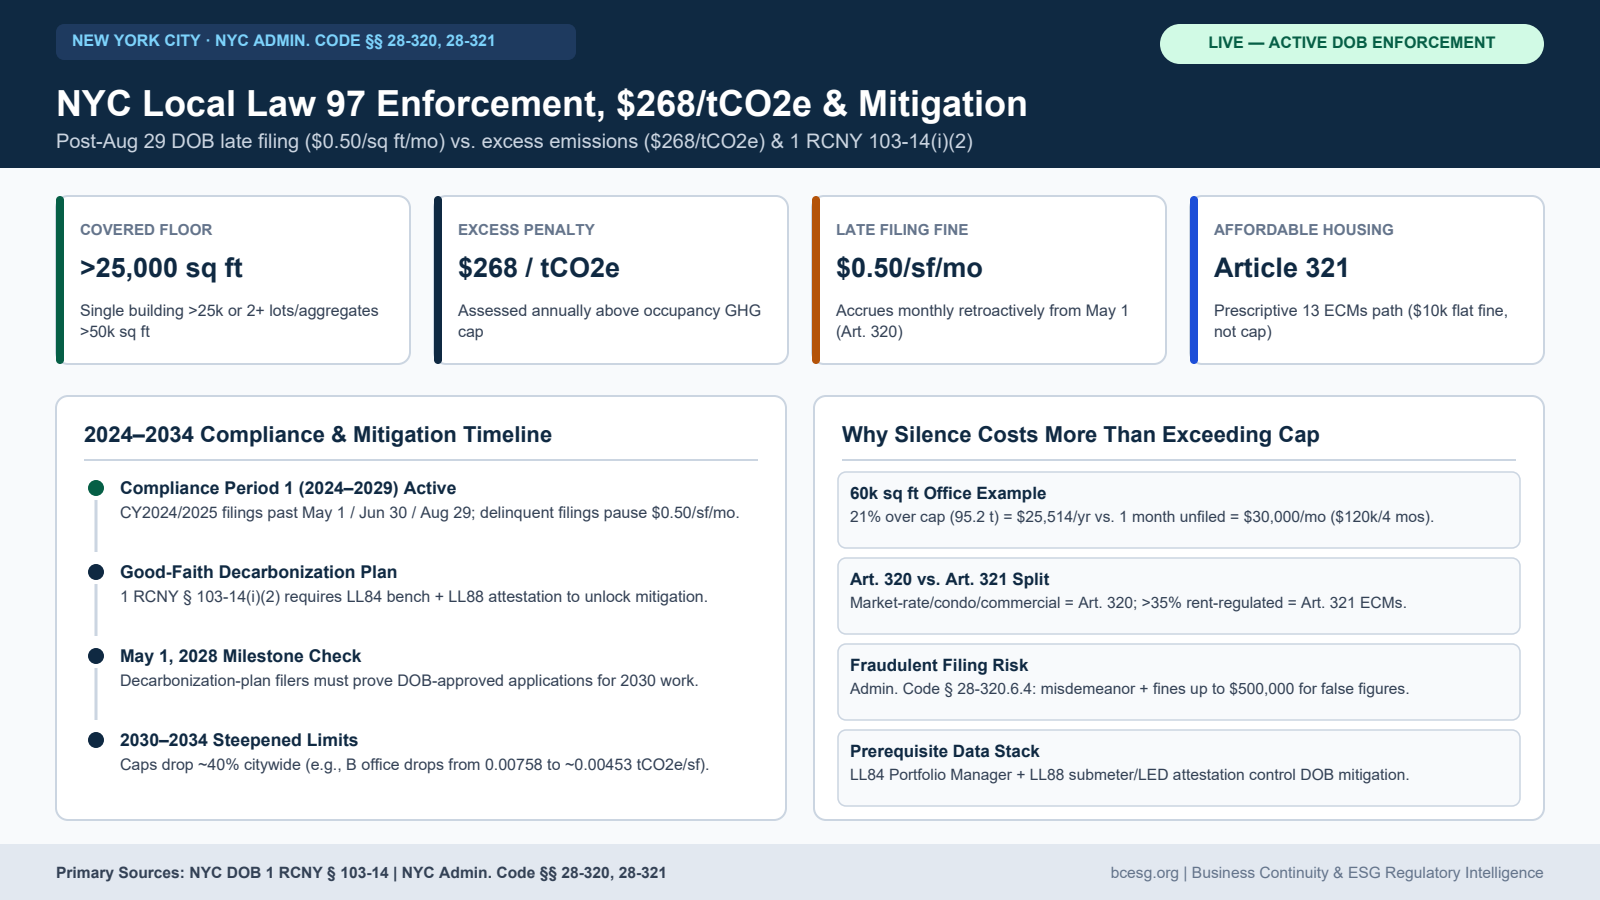
Short answer: With New York City’s Cycle 1 (2024–2029) reporting windows past May 1, June 30, and August 29 and preemption challenges rejected by the New York Court of Appeals in Glen Oaks Village Owners, Inc. v. City of New York, NYC Local Law 97 (Admin. Code §§ 28-320 & 28-321) is in full active DOB enforcement. For unfiled or delinquent covered properties (>25,000 sq ft single building, or >50,000 sq ft across multiple buildings on one tax lot), the immediate cash risk is not the carbon cap itself — it is the compounding $0.50 per square foot per month non-filing penalty running retroactively to May 1.
Once DOB receives a certified Registered Design Professional (RDP) report, monthly late fees stop accruing and evaluation shifts to the underlying occupancy-group cap (e.g., 0.00758 tCO2e/sq ft for Business Group B offices in 2024–2029) and whether the owner qualified for mitigated penalties under 1 RCNY § 103-14(i)(2). Pair this operational manual with our NYC LL84, LL88, LL97 & LL33 Calendar Guide and LL84 Benchmarking Prerequisite Walkthrough.
Statutory Status at a Glance
Covered Thresholds: Single buildings >25,000 gross sq ft; 2+ buildings on the same tax lot >50,000 sq ft; or 2+ condo buildings governed by the same board >50,000 sq ft.
Two Legal Tracks: Article 320 (market-rate commercial, institutional, and residential <=35% rent-regulated) faces annual carbon caps and $268/tCO2e fines; Article 321 (affordable/rent-regulated >35% or NYCHA/HUD-assisted) follows the one-time 13 Prescriptive Energy Conservation Measures (PECMs) or 2030 cap demonstration ($10,000 flat non-compliance fine).
Penalty Asymmetry: An unfiled 60,000 sq ft Group B office at 21% over cap incurs ~$25,514/year for emissions vs. $30,000/month ($120,000 over 4 months) simply for remaining unfiled past May 1.
Good-Faith Mitigation Gate: Under 1 RCNY § 103-14(i)(2), owners invoking a Decarbonization Plan must hold submitted LL84 benchmarking and LL88 lighting/submetering attestations on file and hit the May 1, 2028 DOB permit/approval milestone.
2030 Cliff Prep: Cycle 2 (2030–2034) drops commercial Group B office intensity caps roughly 40% (~0.00453 tCO2e/sq ft), shifting electrification economics well ahead of 2029.
Print-First Compliance Brief
Download the NYC Local Law 97 Enforcement & Mitigation Reference
2-page Print-First PDF covering DOB’s $0.50/sq ft/month vs. $268/tCO2e penalty math, Article 320 vs. Article 321 rules, and 1 RCNY § 103-14(i)(2) good-faith mitigation.
Late-Filing Mathematics vs. $268/tCO2e Carbon Caps & Criminal Misstatement Risk
Building owners who miss annual May 1 reporting (or approved June 30 / August 29 extension windows) often confuse carbon-overage liability with administrative filing delinquency. Under NYC Admin. Code § 28-320.6, the $0.50/sq ft/month failure-to-file penalty is statutory, accumulates continuously from May 1 until DOB accepts a certified filing, and cannot be waived simply because actual emissions sat below the occupancy cap.
Equally critical is filing accuracy. Under Admin. Code § 28-320.6.4, knowingly submitting a false LL97 report or fraudulent Registered Design Professional attestation is a misdemeanor carrying fines up to $500,000. Owners resolving delinquent filings must reconcile Portfolio Manager meter boundaries, co-gen/steam coefficients, and space-type square footage directly against DOB property records.
Filing First Stops the Bleed: Even if final emissions confirm an overage at $268/tCO2e, submitting the certified filing halts the monthly $0.50/sq ft clock immediately.
Extension Mechanics (1 RCNY § 103-14): Standard extensions run only through timely May 1/June 30 administrative requests; once an un-extended deadline passes, DOB treats the parcel as delinquent.
Renewable Energy Credits (RECs) & Deductions: Only NYSERDA Tier 4 NYC-deliverable RECs (credited strictly against electricity emissions) qualify — general out-of-state voluntary RECs do not offset LL97 overages.
Track & Citation
Covered Building Scope
Primary Compliance Metric
Maximum Statutory Penalty
Article 320 (2024–2029)
Commercial, condo & residential <=35% rent-regulated >25k sf
Occupancy GHG limit (e.g., 0.00758 tCO2e/sf Group B)
Steepened limits (~0.00453 tCO2e/sf Group B office)
$268/tCO2e + stricter false-filing rules
NYC Local Law 97 enforcement posture under Admin. Code §§ 28-320 and 28-321: late-filing exposure vs. excess emissions penalties and good-faith decarbonization plan prerequisites.
For Article 320 buildings unable to meet 2024–2029 limits economically on day one, 1 RCNY § 103-14(i)(2) offers mitigated penalties — provided the owner filed LL84 benchmarking on time, completed LL88 lighting and submetering attestations, and submitted a stamped Decarbonization Plan demonstrating net-zero 2050 alignment with no REC offsets allowed inside that mitigation period.
Meanwhile, Article 321 qualifying properties (buildings with >35% rent-regulated units, Mitchell-Lama, or HDFC cooperatives) operate on an entirely separate track: demonstrating compliance either with the 2030 emissions limit or installing all 13 applicable Prescriptive Energy Conservation Measures (pipe insulation, steam traps, low-flow fixtures, weatherization, etc.), where missed filings draw a $10,000 flat violation rather than $268/tCO2e.
Decarbonization Plan Lock-In: Choosing good-faith mitigation waives REC compliance through 2029 and legally commits the asset to securing DOB-approved work permits by May 1, 2028.
State-Local Portfolio Note: New York’s executive-order state benchmarking covers state-owned assets only — private NYC landlords follow LL97 and LL84 as their exclusive statutory baseline.
Compliance Execution Checklist
Step
Owner / Team
Auditable Deliverable
1. Prerequisite Gate Check
Property / Compliance
Verify LL84 Portfolio Manager acceptance and LL88 attestation on DOB NOW.
2. Art. 320 vs 321 Confirm
Legal / Tax Lot Counsel
Pull DHCR/HPD rent-regulation counts or tax-lot square footage from DOF records.
How do NYC Local Law 97 late-filing fines compare to the $268/tCO2e emissions penalty?
Under NYC Admin. Code § 28-320.6, failing to file an LL97 report incurs $0.50 per gross square foot per month starting May 1. For a 60,000 sq ft office moderately above cap, four months unfiled costs $120,000 — nearly five times a full year's $25,514 overage penalty.
What does an Article 320 Good-Faith Effort mitigation plan require?
Under 1 RCNY § 103-14(i)(2), owners must demonstrate on-time LL84 benchmarking, LL88 lighting/submetering attestation, and an RDP-stamped Decarbonization Plan with DOB-approved construction applications by May 1, 2028.
Is Local Law 97 still facing preemption litigation?
No. In Glen Oaks Village Owners, Inc. v. City of New York (2025), the New York Court of Appeals ruled in the City's favor, confirming New York State's CLCPA did not preempt NYC's local emissions caps.
Informational notice: This guide summarizes enacted statutes, regulations, or pending legislative records from the primary authorities linked above as of November 14, 2026. It is not legal, accounting, or licensed engineering advice.
LL97 emissions compliance is only as good as the energy data system underneath it. LL84-style benchmarking via ENERGY STAR Portfolio Manager is not a side quest. It is the data spine for intensity, property type, and year-over-year truth. The filing walkthrough is already here: DOB NOW, ESPM, and BEAM.
Operator checklist
Every covered BIN has a maintained ESPM property
Property type matches reality (mixed-use rules understood)
Changing property type to “game” factors without basis
Tenant meters invisible to the landlord
Different consultants using different ESPM copies
Benchmarking marked “done” while LL97 data is still wrong
If the meters are a mess, do not debate 2030 electrification first. File with honest data, then fix coverage. The non-filing estimator is what you owe while you argue about the plant.
Last verified: August 22, 2026. By Will Tygart. For co-op and condo boards and managing agents. Counsel and a Registered Design Professional (RDP) finalize. Not legal advice.
Boards hear “pathway” folklore in hallways. Article 320 and Article 321 are not vibes. They are different legal tracks with different evidence, different reports, and different failure modes. This tree forces questions before anyone votes.
Most market-rate co-ops and condos over the size threshold are Article 320 buildings. Article 321 is the lighter, more prescriptive track for certain affordable housing, buildings with more than 35% rent-regulated units, and houses of worship. Confirm which track you are on against DOB’s Covered Building List — do not take it from a group-chat rumor.
Coverage first (if you are not covered, stop)
NYC Accelerator’s working test: buildings over 25,000 gross square feet; two or more buildings on the same tax lot that together exceed 50,000; or two or more condo buildings governed by the same board of managers that together exceed 50,000. Square footage comes from Department of Finance records (BBL / BIN). Penalties apply at the BIN.
What the two articles actually are
Article 320
Article 321
Who it usually covers
Most private / market-rate covered buildings
Certain affordable housing, buildings with more than 35% rent-regulated units, houses of worship
The obligation
Annual carbon cap on building emissions from energy use
Either complete a one-time list of 13 prescriptive energy conservation measures, or meet the building’s 2030 carbon limit
Over-cap math
$268 per metric ton of CO2e over the limit for that year
Different (prescriptive / alternate) reporting and enforcement — do not import 320 penalty folklore
HDFC co-ops are commonly treated as Article 321. Ordinary market-rate co-ops and condos are commonly Article 320. Mixed buildings need a rent-roll analysis, not a slogan.
Step 0 — facts packet before the vote
Covered building? GFA / aggregate rules checked against the Covered Building List
Rent-regulated share estimate with a source (rent roll, not memory)
Dual-period calculator output if you are on (or might be on) 320
Last verified: August 22, 2026. By Will Tygart. Written for co-op and condo boards and the managing agents who serve them. Not legal advice — counsel and a Registered Design Professional (RDP) finalize language and pathway calls.
Co-op and condo Local Law 97 work usually dies in governance before it dies in engineering: unclear authority, unfunded mandates, a late RDP, and a pathway decision nobody minuted. This checklist is the meeting-ready spine. Pair it with the live co-op and condo LL97 playbook and the $268-per-ton calculator.
2026 filing clock (do not skip this)
NYC Accelerator and DOB still run the same three-step file: pay the fee in DOB NOW, share energy data in ENERGY STAR Portfolio Manager, then submit in BEAM with an RDP. The annual report is due May 1, with a 60-day grace period through June 30. For 2026, buildings that need more time may apply in BEAM by June 30 for a $60 extension that runs through August 29, 2026. Missing the file is a different (and often worse) problem than being over cap.
Confirm your building is on DOB’s Covered Building List before you argue pathway folklore in the hallway.
Pre-meeting packet (managing agent / president)
Latest ENERGY STAR Portfolio Manager property type(s) and gross floor area assumptions
Dual-period calculator printout (current period vs 2030)
Filing status: submitted / in grace / extension / not started
RDP engagement letter status and fee range
Reserve study excerpt (energy / capital)
Pathway status if anyone is talking Article 320 vs 321 — with evidence, not rumor
Primary sources checked this pass: NYC Accelerator LL97 page (coverage, Article 320 vs 321, 2026 extension), NYC DOB LL97 greenhouse gas reductions page, and the live BCESG co-op playbook.
In too many organizations, sustainability owns ESPM, risk owns the BCP binder, and insurance owns the renewal submission. Those packets should share DNA. LL97 forces annual, building-level truth about energy and emissions. Continuity forces truth about what breaks. Insurers and lenders ask questions that sit in the overlap.
Store calculator outputs with the risk file, not only the ESG folder
Days 31–60 — shared packet
One digital binder per priority asset: LL97 summary (current + 2030), critical systems list (power, heat, life safety, elevators, BMS), vendor call tree, last incident log, open CapEx that improves both intensity and resilience.
Days 61–90 — negotiation use
Bring the packet to renewal meetings. Use 2030 exposure as a capital-prioritization argument, not a scare PDF. Align continuity tests with systems that dominate emissions (central plants).
Last verified: August 22, 2026. By Will Tygart. Not legal advice. Pathway and adjustment eligibility are building-specific.
Missing a cap is a management problem, not only a payment problem. DOB and counterparties look for credible, documented effort: accurate data, timely filing, professional involvement, and a path that could work.
Last verified: August 22, 2026. By Will Tygart. Read with the LL97 penalty calculator. Not legal advice. Confirm factors against 1 RCNY 103-14 and your RDP before any CapEx memo.
Local Law 97 already has real reporting and penalty mechanics. The strategic shock for many portfolios is January 1, 2030, when emissions limits tighten sharply by property type. A building that looks “fine” under 2024–2029 factors can face a large annual overage in 2030 at the same energy use.
NYC Accelerator’s public read of 2024 benchmarking: less than 10% of properties exceeded the first-period cap; about 57% are projected to exceed 2030–2034 limits. That is the planning problem.
How limits work (refresher)
Annual building emissions are compared to a limit derived from gross floor area × an emissions factor for the building’s ENERGY STAR Portfolio Manager property type (with mixed-use weighting). Overage metric tons × $268 is the statutory penalty-rate context used on this site. Factors and elections can be nuanced. Always confirm against 1 RCNY 103-14.
Why 2030 is a different planning problem
Period
Planning posture
2024–2029 limits
Data quality, file on time, quick efficiency wins, document good faith
2030+ limits
CapEx sequencing, electrification pathways, tenant energy strategy, capital reserves, possible pathway elections
Illustrative relative tightening — order-of-magnitude language for prioritization, not legal limits. Re-verify exact factors from the rule text:
Office — very large drop in allowed intensity (often cited in the ~65% class in explanatory materials)
Retail — among the steepest intensity cuts
Warehouse — steep cuts
Multifamily — material, often cited as less steep than office/retail (~50% class)
Data centers — material; still portfolio-specific
The calculator and 1 RCNY tables are the math source of truth. Do not put the percentages above into a board resolution as if they were the Code.
Scenario A — compliant now, exposed later
Profile: office or retail with solid 2025–2026 reporting, modest overage or none under current factors.
Risk: same EUI in 2030 → large annual penalty.
Run dual-period calculator outputs for the asset
Build a 2027–2029 CapEx path (envelope, HVAC, controls, electrification readiness)
Align board reserve studies or CapEx committees to 2030, not only the next audit
Tie vendor RFPs to measurable intensity outcomes
Scenario B — filing is the emergency; 2030 is the strategy
Profile: behind on 2026 reporting, RDP not booked, ESPM messy.
Parallel track: data hygiene now, retrofit roadmap after the first clean filing year
Scenario C — portfolio mix
Rank assets by 2030 gap × square footage × hold period. One capital plan applied to office + multifamily + industrial wastes money. Sell / hold / renovate decisions include the LL97 path, not only NOI.
Scenario D — board-governed housing
Co-op / condo split incentives. Use the board resolution checklist (scheduled) and the live co-op playbook. Multi-year assessment funding — not a single annual surprise.
Worked thinking (illustrative only)
Take a 100,000 sq ft office with stable operations. Compute limit and emissions under current-period factors. Recompute with 2030 factors for the same property type. Delta tons × $268 = order-of-magnitude annual exposure if nothing changes. Compare that annuity to retrofit debt service. If the 2030 annuity exceeds credible efficiency financing, the conversation is asset strategy, not a compliance project.
This quarter
Dual-period estimate for every covered asset
Flag the top quartile of 2030 exposure
Book RDP / energy capacity before bottleneck seasons
Last verified: August 22, 2026. By Will Tygart. Companion to the $268/ton overage calculator. Not legal advice. Confirm current Code and DOB enforcement language with your RDP and counsel before you rely on any number.
Owners fixate on overage math and ignore non-filing math. Those are different triggers. In a lot of real buildings, stalling the report creates a monthly exposure that can outrun a year’s overage penalty — especially on large floor plates.
The working formula
Market explainers and our calculator FAQ use this pattern for failure to file:
That is the figure used across 2026 practitioner writeups (and it matches the “up to $0.50 per square foot per month” language boards hear from counsel). Retroactivity and how DOB applies your BIN still have to be confirmed. Do not treat this table as a bill.
GFA (sq ft)
≈ Monthly
≈ 3 months
≈ 6 months
25,000
$12,500
$37,500
$75,000
50,000
$25,000
$75,000
$150,000
60,000
$30,000
$90,000
$180,000
100,000
$50,000
$150,000
$300,000
200,000
$100,000
$300,000
$600,000
False-statement penalties are a different animal (fixed, severe). Do not mix them into this table.
Estimate non-filing monthly exposure with the table above
Compare time-to-file cost vs RDP + filing cost
If you are inside a grace or extension window, read the deadline guide today. For 2026: May 1 due, grace through June 30, $60 BEAM extension through August 29 if you actually apply.
Decision tree
Filed this cycle? Monitor acceptance, keep artifacts, shift focus to 2030 intensity.
Not filed, can file within days? Prioritize filing over retrofit debates.
Need the extension? Calendar the BEAM action before June 30.
Data chaos? Buy RDP time immediately. The non-filing meter is the emergency, not the plant replacement meeting.
FAQ
Is non-filing the same as exceeding the cap? No. Different trigger, different math.
Does an extension erase non-filing risk forever? No. It changes the filing date if properly obtained.
Should boards see this table? Yes. It funds an emergency resolution faster than “compliance risk” as an abstract.
Last verified: August 22, 2026. By Will Tygart. Operations calendar for owners and PMs — not a legal instrument. Deadlines move by DOB service notice; re-check the current PDF before you file.
If you operate covered NYC buildings, put three dates on the portfolio dashboard and treat everything else as runway: May 1, June 30, and — if you actually applied — August 29. The 2030 limit cliff is real, but it does not excuse a missed 2026 file.
2026 — filing year
When
What
Ops note
May 1, 2026
LL97 report for calendar-year 2025 emissions (typical due date)
Same season as LL84 / LL88 May 1 patterns. Pay the fee in DOB NOW, share data in ENERGY STAR Portfolio Manager, submit in BEAM with an RDP.
May 1 → June 30, 2026
60-day grace window used in city communications
Do not treat grace as a plan.
June 30, 2026
Last day commonly cited to apply in BEAM for the $60 extension
Extension is an action, not automatic.
August 29, 2026
Extended LL97 filing date if the extension was properly obtained
Keep the ticket and approval artifacts.
October (LL33 / energy grade)
Energy grade label posting window
This is a public / tenant moment, not only a compliance chore.
December 31 (LL87, if in cycle)
Energy efficiency report cycles for buildings in-year
Document disaster impacts that affect energy evidence
2030 — limit cliff
January 1, 2030 is when tighter emissions limits by property type take effect for the next compliance regime. A building that looks fine under 2024–2029 factors can face a large annual overage in 2030 at the same energy use. Run the $268 calculator in both periods before you fund a one-year story.
How to use this in a PM shop
Assign a named human per BIN for filing season
Put May 1 / June 30 / August 29 on the portfolio dashboard
Link each BIN to calculator output plus RDP contact
Review October grade posting as a tenant/public moment
Sources this pass: NYC Accelerator LL97 page (2026 extension), DOB LL97 page, Feb 27 2026 sustainability deadline service notice as cited by Accelerator, and the live BCESG deadline walkthrough.
Updated: November 14, 2026 — Refreshed to reflect current statutory cycles, verification rules, and post-election regulatory posture.
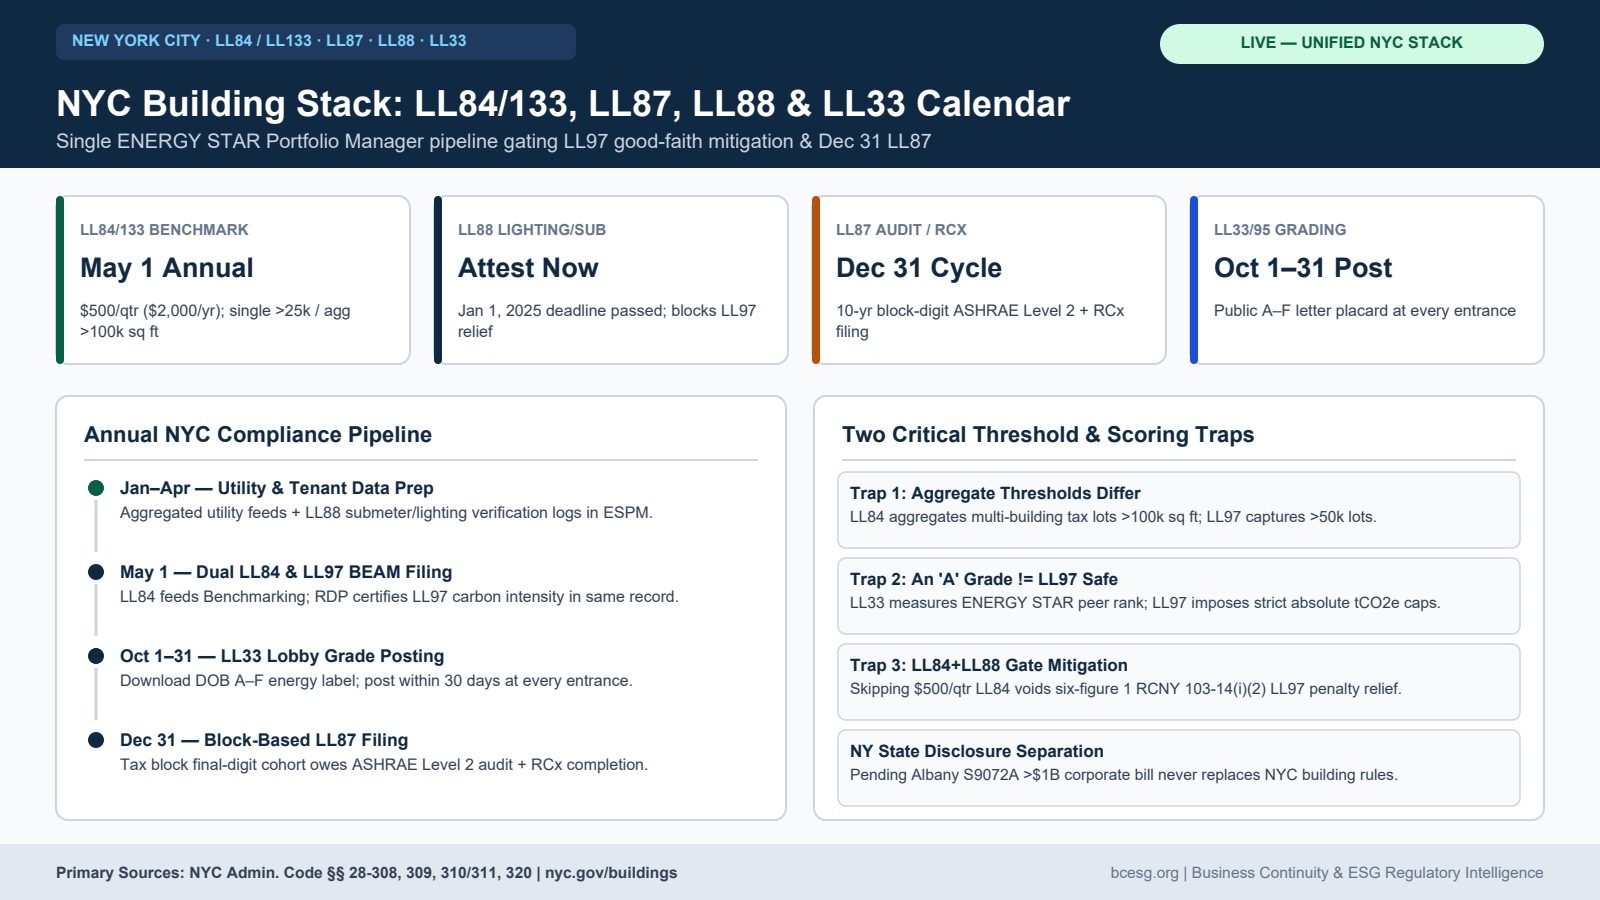
Short answer: New York City property managers do not face four isolated rules — Local Laws 84/133 (Benchmarking), LL87 (10-year Audits & RCx), LL88 (Lighting & Submetering), and LL33/95 (Energy Letter Grades) operate as an interconnected compliance data stack administered by the NYC Department of Buildings (DOB). Most critically, timely LL84 submissions and LL88 attestations act as legal gatekeepers for mitigated penalties under NYC Local Law 97.
Separating them creates recurring surprises: quarterly late fines on May 1 LL84 benchmarking automatically sabotage October LL33/95 building grades (triggering a public ‘F’ grade for unsubmitted properties and a $1,250 fine), while overlooking a tax-block-digit December 31 LL87 audit due date blocks access to DOB decarbonization relief. See also our dedicated LL84 Prerequisite Technical Walkthrough.
Statutory Status at a Glance
LL84 / LL133 Benchmarking (May 1 Annual): Whole-building electricity, gas, fuel oil, steam, and water consumption for >=25,000 sq ft properties via ENERGY STAR Portfolio Manager; quarterly non-filing fines ($500/qtr up to $2,000/yr).
LL33 / LL95 Energy Letter Grades (Oct 1–31 Annual): Owners download DOB NOW Energy Efficiency Labels starting October 1 and display A–D/N/F grades at every public entrance within 30 days ($1,250 penalty).
LL88 Lighting & Submetering (Active Jan 1, 2025+): Mandates NYC Energy Conservation Code-compliant lighting across non-residential buildings >25,000 sq ft and residential common areas, plus electrical submeters for non-residential tenant spaces >5,000 sq ft.
LL87 Audits & Retro-Commissioning (Dec 31 10-Yr Rotation): Buildings >50,000 sq ft submit Energy Efficiency Reports (EER) by December 31 in the year matching the final digit of their NYC Tax Block number (e.g., Block ending in 6 -> Dec 31, 2026).
Print-First Compliance Brief
Download the NYC Four-Law Building Compliance Calendar
2-page Print-First PDF syncing LL84 benchmarking, LL33/95 grade posting, LL88 submetering/LEDs, and LL87 10-year EER audits into one annual calendar.
Even though DOB administers separate violation numbers for LL84 ($500 quarterly benchmarking fine), LL88 ($1,500 initial + monthly non-submetering penalties), and LL87 ($3,000 initial + $5,000/yr late EER fines), their operational interconnection is tight. DOB’s Good-Faith Effort criteria under 1 RCNY § 103-14(i)(2) explicitly verify that an owner submitted timely LL84 benchmarking data and valid LL88 attestations before granting mitigated LL97 penalties.
Meanwhile, LL84 utility feeds populate both your LL33 lobby letter grade and the exact meter inventory imported by your Registered Design Professional for annual LL97 emissions filings — meaning meter omissions fixed once in Portfolio Manager protect four filings simultaneously.
Con Edison & National Grid Aggregation: Request automated whole-building utility uploads at least 45 days before May 1 to prevent estimated billing gaps that trigger DOB data flags.
Tenant Submeter Exception Check (LL88): Non-residential leases executed strictly below 5,000 sq ft on single-tenant floors remain exempt from individual submetering unless aggregated on the same floor above 5,000 sq ft.
LL33 Score Cutoffs: Grade A (>=85 ENERGY STAR), B (70–84), C (55–69), D (1–54), N (exempt/unscorable property types), F (failed to submit LL84 benchmarking).
Local Law & Citation
Threshold & Coverage
Deadline / Cadence
Statutory Violation Exposure
LL84 / LL133 (§ 28-309)
Single bldgs >=25k sf; multi-bldg tax lots >=100k sf
Annual May 1 (ENERGY STAR PM)
$500/quarter ($2,000/yr cap) + triggers F grade
LL33 / LL95 (§ 28-309.12)
Covered LL84 buildings >=25k sf
Download Oct 1; post by Oct 31
$1,250 annual non-posting DOB fine
LL88 (§§ 28-310, 28-311)
Nonres >25k sf lighting; tenant spaces >5k sf submeters
Compliance active Jan 1, 2025+
$1,500 initial + per-submeter fines + blocks LL97 relief
LL87 (§ 28-308)
Buildings >50k sf (or multi-bldg lots >100k sf)
Dec 31 on 10-yr Tax Block last digit
$3,000 year 1; $5,000 each subsequent yr late
How NYC DOB integrates LL84/133 benchmarking, LL33/95 letter grades, LL88 lighting/submetering, and LL87 10-year audits into a prerequisite stack for LL97 mitigation.
Sequencing One 12-Month NYC Building Compliance Calendar
Rather than scrambling around four disconnected dates, commercial and multifamily asset teams should align accounting and engineering reviews into four quarterly gates covering utility verification, May 1 Portfolio Manager uploads, October lobby label posting, and December 31 LL87 rotation checks.
Q1 (Jan–Mar): Verify ConEd/National Grid whole-building feeds and check whether the NYC Tax Block final digit triggers a December 31 LL87 Energy Efficiency Report.
Q2 (May 1): Submit annual LL84/133 Portfolio Manager benchmarking + LL97/LL88 attestations in DOB NOW.
Q4 (Oct 1–31 & Dec 31): Download and post LL33 letter grades at all entrances by October 31; file due-year LL87 EERs by December 31 ($3,000–$5,000 avoided).
Compliance Execution Checklist
Step
Owner / Team
Auditable Deliverable
1. Utility Meter Audit
Property Manager
Reconcile ConEd/National Grid whole-building CSV accounts in Portfolio Manager.
2. May 1 Joint Window
Compliance / RDP
File LL84 benchmarking alongside LL88 and LL97 filings before May 1.
3. Oct 31 Lobby Grade
Building Operations
Print DOB NOW Energy Efficiency Label and post in public lobby + photo proof.
4. Block-Digit LL87 Check
Engineering Lead
Verify NYC Tax Block final digit against upcoming Dec 31 EER audit cohort.
Field & Print Package
Keep This New York City, NY Compliance Checklist Handy
Download the formatted 2-page PDF reference brief or pull the structured Markdown edition for internal compliance documentation.
Which NYC buildings owe LL84 benchmarking vs. LL87 energy audits?
LL84/133 benchmarking applies annually starting at >=25,000 sq ft, whereas LL87 10-year Energy Efficiency Reports (audits and retro-commissioning) apply at >50,000 sq ft (or multi-building lots >100,000 sq ft) on a Tax Block last-digit schedule.
What happens if I miss LL84 benchmarking before October LL33 grade issuance?
NYC DOB issues an automatic 'F' Energy Efficiency Grade in October, triggers $500 quarterly benchmarking fines, and renders your building ineligible for 1 RCNY § 103-14(i)(2) LL97 penalty mitigation.
How is my Local Law 87 due date determined?
Your 10-year LL87 EER deadline falls on December 31 of the calendar year whose last digit matches the final digit of your NYC Tax Block number (e.g., Tax Block 1206 is due December 31, 2026).
Informational notice: This guide summarizes enacted statutes, regulations, or pending legislative records from the primary authorities linked above as of November 14, 2026. It is not legal, accounting, or licensed engineering advice.
Use the calculator below for $268-per-ton LL97 excess-emissions math from 1 RCNY 103-14; confirm penalties and filing status in DOB records — this page does not state outcomes for your building.
A Local Law 97 fine is calculated in one line: (your building’s actual annual emissions − its emissions limit) × $268 per metric ton of CO2e, assessed every year you remain over the cap. The limit is your gross floor area times a published factor for your property type — 0.00758 tCO2e per square foot for an office today, falling to 0.002690852 in 2030. The separate failure-to-file penalty is gross floor area × $0.50 per month. Use the calculator below for your building, then read the part nobody’s calculator shows you: what the 2030 factors do to a building that is comfortably compliant today.
LL97 Penalty Calculator — emissions factors as printed in 1 RCNY 103-14(c)(3); penalty rate $268/tCO2e per Admin Code §28-320.6.
Estimates only. Mixed-use buildings use square-footage-weighted factors; for 2024–2025 owners could elect the statutory occupancy-group limits instead; good-faith-efforts mitigation, RECs, AHRF offsets, and the disaster provision can reduce penalties. Always confirm against 1 RCNY 103-14 and your Registered Design Professional.
The formula, worked by hand
Take a 60,000 sq ft Midtown office building:
Limit today: 60,000 × 0.00758 = 454.8 tCO2e/year
If it emits 550 tCO2e: (550 − 454.8) × $268 = $25,514/year
If it never files: 60,000 × $0.50 = $30,000/month — one month of silence costs more than a year of being 21% over the cap. Whatever else is true about your building, file.
The 2030 cliff, in numbers nobody publishes
Most LL97 coverage says the 2030 limits get “roughly 40% stricter.” The actual factors in the rule (1 RCNY 103-14(c)(3)(iii)) are far more dramatic for some property types:
ESPM property type
2024–2029 factor
2030–2034 factor
Reduction
Office
0.00758
0.002690852
−65%
Multifamily Housing
0.00675
0.003346640
−50%
Hotel
0.00987
0.003850668
−61%
Retail Store
0.00758
0.002104490
−72%
Non-Refrigerated Warehouse
0.00426
0.000883187
−79%
Hospital
0.02381
0.007335204
−69%
Data Center
0.02381
0.014791131
−38%
Restaurant
0.01181
0.004038374
−66%
K-12 School
0.00675
0.002230588
−67%
Medical Office
0.01074
0.002912778
−73%
(Factors are tCO2e per square foot per year, as printed in the rule. The 2030 table also cuts the grid-electricity coefficient roughly in half — to 0.000145 tCO2e/kWh — reflecting expected grid cleanup, which softens the blow for electrified buildings specifically.)
What that does to a real building: the same 60,000 sq ft office emitting 400 tCO2e is comfortably under its 454.8-ton cap today — penalty $0. In 2030 its cap drops to 161.5 tons. Same building, same energy use: 238.5 tons over, $63,931 per year, every year. That is why Urban Green’s finding — only ~9% of properties exceed today’s caps but ~57% exceed the 2030 caps — is the single most important number in NYC real estate planning, and why a “we’re compliant” answer in 2026 is only half an answer.
The fines-versus-retrofit math, honestly
Some owners are paying. Habitat’s reporting quotes a senior official at a prominent real estate firm: eliminating the fines would mean investing “15 to 20 times the fine amount,” and an energy manager’s example pits an $8–10M retrofit against a ~$180,000-a-year penalty (Habitat, March 2025). For 2026, that arithmetic can be rational.
It stops being rational on three clocks. First, fines repeat annually, forever — a $180K/year penalty is $1.8M over a decade against a one-time retrofit. Second, the 2030 factors multiply the overage: the building paying $180K today may be paying three to five times that from 2030. Third, equipment dies on its own schedule anyway — the cheapest compliance is the boiler you were already replacing, replaced electric, with beneficial-electrification credits that are richest before December 2026. REBNY projects citywide fines approaching $900 million a year once the 2030 limits bite — the buildings that avoid contributing to that number are the ones doing the math now, while the retrofit can ride the capital calendar instead of fighting it.
Five things that legitimately reduce an LL97 penalty
Good-faith-efforts mitigation (1 RCNY 103-14(i)(2)) — requires a filed report, current LL84 benchmarking, and LL88 attestation, plus a qualifying path such as an RDP-certified decarbonization plan or an approved application for compliance work.
RECs — offset electricity-attributable emissions only, must be NYC-deliverable, currently uncapped (decarbonization-plan filers excluded); Zone J Tier 4 supply (CHPE, Clean Path NY) becomes materially available during 2026.
AHRF offsets — capped at 10% of your limit, priced at $268/ton (deliberately equal to the penalty), funding affordable-housing decarbonization.
The disaster provision (1 RCNY 103-14(i)(1)) — documented hurricane, severe flooding, or fire damage that precluded compliance can zero the year’s penalty. Your restoration contractor’s job file is the evidence; see what LL97 does and does not count.
Mediated resolution — a negotiated DOB compliance plan in lieu of penalty, case by case.
What this means for each seat at the table
If you are the…
The penalty math says…
Owner
Run the calculator twice — today’s factor and 2030’s. The second number belongs in the capital plan and the next refinancing conversation, because lenders are already running it.
Facility / property manager
Your energy data is the input to a six-figure equation. Tight ESPM records, submetering, and vendor documentation are what make the difference between an estimated overage and a defended one.
Tenant
Your consumption is inside the building’s number, and lease structures increasingly pass LL97 exposure through. A tenant who can demonstrate efficiency is negotiating leverage; one who cannot is a cost center.
Frequently asked questions
How are Local Law 97 fines calculated?
(Actual annual building emissions − the building’s emissions limit) × $268 per metric ton CO2e, assessed annually. The limit is gross floor area × the published factor for your ESPM property type — 0.00758 tCO2e/sqft for offices in 2024–2029, dropping to 0.002690852 in 2030.
How much is the LL97 penalty per ton?
$268 per metric ton of CO2e over the limit, per year. The Affordable Housing Reinvestment Fund offset is deliberately priced at the same $268 — the city set the escape hatch at exactly the cost of the penalty.
What is the penalty for not filing an LL97 report?
Gross floor area × $0.50 per month, retroactive to May 1 of the filing year. On a 60,000 sq ft building that is $30,000 a month — typically far worse than the overage penalty itself.
When do LL97 fines start?
They already have: caps took effect January 1, 2024, first reports were due in 2025, and DOB confirmed in April 2026 that ~1,400 non-filers are in the enforcement pipeline with OATH cases in preparation. The much larger fine wave arrives with the 2030 limits, which roughly 57% of covered buildings currently exceed.
How much stricter do LL97 limits get in 2030?
It depends on property type: offices drop 65%, retail 72%, warehouses 79%, multifamily 50%, data centers 38% — per the factors printed in 1 RCNY 103-14(c)(3)(iii). A building comfortably compliant today can face a six-figure annual penalty in 2030 at the same energy use.
Is there an official LL97 penalty calculator?
DOB publishes the factors and formula but no official calculator; NYC Accelerator’s Building Energy Snapshot is the closest city tool. The calculator on this page applies the rule’s printed factors directly and shows both compliance periods side by side.
If the number is real: the good-faith mitigation path
The calculator above gives you the statutory exposure. What it cannot show is the mitigation mechanism DOB built into the same rule. Under 1 RCNY \u00a7 103-14(i)(2), an owner facing penalties in the 2024\u20132029 compliance period can seek mitigation by demonstrating good faith efforts \u2014 the fine is negotiated down or deferred through a mediated resolution, in exchange for documented, verifiable progress toward compliance.
The standing prerequisites (all three, before any pathway counts):
Your annual building emissions report is filed, and you are complying with any adjustment DOB has granted.
You are in compliance with Local Law 84 benchmarking.
You are in compliance with Local Law 88 lighting upgrades and submetering.
The principal pathway is a Decarbonization Plan: an energy audit and equipment inventory, concrete timelines and financing, and projected reductions on a path to net zero by 2050 \u2014 structured to bring the building within its 2024 limit within two years of submission, with DOB-approved applications in place by May 1, 2028 for the work the stricter 2030\u20132034 limits will require. Other qualifying showings include a financial-hardship adjustment under Administrative Code \u00a7 28-320.7 and, from 2025, having been under the prior year\u2019s limit.
Read the protection correctly: it is conditional, not a waiver. Mitigation holds while the milestones hold. Miss them and DOB can cancel the arrangement and assess the deferred penalties retroactively. Two more mechanics matter to the math: renewable energy credits remain uncapped for electricity emissions in this period but qualify only from Tier 4 projects delivering into New York City (Champlain Hudson Power Express, Clean Path New York); and a building on the Decarbonization Plan pathway gives up REC use for the cycle \u2014 the plan route demands physical reductions, not purchased ones.
Confirm your building\u2019s status and any mitigation filing in DOB records; this page explains the mechanism and does not state an outcome for any specific building.
Updated Nov 2, 2026 — refreshed 2027 board budgeting playbook, reserve study financing stack, Article 321 census protocols, and statutory relief pathways.
As of October 6, 2026, co-op and condo boards should confirm LL97 pathway and CY2025 filing status in BEAM; the June 30 and August 29, 2026 filing deadlines have passed — this guide does not state outcomes for any building.
November 2026 Board Action Checklist: 2027 Budget & Reserve Decisions
With 2027 annual budget and reserve study cycles commencing this month, co-op and condominium boards must execute this four-step statutory triage before levying capital assessments or approving debt packages:
Verify LL33 Label Posting & ESPM Cleanliness: Confirm physical entrance posting of the building’s 2026 Energy Efficiency Rating label (statutory deadline: October 31). Verify that prior-year Local Law 84 benchmarking in Portfolio Manager is reconciled without missing meter records; under 1 RCNY § 103-14, clean benchmarking is a mandatory prerequisite before DOB will review any mediated penalty relief or Decarbonization Plan filing.
Calculate 2024–2029 Statutory Penalty Exposure: Calculate your property’s net emissions penalty liability using gross floor area, fuel splits, and the statutory penalty coefficient of $268 per metric ton of CO2e ($268/tCO2e) over the Article 320 occupancy limit. Model baseline exposure using the Local Law 97 fines calculator ($268/ton).
Execute the Article 321 Census Test: Audit the building’s certified rent roll. Under NYC Administrative Code § 28-321, if more than 35% of dwelling units are rent-regulated or rent-stabilized, the building is legally exempt from Article 320 annual carbon caps and $268/ton fines. The board pivots immediately to verifying completion of the 13 Prescriptive Energy Conservation Measures (ECMs) rather than levying electrification special assessments. Compare pathway requirements in the Article 320 vs 321 decision guide.
Evaluate § 28-320.7 Financial Hardship Relief (2035 Cap Deferral): For Article 320 properties facing acute capital constraints, determine whether the building’s average unit assessed valuation is below $65,000 per unit or capital retrofit outlays exceed 10% of property assessed value. Under NYC Administrative Code § 28-320.7 and 1 RCNY § 103-12, qualifying properties may petition the DOB for statutory adjustment and delayed compliance through 2035.
If your co-op or condo building is over 25,000 square feet, Local Law 97 applies to you — but which version applies, and what it costs, depends on your building’s rent-regulation mix, and 2026 is the year one of the gentler pathways gets real. The legal challenge is over (the Glen Oaks suit — brought by a Queens co-op — lost at New York’s highest court in May 2025, with no appeal possible), the Council bill to delay penalties for moderate-value condos and co-ops died at the end of session, and multifamily buildings filed their first-year reports at a 94% rate. The question for boards is no longer whether LL97 is happening. It is which pathway you are on, and what the next capital plan should assume.
First question: which pathway is your building on?
LL97 is not one rule for all residential buildings — coverage splits on rent regulation and affordability status (DOB LL97 page):
Pathway
Who is on it
What applies
Article 320, standard (Pathway 0)
Most market-rate co-ops and condos >25,000 sqft (or condo buildings sharing a board totaling >50,000 sqft)
Emissions caps from 2024, annual RDP-certified reports, $268/tCO2e overage penalties
Article 320, 2026 start (Pathway 1)
Buildings with at least one but no more than 35% rent-regulated units
Cap compliance began January 1, 2026 — this year is their first capped year
Article 320, 2035 start (Pathway 2)
Certain buildings under §28-320.3.9
Caps begin 2035
Article 321, prescriptive (Pathway 3)
>35% rent-regulated, HDFC co-ops, Mitchell-Lama, income-restricted, project-based federal housing
One-time prescriptive energy measures (a defined checklist of upgrades) instead of caps; $10,000 penalties for non-compliance
Your pathway is shown on the Covered Buildings List published each year on DOB’s LL97 page; disputes go through a BEAM portal ticket. If your building has a mix of rent-regulated units, checking the percentage against DOF records is the single highest-value hour a managing agent can spend this year — Pathway 1 buildings are in their first capped year right now, and many boards do not know it.
The math boards actually face
The multifamily emissions cap for 2024–2029 is 0.00675 tCO2e per square foot (1 RCNY 103-14). For a 120,000 sq ft co-op, that is an annual limit of 810 tCO2e. Exceed it by 100 tons and the penalty is $26,800 a year. Fail to file at all and the penalty is 120,000 × $0.50 = $60,000 per month — which is why “we’re under the cap so we don’t need to do anything” is the most expensive sentence in co-op governance. Filing is mandatory regardless of emissions; for most buildings under the cap it costs the $210 fee plus the engineer.
About 9% of covered properties exceed today’s caps — but roughly 57% exceed the 2030 caps (Urban Green Council). For residential boards the 2030 number is the one that belongs in the reserve study, because the realistic retrofit menu — heat pump conversions, window and envelope work, boiler replacement timed to end-of-life — takes more than one budget cycle to finance and execute. Habitat’s reporting captured the honest owner calculus: some owners are choosing fines over retrofits because, as one put it, eliminating the fine would cost “15 to 20 times the fine amount” (Habitat, March 2025). That math can be rational in 2026 — and flips as the caps tighten and the fines repeat annually, forever.
What boards hoping for a rescue should know
The lawsuit is over. Glen Oaks Village Owners — a Queens garden co-op — argued the state climate law preempted LL97. The NY Court of Appeals rejected the challenge on May 22, 2025 (opinion); as a state-law ruling from the highest court, it cannot be appealed further.
The relief bills stalled. Int 1197 (Lee/Ung), which would have delayed penalties for condos and co-ops with average unit assessed value under $65,000, was never moved by the Speaker; Int 1180’s REC cap also died at end of session. No amendment has touched the $268 rate, the caps, or the May 1 cycle.
Enforcement has started. DOB’s April 22, 2026 release: 93% of covered properties filed, ~1,400 non-filers are receiving Notices of Deficiency, and OATH penalty cases are being prepared (DOB press release).
The board playbook for 2026
October 2026 status: The June 30, 2026 statutory deadline and the August 29, 2026 extended deadline (for buildings that secured a $60 extension by June 30) are both in the past. Use DOB BEAM and DOB NOW records to verify whether your building filed; this article does not state filing outcomes for any property.
Confirm your pathway and filing status in BEAM today. As of October 6, 2026, the June 30, 2026 and August 29, 2026 CY2025 filing deadlines have passed; verify whether your building filed rather than assuming an outcome. See the LL97 2026 deadlines reference.
Get the real number before the meeting. An energy audit that converts “we might be over” into “we are 110 tons over, which is $29,480 a year, and these three measures close 80% of it” changes the quality of every board conversation that follows.
Time retrofits to equipment life, not to panic. The cheapest decarbonization is the boiler you were going to replace anyway, replaced with the electric option, with the beneficial-electrification credits that remain richest before December 2026.
Know the mitigation menu before you need it: good-faith-efforts (requires filed reports + current LL84 + LL88 attestation plus a qualifying path like an RDP-certified decarbonization plan); RECs (electricity-attributable emissions only, NYC-deliverable); AHRF offsets (capped at 10% of your limit, $268/ton); and after a fire or flood, the disaster provision that can zero a penalty year with documentation (1 RCNY 103-14(i)(1)).
Use the free help.NYC Accelerator provides no-cost LL97 compliance guidance, and the Building Energy Exchange published a co-op/condo-specific playbook, Cutting Carbon in Co-ops & Condos, in May 2026.
What this means for each seat at the table
If you are the…
LL97 in 2026 means…
Board (the owner)
The penalty exposure and the capital plan are yours. Put the 2030 number in the reserve study now; annual fines are a recurring line item, not a one-time fee.
Managing agent (the coordinator)
Pathway verification, the three-portal filing chain, the RDP booking, and the mitigation paperwork run through you — including the disaster documentation if the building ever floods or burns.
Shareholders / unit owners (the residents)
LL97 costs reach you through maintenance and common charges either as planned retrofit financing or as unplanned fines — and the planned version is almost always cheaper. The A–F energy grade at the entrance is your building’s public report card.
Frequently asked questions
Does Local Law 97 apply to co-ops and condos?
Yes — co-op and condo buildings over 25,000 square feet (or condo buildings under one board totaling over 50,000 square feet) are covered. The applicable pathway depends on rent-regulation and affordability status: most market-rate buildings face Article 320 caps; buildings over 35% rent-regulated, HDFC, and Mitchell-Lama follow Article 321’s one-time prescriptive measures instead.
What is the LL97 penalty for a co-op?
The same as any Article 320 building: (actual emissions minus the cap) × $268 per ton CO2e per year, and $0.50 per square foot per month for failing to file. Article 321 buildings face $10,000 penalties for late or missing compliance reports.
What changed for partially rent-regulated buildings in 2026?
Buildings with at least one but no more than 35% rent-regulated units (Pathway 1) began cap compliance on January 1, 2026 — 2026 is their first capped calendar year, reportable in 2027.
Did the co-op lawsuit against LL97 succeed?
No. Glen Oaks Village Owners v. City of New York was decided against the challengers by the NY Court of Appeals on May 22, 2025, and cannot be appealed further. LL97 is settled law.
Will LL97 raise my maintenance or common charges?
For buildings over their caps, yes — the only question is whether the increase funds planned retrofits (often with incentives, and timed to equipment replacement) or recurring annual fines. The retrofit usually wins over a ten-year horizon, especially with 2030’s stricter caps.
Where can a board get free LL97 help?
NYC Accelerator (accelerator.nyc/ll97) offers free compliance guidance, and the Building Energy Exchange’s May 2026 “Cutting Carbon in Co-ops & Condos” playbook is written specifically for residential boards.
Co-op and Condo Capital Financing Stack: Eliminating Lump-Sum Special Assessments
The primary political crisis facing co-op and condo boards is the shareholder assessment revolt. When boards present heating plant decarbonization or envelope retrofits as lump-sum capital calls ($20,000 to $50,000 per apartment), shareholders routinely threaten board recalls or litigation. Modern decarbonization governance structures CapEx through long-term, non-accelerating financing instruments layered with utility rebates.
Financing Mechanism
Term & Security
Impact on Shareholder Lien / Resale
Eligible Project Scope
C-PACE (Commercial PACE)
20–30 year fixed-rate financing repaid as a senior voluntary tax assessment via municipal property tax bill.
Transfers automatically with title upon unit sale; never accelerates upon sale; does not impair individual shareholder mortgageability.
100% of hard and soft costs: engineering, electrical switchgear upgrades, heat pumps, building envelope, solar PV.
NYCEEC Clean Energy Debt
5–15 year term loans; subordinated debt or co-op building loan structures.
Secured by building underlying cash flow or assignment of maintenance dues; requires lender consent.
Pre-development studies, design engineering, electrical service risers, heating plant electrification.
Con Edison Clean Heat Rebates
Direct utility capital incentives paid upon verified installation and commissioning.
Non-debt capital infusion directly reducing project net borrowing requirement.
Full-load heat pump space heating (up to $5,000 per dwelling unit market-rate; $12,000–$14,000 affordable) plus DHW heat pumps ($1,000/unit), or custom performance ($200/MMBtu).
10-Year Reserve Amortization
Integrated reserve study allocation paired with annual operating budget escalation (1.5%–3.0%).
Predictable maintenance charge trajectory; prevents sudden special assessment notices during unit resales.
Board Resolution & Shareholder Communication Package
To establish institutional protection against breach-of-fiduciary-duty claims, boards should adopt formal resolutions authorizing technical feasibility studies and establish transparent shareholder communications well in advance of vote milestones.
“WHEREAS, the Corporation is subject to the building energy performance standards and greenhouse gas emissions limitations of NYC Administrative Code § 28-320 (Local Law 97); and
WHEREAS, compliance requires professional engineering analysis of heating plant electrification, electrical service capacity, and capital amortization options;
NOW, THEREFORE, BE IT RESOLVED, that the Board of Directors hereby approves the retention of a New York State licensed Professional Engineer (PE) or Registered Architect (RA) to perform an ASHRAE Level II Energy Audit, electrical load letter evaluation, and statutory Article 320/321 compliance pathway analysis; and
BE IT FURTHER RESOLVED, that the Treasurer and Managing Agent are authorized to solicit non-accelerating financing proposals, including C-PACE financing structures and utility incentive pre-approvals, to present an integrated Decarbonization Capital Plan at the upcoming Shareholder Informational Meeting.”
Shareholder Town Hall Structure: Cost of Inaction vs. Decarbonization
When presenting compliance proposals to shareholders, boards must contrast the Cost of Inaction against the Cost of Financed Decarbonization:
Cost of Inaction: Accumulating annual DOB penalties ($268/tCO2e) beginning in the 2024–2029 cycle and escalating steeply in 2030, compounded by fossil fuel commodity price volatility, deteriorating LL33 letter grades (D or F posted at building entrance), and lender scrutiny on unit buyer mortgages.
Cost of Decarbonization: Net capital outlay after utility equipment rebates, amortized over 20–25 years via C-PACE or energy debt. Because C-PACE is repaid through property tax assessments and transfers with unit title, departing shareholders pay only for their tenure of ownership, while lower operating EUI permanently reduces building operating expenses.
Resale Questionnaire & Lien Search Disclosures
Managing agents must prepare for increasing disclosure requirements on co-op lien searches and institutional buyer questionnaires. Institutional mortgage lenders (including Fannie Mae, Freddie Mac, and private portfolio lenders) now routinely request evidence of LL97 pathway classification, outstanding DOB violations, and projected special assessment liabilities. Boards that fail to adopt an approved capital compliance plan risk having buyer financing rejected by lender underwriting departments. For step-by-step administrative submission protocols, review How to File Local Law 97 on DOB NOW, ESPM, and BEAM.
Notice on Co-op/Condo Governance: This guidance is prepared for condominium unit owners, cooperative shareholders, board directors, and managing agents for capital budgeting and compliance strategy. Regulatory standards reflect NYC Administrative Code § 28-320 and 1 RCNY § 103-14. This analysis does not constitute formal legal counsel, certified engineering filings, or licensed financial underwriting. Boards must consult their corporate legal counsel, managing agent, and a New York State licensed Professional Engineer (PE) or Registered Architect (RA) prior to executing capital assessments or filing compliance documents.